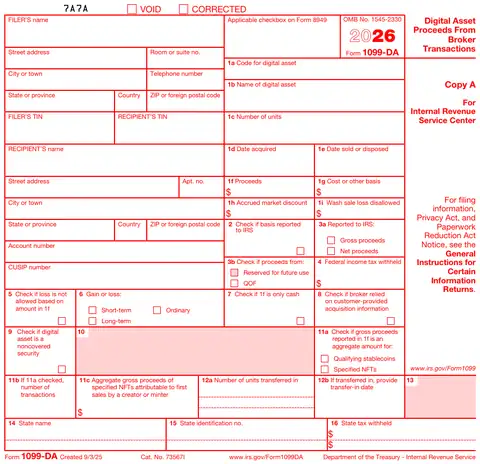
 VOIDPaper only: marks a form on a sheet that should be ignored. It is not a correction; a filed return is undone with a corrected return.How corrections workCORRECTEDChecked on a return that replaces one already filed. Which fields to repeat, and whether two returns are needed, depends on the error.Type 1 vs Type 2 correctionsFiler's nameWhat goes hereThe broker filing the form. Generally only a U.S. digital asset broker reports: a U.S. person, or a U.S. branch treated as one, that effects sales of digital assets for others.Watch forBrokers include kiosk operators, processors of digital asset payments and real estate reporting persons who know digital assets were paid. Providing only validation services, or only wallet hardware or software, does not make you a digital asset middleman.Check the filer blockApplicable checkbox on Form 8949What goes hereA one-letter code for the customer's Form 8949: G short term with basis reported, H short term without, J long term with basis reported, K long term without, Y holding period unknown.Watch forThese are not the Form 1099-B codes (A, B, D, E, X).Calendar yearThe year the payment was made, not the year you file. The 2026 forms cover payments in 2026 and are filed in 2027.The 2027 calendarFiler's street addressStreet or P.O. box of the filer, where the recipient can write about the form. Not matched against IRS records.Filer's room or suiteSecond address line, optional.Box 1a: Code for digital assetWhat goes hereThe nine-character digital token identifier issued by the Digital Token Identifier Foundation (DTIF). Required on every form.Watch forEnter 999999999 if the asset is not registered with DTIF, and for specified NFTs reported under the optional method. For aggregated stablecoins, use the stablecoin's identifier.Click to open the row in the box tableFiler's city or townCity of the filer's address. A foreign filer gives the city and leaves the state blank.Filer's telephone numberRequired: a number the recipient can call about the form, with area code. The recipient copy must carry it.Box 1b: Name of digital assetWhat goes hereThe full name of the digital asset. Required on every form.Watch forIf box 1a holds a DTIF identifier, use the name that matches its DTIF registration. Under the optional NFT method enter "Specified NFTs."Click to open the row in the box tableFiler's state or provinceTwo-letter state code for a U.S. address; the province for a foreign one.Filer's countryBlank or US for a domestic address; the country for a foreign filer.Filer's ZIP or postal codeFive or nine digits for a U.S. address; the foreign postal code otherwise.Filer's TINThe EIN the returns are filed under; it must match the filer name on the first line. A sole proprietor may use an SSN, with the owner's name first.Check the filer blockRecipient's TINWhat goes hereThe customer's SSN, ITIN, ATIN or EIN, requested on Form W-9. Foreign customers give the right Form W-8 instead.Watch forYou may truncate it on the customer's statement, never on the IRS copy. For 2027 sales, Notice 2025-33 lets you rely on an uncertified TIN of a customer with a pre-2026 account if the name and TIN matched in IRS TIN Matching before the sale.Match it before you fileBox 1c: Number of unitsWhat goes hereThe number of units sold, exchanged or otherwise disposed of in the transaction, to 18 decimal places. Required on every form.Watch forUnder an optional reporting method, enter the aggregate number of stablecoin or NFT units.Click to open the row in the box tableRecipient's nameThe name the IRS has for this TIN: an individual's own name for an SSN, the legal name for an EIN; a DBA goes on the second line. This is what TIN matching compares.Which name goes firstBox 1d: Date acquiredWhat goes hereThe acquisition date, MM/DD/YYYY. Required for covered digital assets.Watch forLeave it blank if the units were acquired on various dates, if box 9 is checked and you do not know or choose not to give the date, or under an optional reporting method.Click to open the row in the box tableBox 1e: Date sold or disposedWhat goes hereThe date of sale, MM/DD/YYYY.Watch forRequired except for stablecoins or specified NFTs reported under an optional method, where it may be blank.Click to open the row in the box tableRecipient's street addressWhere the recipient copy is mailed. From the W-9 line 5; the IRS does not match it, but an undeliverable copy is a furnishing failure.Recipient's apartment or suiteSecond address line, optional. Keep it on its own line rather than appended to the street.Box 1f: ProceedsWhat goes hereGross proceeds: cash, and the value of services, digital assets or other property received. Reduce them by transaction fees, commissions and transfer taxes. A loss goes in parentheses.Watch forFirst sales of specified NFTs by a creator or minter go in box 11c, with box 1f blank on that form. Under the stablecoin method, box 1f is the total of the designated sales.Click to open the row in the box tableBox 1g: Cost or other basisWhat goes hereThe adjusted basis of the units sold. Required for covered securities: digital assets acquired after 2025 in an account where you provided custodial services and held there until the sale.Watch forEnter -0- only for a true zero basis. Blank when box 9 is checked and you choose not to report basis, or under an optional method. Customer-provided acquisition information may not be used for basis.Click to open the row in the box tableRecipient's city or townCity of the mailing address, from the W-9 line 6.Box 1h: Accrued market discountWhat goes hereAccrued market discount, for covered digital assets that are also debt instruments for federal income tax purposes.Watch forMay be left blank when box 9 is checked or under an optional reporting method.Click to open the row in the box tableBox 1i: Wash sale loss disallowedWhat goes hereLoss disallowed under section 1091. Required for tokenized securities when the sale and repurchase have the same CUSIP in the same account.Watch forOther disallowed losses are optional. Add the disallowed loss to the basis of the units bought back.Click to open the row in the box tableRecipient's state or provinceTwo-letter state code; it also drives which state copies are needed when there is no withholding.State filing requirementsRecipient's countryBlank or US for a domestic address. A foreign address is a flag to check whether a W-8 and Form 1042-S were the right documents instead.Foreign payeesRecipient's ZIP or postal codeFive or nine digits for a U.S. address, or the foreign postal code.Box 2: Check if basis reported to IRSCheck it whenYou are not checking box 9, or you check box 9 but report basis in box 1g anyway.Watch forDo not check it for stablecoins or specified NFTs reported under an optional method.Click to open the row in the box tableGross proceedsCheck it whenThe digital asset was sold because an option was exercised and box 1f was not reduced by the option premium.Watch forBox 3a applies only to sales from the exercise of an option.Open this box on the IRIS field mapAccount numberWhat goes hereThe account number you assigned to the customer, not the customer's wallet address.Required whenYou file more than one Form 1099-DA for a recipient with multiple accounts. The IRS encourages one on every form.Net proceedsCheck it whenYou reduced box 1f by the option premium for a digital asset sold because an option was exercised.Watch forFor options granted or acquired after 2013, follow Treas. Reg. 1.6045-1(m) on premiums.Open this box on the IRIS field mapBox 4: Federal income tax withheldWhat goes hereBackup withholding, generally 24%, when the customer has not furnished a TIN as required.Watch forNotice 2025-33 waives backup withholding on all digital asset sales in 2025 and 2026. For 2027 sales it is waived for pre-2026 accounts with a non-U.S. address never classified as U.S. persons, and digital-for-digital withholding is limited. Totals go on Form 945.Click to open the row in the box tableCUSIP numberWhat goes hereFor a tokenized security reported transaction by transaction: the CUSIP number or other identifying number.Watch forAll other unnumbered boxes must be completed; this is the one that may be left blank when there is no applicable number.QOFCheck it whenYou report a disposition of an interest in a qualified opportunity fund.Open this box on the IRIS field mapBox 5: Check if loss is not allowed based on amount in 1fCheck it whenBox 1f reports what the customer received in an acquisition of control or substantial change in capital structure reportable on Form 8806, for a digital asset that is also stock.Watch forLeave the other boxes blank unless you combine this with ordinary sale reporting; then box 1g may not exceed box 1f.Click to open the row in the box tableBox 7: Check if 1f is only cashCheck it whenOnly cash was paid as proceeds: U.S. dollars or a government-issued convertible foreign currency.Watch forStill check it when you combined the sale with the units used to pay your broker fee.Click to open the row in the box tableBox 8: Check if broker relied on customer-provided acquisition informationCheck it whenYou received, now or earlier, customer-provided acquisition information to identify which units were sold, even if it was not used for this lot.Watch forNo check is needed once the customer has disposed of all units that information covered. It may be used for lot selection only, not basis or dates.Click to open the row in the box tableShort-termCheck it whenThe gain or loss on covered units is short term under section 1222, applying the gift and inherited property rules.Watch forShort and long term never share a form. Covered short-term and long-term lots from one sale go on separate forms.Open this box on the IRIS field mapOrdinaryCheck it whenAll or part of the gain or loss may be ordinary, along with the short-term or long-term box.Watch forAlways check it for a transaction denominated in a currency other than the U.S. dollar, since it may be a section 988 transaction.Open this box on the IRIS field mapLong-termCheck it whenThe gain or loss on covered units is long term under section 1222.Watch forMay be left blank for a noncovered asset with box 9 checked, or under an optional reporting method.Open this box on the IRIS field mapBox 9: Check if digital asset is a noncovered securityCheck it whenYou choose to flag a noncovered digital asset: one acquired before 2026, transferred in, or not in an account you held in custody when acquired.Watch forChecked, boxes 1d, 1g, 1h, 1i and 6 may be blank and voluntary entries carry no penalty for errors. Unchecked, those boxes are subject to penalties. Never check it under an optional method.Click to open the row in the box tableQualifying stablecoinsCheck it whenYou report designated sales of a qualifying stablecoin under the optional method, in aggregate. Then complete box 11b.ThresholdNo report is needed if the customer's designated stablecoin sales total $10,000 or less for the year. Above that, report each stablecoin's aggregate on its own form.Open this box on the IRIS field mapSpecified NFTsCheck it whenYou report specified NFT sales under the optional method, in aggregate. Then complete box 11b and, for first sales, box 11c.ThresholdNo report is needed if the customer's specified NFT sales total $600 or less for the year.Watch forFirst sales by a creator or minter and other NFT sales go on two separate forms.Open this box on the IRIS field mapBox 11b: If 11a checked, number of transactionsWhat goes hereUnder the optional method for qualifying stablecoins or specified NFTs, the number of transactions reported on this form.Required whenEither box in 11a is checked.Click to open the row in the box tableBox 11c: Aggregate gross proceeds of specified NFTs attributable to first sales by a creator or minterWhat goes hereAggregate gross proceeds from first sales of specified NFTs by the creator or minter.Watch forThese proceeds never go in box 1f. Report them on a separate form from other specified NFT sales, with box 1f blank.Click to open the row in the box tableBox 12a: Number of units transferred inWhat goes hereThe number of units sold that had been transferred into a custodial account at your firm, to 18 decimal places.Watch forMay be blank under an optional reporting method. Transferred-in units are noncovered securities.Click to open the row in the box tableBox 12b: If transferred in, provide transfer-in dateWhat goes hereThe date the units were transferred in, MM/DD/YYYY.Watch forLeave it blank if they were transferred in on various dates, or under an optional reporting method.Click to open the row in the box tableBox 14: State nameWhat goes hereThe state's abbreviated name, for up to two states. Keep each state on its own line.Watch forBoxes 14 to 16 are for your convenience; the IRS does not need them.Click to open the row in the box tableBox 15: State identification no.What goes hereYour state identification number, the number that state assigned to you.Click to open the row in the box tableBox 16: State tax withheldWhat goes hereState income tax withheld from this payment, if any.Watch forA state that wants a paper copy gets Copy 1; the recipient gets Copy 2.Click to open the row in the box table
Hover over a box for what goes in it; click to open its row in the table below. On a touch screen, tap the box to jump to the row.
What Form 1099-DA is
Form 1099-DA, Digital Asset Proceeds From Broker Transactions, is the digital-asset counterpart of Form 1099-B. It was created by the final broker regulations the Treasury issued in July 2024 (T.D. 10000) under the reporting mandate in the 2021 Infrastructure Investment and Jobs Act. A broker files one for each customer for each sale or exchange of a digital asset it effected, showing the date, the asset, the units, the gross proceeds and, from 2026, the cost basis and holding period for assets the broker has basis information for.
Like every other 1099, the form carries the customer’s name and taxpayer identification number, and the IRS matches the two against its records. That is why a form built for crypto ends up governed by the same W-9, CP2100 and backup-withholding rules as a 1099-NEC.
Who has to file
| Filer | Status |
|---|---|
| Custodial brokers: centralized exchanges, hosted-wallet providers, and any platform that takes custody and effects sales for customers | Must file, starting with 2025 transactions |
| Digital-asset payment processors (PDAPs) that accept digital assets on behalf of merchants | Must file, starting with 2025 transactions |
| Real-estate reporting persons (title and closing agents) when digital assets are used as consideration | Report the digital-asset payment for closings on or after January 1, 2026 |
| Non-custodial (“DeFi”) front-end service providers | Not required. The separate December 2024 rule that would have treated them as brokers was repealed by Congress under the Congressional Review Act in April 2025 |
| Miners, stakers, node operators and hardware-wallet makers | Not brokers under the final regulations |
What is reported, and when
| Tax year | Reported on the form | Filed |
|---|---|---|
| 2025 | Gross proceeds of every sale or exchange effected on or after January 1, 2025. Basis is not required | Recipient copy by February 17, 2026 (February 15 is a Sunday); IRS by March 31, 2026 if e-filed |
| 2026 | Gross proceeds, plus cost basis and holding period for “covered” digital assets: those acquired in the customer’s account on or after January 1, 2026 and held there since | Recipient copy by February 16, 2027 (February 15 is Presidents’ Day); IRS by March 31, 2027 if e-filed |
Two optional simplifications exist for high-volume, low-value activity: a broker may report sales of qualifying stablecoins in aggregate when a customer’s total is under $10,000 for the year, and sales of specified NFTs in aggregate under $600. Notice 2024-57 also tells brokers not to report six transaction types until further guidance: wrapping and unwrapping, liquidity-provider transactions, staking, lending, short sales, and notional principal contracts.
Almost every filer will be above the 10-return e-file threshold, so paper is not a practical option. Firms that already file 1099-B through IRIS add 1099-DA to the same feed. FIRE never accepted it: the IRS lists 1099-DA among the forms IRIS takes for tax year 2025, and Publication 1220 has no record layout for it, so a vendor that only writes FIRE files cannot file it.
Box by box
| Box | What it reports | Notes |
|---|---|---|
| 1a | Code for digital asset | RequiredThe nine-character Digital Token Identifier Foundation (DTIF) code for the asset; 999999999 if it is not registered, and for specified NFTs under the optional method. |
| 1b | Name of digital asset | RequiredThe full name of the digital asset, matching its DTIF registration when box 1a has a code. "Specified NFTs" under the optional NFT method. |
| 1c | Number of units | RequiredUnits sold, exchanged or otherwise disposed of, to 18 decimal places; the aggregate units under an optional method. |
| 1d | Date acquired | RequiredFor covered assets. The acquisition date. Blank when units were acquired on various dates, when box 9 is checked and you do not give it, or under an optional method. |
| 1e | Date sold or disposed | The sale date, MM/DD/YYYY. May be blank only for stablecoins or specified NFTs reported under an optional method. |
| 1f | Proceeds | Gross proceeds (cash, services, digital assets or other property received) less transaction fees, commissions and transfer taxes. First sales of specified NFTs by a creator or minter go in box 11c instead. |
| 1g | Cost or other basis | RequiredFor covered assets: acquired after 2025 in an account you held in custody until the sale. Adjusted basis; -0- only for a true zero. Blank for a noncovered asset with box 9 checked if you choose, or under an optional method. |
| 1h | Accrued market discount | Accrued market discount, only for covered digital assets that are also debt instruments. May be blank when box 9 is checked. |
| 1i | Wash sale loss disallowed | Wash sale loss disallowed. Required for tokenized securities sold and bought back with the same CUSIP in the same account; other disallowed losses are optional. |
| 2 | Check if basis reported to IRS | CheckboxCheck it when box 9 is not checked, or when box 9 is checked but you report basis anyway. Never under an optional method. |
| 3a | Reported to IRS: gross proceeds or net proceeds | CheckboxOnly for a sale from the exercise of an option: net proceeds when box 1f was reduced by the option premium, gross proceeds when it was not. |
| 3b | Check if proceeds from a QOF | CheckboxQOF when you report a disposition of an interest in a qualified opportunity fund. |
| 4 | Federal income tax withheld | Backup withholding, generally 24%. Notice 2025-33 waives it on all digital asset sales in 2025 and 2026, so it is normally blank on 2026 forms. Limited relief continues for 2027. Totals go on Form 945. |
| 5 | Check if loss is not allowed based on amount in 1f | CheckboxBox 1f is from an acquisition of control or substantial change in capital structure reportable on Form 8806, for a digital asset that is also stock. |
| 6 | Gain or loss: short-term, long-term, ordinary | CheckboxShort term or long term, never both on one form, plus Ordinary when any part may be ordinary (always for non-dollar transactions). Required for covered assets; may be blank with box 9 checked or under an optional method. |
| 7 | Check if 1f is only cash | CheckboxCheck it when only cash (dollars or a government-issued currency) was paid as proceeds. |
| 8 | Check if broker relied on customer-provided acquisition information | CheckboxCheck it when the customer has given you acquisition information to identify which units were sold, even if not used for this lot, until all units it covers are gone. |
| 9 | Check if digital asset is a noncovered security | CheckboxNoncovered assets only (acquired before 2026, transferred in, or not in your custody when acquired). Checked, boxes 1d, 1g, 1h, 1i, 2 and 6 may be blank. Unchecked, they are subject to penalties. |
| 10 | Reserved | ReservedLeave blank. |
| 11a | Check if gross proceeds reported in 1f is an aggregate amount for qualifying stablecoins or specified NFTs | CheckboxOptional method only. Qualifying stablecoins: aggregate reporting, and no report if designated sales total $10,000 or less. Specified NFTs: aggregate reporting, and no report if sales total $600 or less. Box 11b is then required. |
| 11b | If 11a checked, number of transactions | RequiredWhen box 11a is checked. The number of transactions included in the aggregate on this form. |
| 11c | Aggregate gross proceeds of specified NFTs attributable to first sales by a creator or minter | Aggregate gross proceeds from first sales of specified NFTs by their creator or minter, on a separate form from other NFT sales. Never in box 1f. |
| 12a | Number of units transferred in | Units sold that had been transferred into your custody, to 18 decimal places. May be blank under an optional method. |
| 12b | If transferred in, provide transfer-in date | The transfer-in date. Blank if units came in on various dates, or under an optional method. |
| 13 | Reserved | ReservedLeave blank. |
| 14to16 | State name, state identification number, state tax withheld | OptionalThe IRS does not need them. The state, your state ID number and state tax withheld, for up to two states. A state that wants a paper copy gets Copy 1; the recipient gets Copy 2. |
Codes for the applicable checkbox on Form 8949 (5 codes)
Enter one letter that tells the recipient where to report the digital asset transaction on Form 8949 or Schedule D.
| Code | Meaning | When to use it |
|---|---|---|
| G | Short term, basis reported to the IRS | Matches box G on Form 8949, the short-term part, for transactions with basis reported to the IRS. |
| H | Short term, basis not reported to the IRS | Matches box H on Form 8949, the short-term part, for transactions with basis not reported to the IRS. |
| J | Long term, basis reported to the IRS | Matches box J on Form 8949, the long-term part, for transactions with basis reported to the IRS. |
| K | Long term, basis not reported to the IRS | Matches box K on Form 8949, the long-term part, for transactions with basis not reported to the IRS. |
| Y | Holding period unknown | You cannot tell whether the recipient should check box H or box K on Form 8949. |
Source: Instructions for Form 1099-DA (2026), Applicable Checkbox on Form 8949
Box titles follow the 2026 revision of the form (Copy A above). The IRS reads the filer and recipient name, TIN, address, account number and the money boxes; the state boxes are for the state copy only. Boxes 1d, 1e, 1g, 1h, 1i, 2, 3a, 3b, 5, 6, 8, 9, 12a and 12b may be blank when the broker reports qualifying stablecoins or specified NFTs under the aggregate method. The IRIS field map for Form 1099-DA has every XML element.
The transition relief
The IRS acknowledged that brokers were being asked to build reporting, basis tracking and TIN collection at once, and issued relief in stages.
- Notice 2024-56 (June 2024). No penalties under sections 6721 and 6722 for 2025 gross-proceeds reporting when the broker makes a good-faith effort. No backup withholding on digital-asset sales in 2025. For 2026, no backup withholding on an account opened before January 1, 2026 if the broker submits the customer’s name and TIN to the IRS TIN Matching Program and receives a match. Special relief where a sale is paid in another digital asset the broker would otherwise have to liquidate to withhold.
- Notice 2025-33 (June 2025). Extended the relief by a year: good-faith penalty relief for 2026 reporting, no backup withholding on sales in 2026, and, for 2027, no backup withholding on pre-2026 accounts whose name and TIN the broker has matched through the TIN Matching Program.
The relief is dated, and each notice conditions the later years on TIN matching. Read the current text of Notices 2024-56 and 2025-33 before relying on a specific date; the IRS has already extended once and may change the conditions again.
Why the TIN is the whole game
A crypto platform’s backup-withholding exposure is different from a normal payer’s. It cannot simply hold back 24% of a wire; the “payment” is a sale, often settled in another token, and withholding means liquidating the customer’s asset. The relief above was written around that problem, and the price of the relief is a matched TIN: an account whose name and TIN the broker has run through the IRS TIN Matching Program and received code 0 for.
In practice that turns into three tasks for the compliance team: collect a certified TIN from every U.S. customer at onboarding (a W-9 or an equivalent electronic certification), bulk-match the existing customer base and solicit corrections before the next filing cycle, and keep the solicitation record that makes any penalty on a mismatched TIN waivable. KYC identity verification does not do this; it proves who the customer is, not that the IRS agrees on the name-TIN pair. The crypto and fintech industry page covers the operational side.
If you received one
A 1099-DA means a U.S. broker reported your sales to the IRS. The gross-proceeds figure is not your gain; you subtract your basis on Form 8949 and Schedule D, and for 2025 sales you will need your own basis records because the form does not carry them. If the name or TIN on the form is wrong, tell the broker and give a corrected W-9; an unresolved mismatch is what eventually leads to a B-Notice and 24% withholding on later sales.
Questions people ask
Does TIN matching matter for Form 1099-DA in 2026?
Yes. Notice 2024-56 waived backup withholding on digital-asset sales in 2025. For 2026 the relief is narrower: no backup withholding on an account opened before January 1, 2026 if the broker submits the customer’s name and TIN to the IRS TIN Matching Program and receives a match. An account that was never matched does not get that relief.
How can a crypto exchange validate customer TINs before filing 1099-DA?
Collect a W-9 (or a W-8 from a foreign customer) at signup, check the TIN format, and run the name and TIN pairs through IRS TIN Matching: interactively for a few at a time, or as a bulk file of up to 100,000 records with results within 24 hours. Solicit a corrected W-9 for every mismatch before the filing season. The TIN matching guide covers the result codes and what each one asks you to fix.
Does 1099-DA replace 1099-B for crypto?
Yes. For digital assets, 1099-DA is the form; 1099-B stays for securities. Some brokers reported crypto on 1099-B voluntarily before 2025.
Is there a dollar threshold?
No. Every sale or exchange is reportable regardless of amount, subject only to the optional aggregate reporting for small stablecoin and NFT sales.
Do foreign customers get a 1099-DA?
Generally not, if the broker holds a valid W-8 establishing foreign status. See the W-8 guide.
What about wallet-to-wallet transfers?
A transfer between the customer’s own wallets is not a sale and is not reported, though brokers must track transfers in for basis purposes from 2026.