Everything between the W-9 and the penalty notice
TIN Compliance is a free reference site from TIN Comply: guides, calculators and templates for the people who collect W-9s, file 1099s and answer the IRS when a CP2100 or Notice 972CG arrives, and for the harder months after a penalty is assessed. Not just the rules: the procedures the IRS gives its own examiners, the dates that actually control, and the letters ready to send.
Every page cites its source: IRS publications, the regulations, and the Internal Revenue Manual cited by subsection and date. Free, no signup.
Start with your situation
Fifteen business days to mail B-Notices, thirty until withholding. Everything for the response, in order.
Forty-five days to answer a proposed penalty. What the number means and how to get it waived.
No notice yet, and you would like to keep it that way. The loop, the rules, and the file to run.
A CP15 or CP215, a denied waiver, a Letter 6112, a levy on a vendor. What the IRS does next and the routes still open.
What the IRS tells its own examiners
Publication 1281 tells you what to do with a CP2100. The Internal Revenue Manual tells the IRS what it will do with your response: which arguments the penalty unit is instructed to deny, what the help desk may and may not verify, what the examiner sees on screen, and how a payer record is corrected or voided without anyone writing to you. Every guide below cites the section it comes from.
Your CP2100: what the IRS will and will not do with it
No way to contest it, no record that you got it, destroyed if undeliverable, recreatable for four years, and the script rules the IRS gives its own staff on first and second notices.
How the IRS actually judges a 972CG response
The examiner's checklist from the Internal Revenue Manual: the two questions, the email-solicitation trap, why First Time Abate does not apply, and the one-penalty cascade.
The IRS program that bills you 24% on every 1099 with a blank TIN
Since 2022 a dedicated IRS unit works straight off filed 1099s: no TIN, no Form 945, Letter 6112. What it accepts, what it rejects, and the one document that ends it.
How the IRS selects backup withholding cases: the robot that reads your 1099s
The 2025 IRS robot that compares about 100,000 TINs at a time to pick payers for backup withholding letters, the data it reads, and what to fix.
The TIN Matching program, as the IRS runs it
Who qualifies and how it is checked, the four roles, the resubmit trap, the 96-hour lockout, the proximal-match rule, and the deletion clock on your results.
Intentional disregard: how the IRS decides
The three-element test, the four questions examiners ask, why volume itself is evidence, the cost-of-compliance memo trap, and the uncapped formula for paper filing.
On the clock
FIRE shuts down. Do you have an IRIS TCC?
The FIRE code does not carry over; applications must be in by November 9. Who needs one and a four-week plan.
The $2,000 threshold is here
1099-NEC and MISC move from $600 to $2,000 for payments after 2025. Every figure and date for the season, sourced.
What is set for 2027, and what is pending
Penalty caps up under Rev. Proc. 2025-32, January 31 falls on a Sunday, IRIS only, three new forms, first 1099-DA basis reporting, and automatic penalty relief for Form 945. One page, with sources.
Why this matters more than it used to
The e-file mandate dropped to 10 returns, so the IRS now matches the name and TIN on nearly every 1099 it receives. A dedicated backup withholding unit works straight off those filings and bills 24% on every return filed with a blank TIN; the Treasury Inspector General counted $13.3 billion that payers should have withheld in a single tax year. The per-return penalty for a missing or incorrect TIN is $340 for returns due in 2026 and 2027, with no cap for intentional disregard. A vendor master with a 5% TIN error rate on 2,000 payees is a five-figure exposure every year, before the staff time on B-Notices and backup withholding. Put your own numbers in.
Tools people come back to
Every form, federal and state
One page per information return and per W-9 and W-8 certificate: who files it, the 2026 threshold, the boxes, the due dates, a picture of the form, and the name/TIN errors that put it on a CP2100. The state side is a page per state.
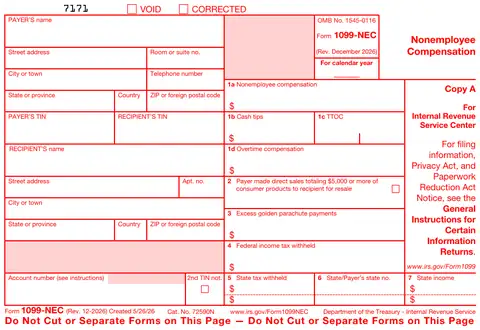 1099-NEC
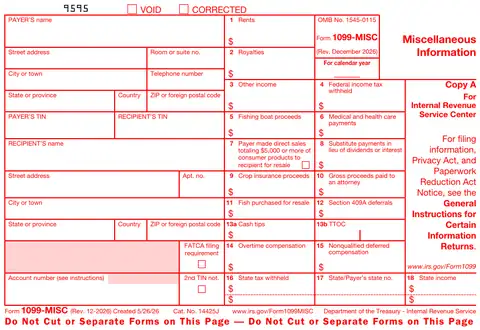 1099-MISC
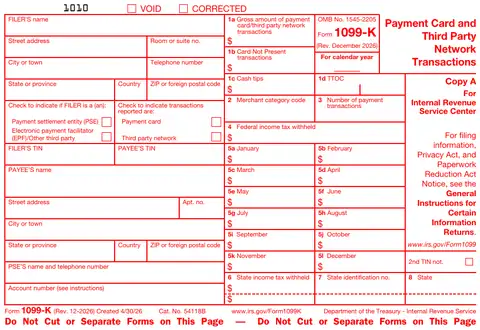 1099-K
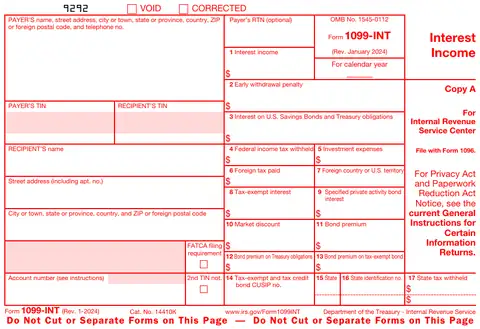 1099-INT
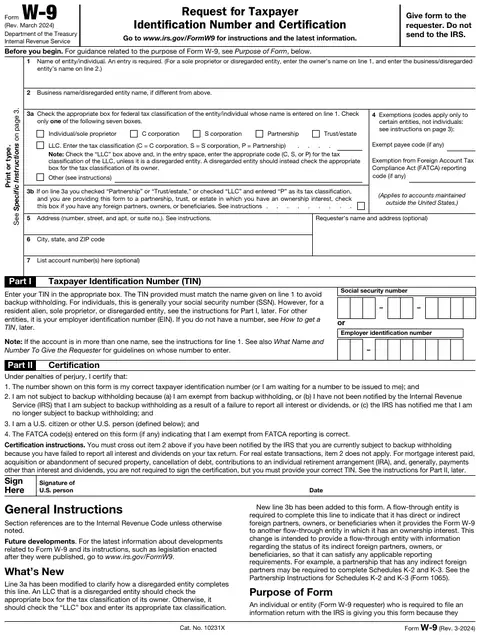 W-9
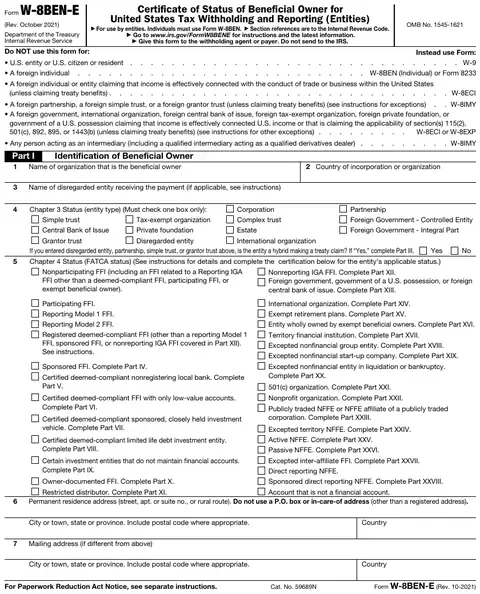 W-8BEN-E
Guides
The loop has six stages and the IRS penalizes the ones you skip: solicit, verify, correct, file, respond, defend. The guides cover each in the order you meet them.
What TIN compliance actually means
The full loop from W-9 to penalty notice, and why TIN matching is one step, not the whole job.
IRS TIN matching: how it works, how to apply, and what the result codes mean
What the IRS compares, what the nine result codes mean, and why a mismatch is not always the vendor's fault.
W-9 solicitation requirements that protect you from penalties
Initial, first-annual and second-annual solicitations, and the records that prove you made them.
IRS CP2100 notice and the B-Notice: what to do, step by step
The 15-day and 30-day clocks, when not to send a notice, and the second-notice rule that trips up most payers.
IRS Notice 972CG: how the penalty is computed and how to get it waived
The 2026 per-return amounts, the 45-day response window, and what a reasonable-cause statement has to prove.
Backup withholding at 24%: when it starts and when it stops
Triggers, deposits, Form 945, and how to stop withholding once a TIN is fixed.
Calculators
For the day a notice lands, and for the questions before it. Everything runs in your browser; nothing you type is sent anywhere.
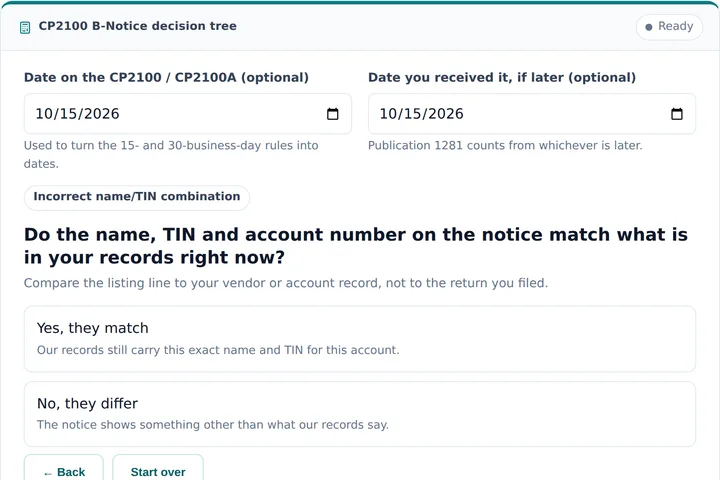
CP2100 B-Notice decision tree
The Publication 1281 flowcharts as questions: for one line on a CP2100, get the required action (no action, records fix, First or Second B-Notice, backup withholding) with the dates.
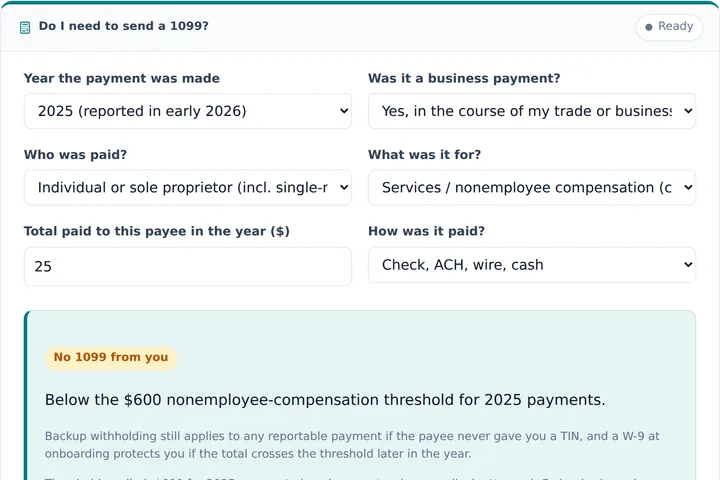
Do I need to send a 1099?
Four questions, the federal answer: which form and box, the threshold for the year, and the corporate, card-payment and foreign-payee exceptions.
TIN format checker
Check whether an SSN, ITIN or EIN is even a valid format before you send it to the IRS. Runs in your browser; nothing is stored.
Missing-TIN exposure calculator
What the IRS backup withholding unit computes on 1099s filed with no TIN: 24% tax, penalties, interest, and what signing the Form 945 saves. From IRM 4.19.26.
Backup withholding calculator
Payment in, 24% withheld and net out, with the Form 945 line and 1099 box each figure goes to.
W-9 date checker for Letter 6112
Paste payees, W-9 dates and first payment dates; see which the backup withholding unit would treat as cleared, exposed or rejectable.
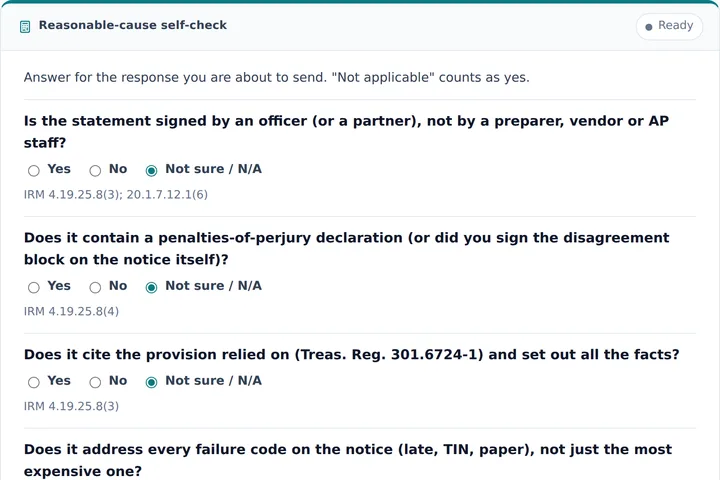
Reasonable-cause self-check
Twelve questions from the examiner's checklist. Find out what would draw a 1948-C, what is denied on sight, and what weakens the substance before you send it.
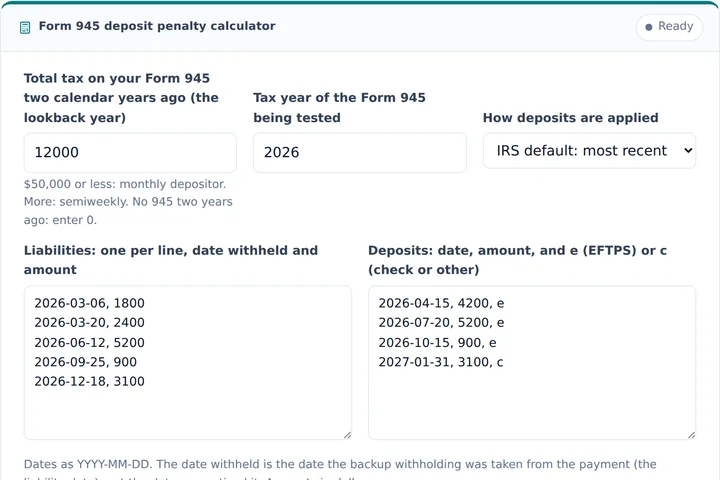
Form 945 deposit penalty calculator
Monthly or semiweekly by the lookback, each deposit due date, and the 2/5/10/15% failure-to-deposit penalty under the IRS default application of deposits or a designated order.
Paying someone outside the United States
A foreign vendor is not a 1099 payee. What you owe them turns on where the work is done and what the payment is: services abroad need only a W-8; royalties, interest and dividends are withheld on at 30% unless a treaty or the Code says otherwise; and the year ends with Forms 1042-S and 1042, not 1099s.
Reference
How to correct a 1099
Type 1 vs Type 2, the wrong-TIN two-step, and why the correction date sets the penalty tier.
Form 945: reporting backup withholding
Due dates, the separate deposit schedule, line 2, and reconciling to box 4.
IRS Letter 147C: how to get one
The EIN verification letter banks, payroll providers and Second B-Notices ask for.
IRS name control rules
The four characters the IRS matches on, the rules by entity type, and a hundred worked examples from the IRS manual.
Form 1099-DA: digital asset sales
Who files it, gross proceeds for 2025 sales, and the first cost basis for assets acquired in 2026.
1099 penalty cases and IRS rulings
Thirty court decisions and IRS rulings on reasonable cause and intentional disregard, each with the lesson for a payer.