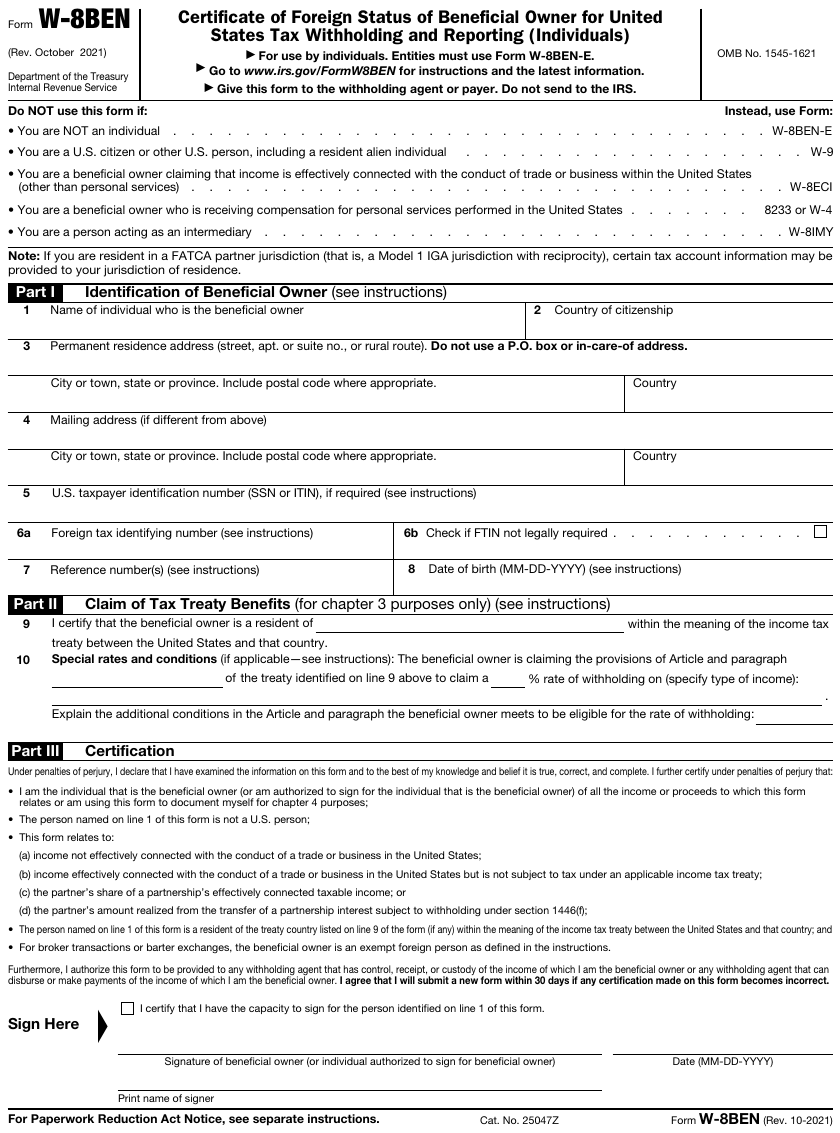
Who completes it and who asks for it
A nonresident alien individual who is the beneficial owner of income subject to withholding completes Form W-8BEN when a withholding agent requests it, whether or not a treaty claim is being made. Entities use W-8BEN-E; individuals whose income is effectively connected with a U.S. trade or business use W-8ECI (compensation for personal services claims a treaty exemption on Form 8233 instead); intermediaries and flow-throughs use W-8IMY. A U.S. citizen or resident alien never completes a W-8BEN, even one living abroad; they complete a W-9.
The withholding agent is any person with control, receipt, custody or disposal of U.S.-source FDAP income paid to a foreign person: a bank paying interest, a company paying royalties or dividends, a platform paying a foreign contractor for services performed in the United States, a casino paying a foreign winner. The agent keeps the form; it is never filed with the IRS.
The lines that matter
| Line | What goes there | Where it goes wrong |
|---|---|---|
| 1 to 4. Name, country of citizenship, permanent residence address, mailing address | The individual's name; a residence address outside the United States that is not a P.O. box or in-care-of address. | A U.S. residence or mailing address, which is a red flag that has to be cured with documentary evidence and an explanation. |
| 5. U.S. TIN | SSN or ITIN, required to claim treaty benefits on most income and for certain accounts; otherwise optional. | A treaty claim with no U.S. TIN and no foreign TIN, which the agent cannot honor. |
| 6a and 6b. Foreign TIN, or reason none | Required for accounts at U.S. offices of financial institutions unless the country does not issue TINs or a listed exception applies. | Left blank on a financial account, making the form invalid for that account. |
| 8. Date of birth | Required for financial accounts. | Omitted. |
| 9 and 10. Treaty country; special rates and conditions | The treaty country of residence, and the article, paragraph and rate for a claim that needs more than residence. | Treaty country that differs from the residence address; a rate claimed for the wrong article (royalties versus services). |
| Part III. Certification | Signed under penalties of perjury by the beneficial owner or an agent with a power of attorney (Form 2848 or equivalent attached); the capacity checkbox. | Unsigned or undated forms; forms signed by an employer or a payer on the payee's behalf. |
What the withholding agent relies on
A valid W-8BEN lets the agent treat the payee as foreign, withhold under chapter 3 at 30% or the treaty rate claimed, and report the payment on Form 1042-S rather than a 1099. It is valid from the date signed through the last day of the third calendar year after that date (a form signed in September 2026 runs through December 31, 2029), or until a change in circumstances such as a move to the United States. The foreign-status portion becomes indefinitely valid when the form is paired with documentary evidence received within 30 days of each other; the treaty portion still expires. An agent may rely on the form unless it knows or has reason to know it is unreliable, which is why a U.S. address, a U.S. phone number or a U.S. place of birth has to be explained and documented.
Without a valid form the presumption rules apply: an individual payee with indicia of U.S. status is presumed U.S. and subject to 24% backup withholding and 1099 reporting; a payee presumed foreign is withheld on at 30% with no treaty benefit. Either way the agent is liable for tax it should have withheld (IRC 1461).
Where these go wrong
- Expired forms. Three-year expiry is the most common failure; calendar the December 31 of the third year when the form is filed. The W-8 request and expiry emails template covers the re-solicitation.
- The wrong W-8. A foreign LLC or corporation on a W-8BEN, or an individual performing services in the United States on a W-8BEN instead of an 8233 or W-8ECI.
- Services performed outside the United States are foreign-source and not reportable at all; the W-8BEN documents status, but it is the place of performance that removes the payment from 1042-S reporting.
- Treaty claims without a TIN. Most treaty claims on non-account income need a U.S. TIN or, for some, a foreign TIN; without one the agent withholds 30%.
Questions people ask about Form W-8BEN
Does a foreign contractor working from their home country need a W-8BEN?
Collect one to document foreign status, but the payment for services performed entirely outside the United States is foreign-source income, not subject to withholding or 1042-S reporting.
How long is it valid?
Through December 31 of the third year after the signature date, unless circumstances change; foreign status can be indefinitely valid with documentary evidence.
Can we accept it electronically?
Yes, through a system meeting the requirements in the Requester instructions and Regulations 1.1441-1(e)(4)(iv), including an electronic signature.
Is it filed with the IRS?
No. The withholding agent keeps it and reports the payment on Form 1042-S.
The other certification forms
W-9 · W-9S · W-8BEN-E · W-8ECI · W-8EXP · W-8IMY · Comparison table
Sources: Form W-8BEN and instructions (Rev. October 2021); Instructions for the Requester of Forms W-8BEN, W-8BEN-E, W-8ECI, W-8EXP and W-8IMY (Rev. June 2022); Publication 515; Regulations 1.1441-1.