Who completes it and who asks for it
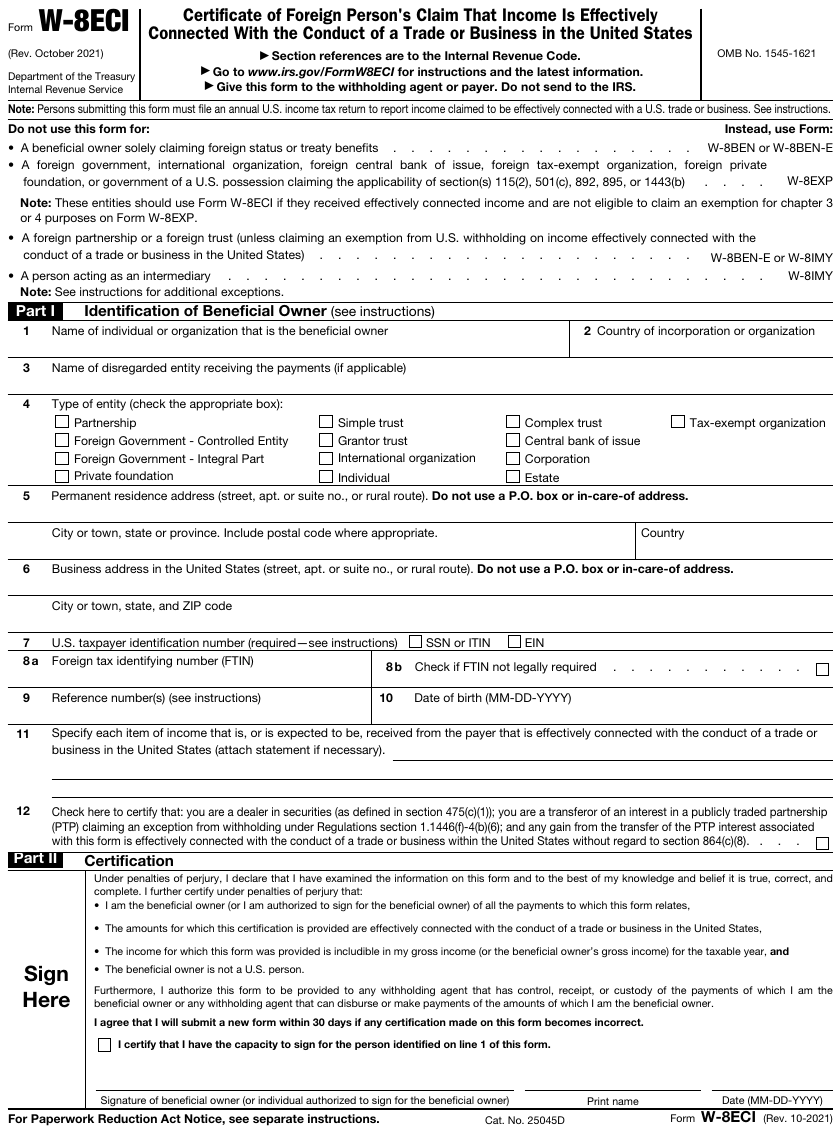
A foreign individual or entity that receives income effectively connected with the conduct of a trade or business in the United States completes Form W-8ECI: a foreign owner of a U.S. rental building who has elected to treat the rents as ECI, a foreign company's U.S. branch, a foreign partner receiving certain distributions, a foreign corporation providing services through a U.S. office. It cannot be used for personal services income of an individual (that is Form 8233 or a W-4), for income that is not effectively connected, or by an intermediary. A separate form is required for each withholding agent, and the form lists the specific items of income it covers.
The withholding agent requesting it is the person paying the ECI: a tenant or property manager paying a foreign landlord, a customer of a U.S. branch, a partnership. The agent keeps the form and reports the payment on Form 1042-S with exemption code 01 (effectively connected income).
The lines that matter
| Line | What goes there | Where it goes wrong |
|---|---|---|
| 1 to 6. Name, country, entity type, addresses | Legal name, country of organization or citizenship, chapter 3 status, permanent residence address outside the United States and the U.S. business address. | Missing U.S. business address; a disregarded entity completing the form in its own name. |
| 7. U.S. TIN | Required. SSN, ITIN or EIN; the form is invalid without one. | Submitted with "applied for"; unlike the W-8BEN this form cannot be accepted without a number. |
| 8 and 9. Reference number; date of birth | Optional reference; date of birth for individuals with financial accounts. | |
| 11. Specify each item of income | The specific types of income the certificate covers (rents from a named property, fees under a contract). | Left generic, so the agent cannot tell which payments are covered. |
| 12. Dealer and section 1446(f) certifications | Certifications relating to transfers of partnership interests and dealer status, added in the 2021 revision. | Skipped by payees for whom they apply. |
| Part II. Certification | Signed under penalties of perjury, including that the income is includible in gross income on a U.S. return and that the payee will file one. | Unsigned; signed by an agent without authority. |
What the withholding agent relies on
A valid W-8ECI relieves the agent of chapter 3 withholding on the income listed, because the foreign person will pay tax on it directly on Form 1040-NR or 1120-F; the agent still reports it on Form 1042-S and, for a partnership allocating ECI to a foreign partner, section 1446 withholding continues under its own rules. Validity is the three-year rule. The agent may not rely on the form for income not listed on line 11, for a payee without a U.S. TIN, or when it knows the income is not effectively connected (a foreign landlord who has not made the net election, for example).
Where these go wrong
- Foreign landlords. Rents on U.S. real property are FDAP subject to 30% unless the owner elects to treat them as ECI under section 871(d) or 882(d); the W-8ECI is the certificate, and the property manager is the withholding agent who is liable if it is missing.
- No TIN, no form. A foreign owner who has not obtained an EIN or ITIN cannot give a valid W-8ECI; withhold 30% until they do.
- Mixed income. A payee with both ECI and FDAP income needs a W-8ECI for the ECI and a W-8BEN or W-8BEN-E for the rest.
Questions people ask about Form W-8ECI
Is the income still reported to the IRS?
Yes, on Form 1042-S, with the exemption code for effectively connected income and no chapter 3 withholding.
Can an individual use W-8ECI for consulting fees earned in the United States?
No. Compensation for personal services of an individual is documented on Form 8233 (treaty claim) or Form W-4, not W-8ECI.
How long is it valid?
Through December 31 of the third year after signature, unless circumstances change or the income listed changes.
The other certification forms
W-9 · W-9S · W-8BEN · W-8BEN-E · W-8EXP · W-8IMY · Comparison table
Sources: Form W-8ECI and instructions (Rev. October 2021); Instructions for the Requester of Forms W-8 (Rev. June 2022); Publication 515; Regulations 1.1441-4.