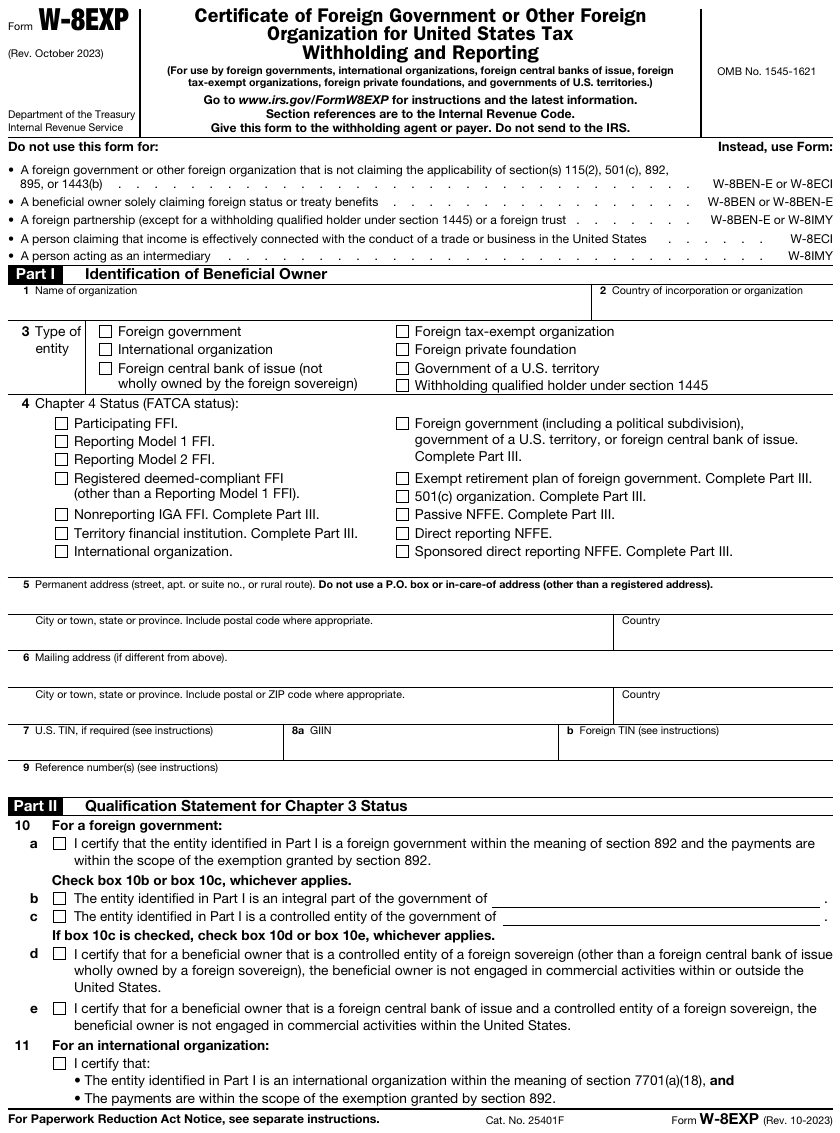
Who completes it and who asks for it
Form W-8EXP is completed by a foreign government or its integral part or controlled entity claiming the section 892 exemption for investment income; an international organization designated under the International Organizations Immunities Act claiming section 892; a foreign central bank of issue claiming section 895 or 892; a foreign tax-exempt organization claiming section 501(c) status (attaching an IRS determination letter or an opinion of U.S. counsel); a foreign private foundation subject to the 4% tax under section 4948; and the government of a U.S. possession claiming section 115(2). These bodies use W-8BEN-E instead when claiming a treaty rate or receiving income the exemption does not cover, and W-8ECI for effectively connected commercial income.
The withholding agent is whoever pays the income: a bank or broker holding a sovereign fund's account, a university paying a foreign foundation, a company paying a foreign government's royalty. The agent keeps the form and reports the payment on Form 1042-S with the applicable exemption code.
The lines that matter
| Part | What goes there | Where it goes wrong |
|---|---|---|
| I, lines 1 to 4 | Name, country, chapter 3 status (the six categories above) and chapter 4 status. | A commercial entity owned by a government claiming section 892 for commercial activity income, which the exemption does not cover. |
| I, lines 5 to 9 | Permanent address, U.S. TIN if any, GIIN if the entity is an FFI, foreign TIN. | A foreign tax-exempt organization that is an FFI omitting the GIIN. |
| II. Qualification statement | The certification matching the status claimed: for a government, that the income is from investments and not commercial activities; for a tax-exempt organization, the determination letter or counsel's opinion and, for a private foundation, the 4% statement. | The wrong box for the body's status; no determination letter or opinion attached for a 501(c) claim. |
| III. Certification | Signed under penalties of perjury by an authorized official. | Unsigned or signed by the wrong office. |
What the withholding agent relies on
A valid W-8EXP lets the agent exempt the covered income from chapter 3 withholding (or apply the 4% rate to a private foundation) and document the entity's chapter 4 status. Unlike the other W-8s, a W-8EXP from a foreign government, international organization, central bank or tax-exempt organization is generally valid indefinitely absent a change in circumstances, provided the supporting determination letter or opinion remains current; the three-year rule applies where the form supports a claim that depends on documentary evidence. The agent must still withhold on income the exemption does not reach, such as a government's income from commercial activities or a foreign charity's unrelated business income.
Where these go wrong
- Grants to foreign charities. A U.S. foundation paying a foreign NGO usually needs a W-8BEN-E with the active-NFFE or nonprofit certification, not a W-8EXP, unless the NGO is claiming section 501(c) status with a determination letter or counsel's opinion.
- Sovereign wealth funds. Section 892 covers investment income of the government or its controlled entity, not income from commercial activities; the form's Part II certification is the line the agent relies on.
- Names. Government ministries and agencies file under long official names; the 1042-S recipient name should match the form exactly.
Questions people ask about Form W-8EXP
Our university pays a foreign university for research. W-8EXP?
Only if the foreign university is claiming section 501(c) status with a determination letter or U.S. counsel's opinion, or is an integral part of a foreign government claiming section 892. Otherwise it gives a W-8BEN-E, and services performed abroad are not subject to withholding anyway.
How long is it valid?
Generally indefinitely for governments, international organizations, central banks and tax-exempt organizations, unless circumstances change or the supporting letter lapses.
Does it cover treaty claims?
No. A treaty rate is claimed on W-8BEN-E.
The other certification forms
W-9 · W-9S · W-8BEN · W-8BEN-E · W-8ECI · W-8IMY · Comparison table
Sources: Form W-8EXP and instructions (Rev. October 2023); Instructions for the Requester of Forms W-8 (Rev. June 2022); Publication 515; IRC 115, 501(c), 892, 895, 1443(b).