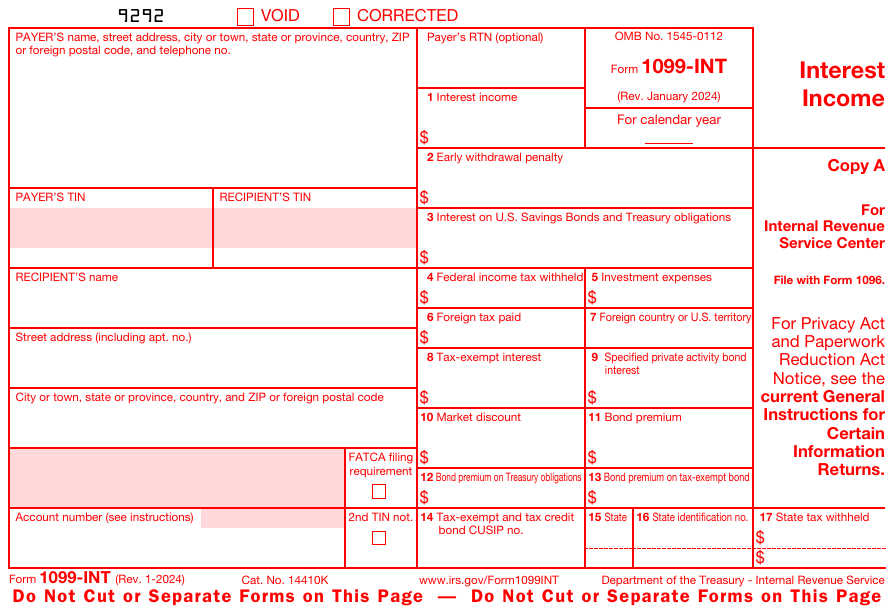
Who must file Form 1099-INT
File Form 1099-INT for each person to whom you paid $10 or more of interest reportable under section 6049 (deposits, bonds, notes, Treasury obligations, tax-exempt bonds), from whom you withheld and paid any foreign tax on interest, or from whom you withheld any federal income tax under backup withholding regardless of amount. Interest paid in the course of your trade or business that is not bank-type interest, such as interest on a late-paid vendor invoice or a seller-financed note, is reportable at the section 6041 amount.
Report only interest paid in the course of a trade or business. No return is required for payments to exempt recipients: corporations, tax-exempt organizations, IRAs, governments, registered securities dealers and the other categories in Regulations 1.6049-4(c).
Threshold: $10, $10 or more; interest paid in the course of a trade or business other than by a financial institution follows the higher section 6041 amount ($2,000 for 2026); any amount if backup withholding applied.
What is reported, box by box
| Box | What it reports | Notes |
|---|---|---|
| 1 | Interest income | Taxable interest not included in box 3, including interest on bank deposits, corporate bonds and seller-financed mortgages. |
| 2 | Early withdrawal penalty | Interest or principal forfeited on early withdrawal of a time deposit. |
| 3 | Interest on U.S. Savings Bonds and Treasury obligations | Reported separately because it is exempt from state tax. |
| 4 | Federal income tax withheld | Backup withholding; Form 945. |
| 5 | Investment expenses | Single-class REMIC only. |
| 6 and 7 | Foreign tax paid and country | Foreign tax on interest, if you withheld and paid it. |
| 8 | Tax-exempt interest | Municipal bond interest of $10 or more. |
| 9 | Specified private activity bond interest | The AMT-preference portion of box 8. |
| 10 to 13 | Market discount and bond premium | Market discount under a section 1278(b) election; bond premium on taxable, Treasury and tax-exempt bonds. |
| 14 | Tax-exempt and tax credit bond CUSIP | CUSIP number, or 'various'. |
| 15 to 17 | State information | Convenience boxes. |
Box titles follow the current revision of the form. The IRS reads the payer and recipient name, TIN, address, account number and the money boxes; the state boxes are for the state copy only.
Payments that are not reported on Form 1099-INT
- Interest paid to an exempt recipient (corporation, tax-exempt organization, IRA, U.S. or state government, foreign government, international organization, securities or commodities dealer, real estate investment trust, common trust fund).
- Interest on obligations issued by an individual, and most interest paid outside the United States by a non-U.S. payer.
- Interest paid to a nonresident alien that is reportable on Form 1042-S instead (bank deposit interest to residents of certain countries is reported on 1099-INT under Regulations 1.6049-8).
- Interest that is OID (Form 1099-OID) and imputed interest on below-market loans, which have their own rules.
Due dates and extensions
| Copy | Due | For 2026 returns |
|---|---|---|
| To the IRS, paper | February 28 | Monday, March 1, 2027 (February 28 is a Sunday) |
| To the IRS, electronic | March 31 | Wednesday, March 31, 2027 |
| To the recipient | January 31 | Monday, February 1, 2027 (January 31 is a Sunday) |
An automatic 30-day extension is available on Form 8809, filed by the due date on paper or through IRIS; a second 30 days requires a hardship showing. Recipient statements can be extended 30 days on Form 15397, online or by fax only. 10 or more information returns of any type in aggregate must be e-filed (T.D. 9972); IRIS is the only IRS intake system from filing season 2027, FIRE having been retired. A payer who e-files the originals must e-file the corrections.
For 2026 forms filed in 2027: January 31 falls on a Sunday, so that deadline moves to Monday, February 1, 2027; February 28 also falls on a Sunday, so the paper deadline moves to Monday, March 1, 2027. March 31 (electronic) and March 15 are weekdays. February 28 does not become February 29 in a leap year. The compliance calendar has every date with the weekend shifts applied.
Backup withholding and TIN matching
Interest is a section 6049 payment, so 24% backup withholding applies when the payee fails to furnish a TIN, fails to certify it under penalties of perjury for accounts opened after 1983, is named on a CP2100, or is a notified payee under-reporter (a C-Notice). The certification requirement is what makes the account-opening W-9 mandatory for banks: an uncertified TIN on an interest account is treated as missing. This is also one of the two payment types with the 60-day awaiting-TIN exemption: a payee who writes "Applied For" and signs the W-9 gets 60 days before withholding must begin.
Form 1099-INT payers may use the IRS TIN Matching program; large financial institutions run it in bulk at onboarding and again before filing.
Name and TIN errors on this form
Every information return is matched by the IRS on the first four characters of the payee's name (the name control) against the TIN. A mismatch produces a CP2100 line the following autumn and, unless the solicitation record is in order, a 972CG penalty the year after: $340 per return for 2026 forms filed in 2027 that are late or wrong, $690 for intentional disregard, with annual maximums of $4,191,500 ($1,397,000 for small filers) under Rev. Proc. 2025-32. The errors that recur on Form 1099-INT:
- Joint accounts. The first name line carries the owner whose TIN is on the return; other joint owners may be listed below. The IRS name control comes from that first name.
- Trust and custodial accounts. A revocable living trust reported under the grantor's SSN uses the grantor's name first; a trust with its own EIN uses the trust's legal name. Mixing the two is a classic CP2100 line.
- Minor's accounts (UTMA). The minor's name and SSN, not the custodian's.
- Name changes. Marriage and divorce leave the bank's record updated and the SSA's not; the 1099-INT then fails on name control. Tell the customer to file SSA Form SS-5 first.
- Deceased account holders. Interest after death is reported to the estate's EIN or the surviving joint owner's SSN.
The name control calculator shows what the IRS will derive from a name line, and the CP2100 guide covers what to do when the notice arrives.
Recipient statements and substitutes
Form 1099-INT is subject to the statement mailing rules: the mailing may contain only the statement, a W-9 or W-8, a check or a letter explaining why there is none, the year-end account statement and a letter of tax consequences, with no advertising, and the envelope must carry the legend Important Tax Return Document Enclosed unless it contains only tax statements. A substitute Copy B must use the official box captions and numbers, show the OMB number and the tax year, form number and form name together in one place, bold the federal income tax withheld caption, and include a direct-access telephone number (Publication 1179, section 4.1). Statements may be furnished electronically only to a recipient who has affirmatively consented in a way that shows they can access the format, after the disclosures in Pub 1099 part M, and must stay posted through October 15. Copy B may show a truncated TIN (xxx-xx-1234); the IRS copy never may.
Corrections and state copies
A wrong amount, code or checkbox is a Type 1 correction: one corrected return with the CORRECTED box checked. A wrong or missing payee TIN, a wrong payee name, or the wrong form type is a Type 2 correction: a zeroed-out copy of the original plus a new original, in that order. Publication 1099 also says you are not required to file a correction for a missing or incorrect TIN if you meet the reasonable-cause standard, only to use the right TIN on the next return, although the IRS encourages the correction. Details and the paper error charts are on the 1099 corrections page.
Form 1099-INT is a Combined Federal/State Filing program form: e-file it with the CF/SF election and the IRS forwards it to participating states. Whether that satisfies a given state, or the state wants a direct filing with its own transmittal, is on each state pages.
Questions people ask about Form 1099-INT
Do we send a 1099-INT for interest of $8?
Not required, unless you backup withheld on it. Many institutions issue below $10 anyway, which the IRS permits.
Does interest on a late vendor payment get a 1099-INT?
Yes if it reaches the section 6041 amount ($2,000 for 2026) and the vendor is not a corporation; it is 'interest paid in the course of your trade or business' rather than bank interest.
What is a C-Notice?
The IRS's instruction to start backup withholding because the payee under-reported interest or dividends. It applies only to interest and dividend accounts and lasts until the IRS says stop, usually the following January 1. See the financial institutions page.
Is 1099-INT in the Combined Federal/State program?
Yes. E-filing with the CF/SF election forwards the return to participating states; whether that satisfies the state is on each state page.
Other federal forms
1042-S · 1097-BTC · 1098 · 1098-C · 1098-E · 1098-F · 1098-Q · 1098-T · 1098-VLI · 1099-A · 1099-B · 1099-C · 1099-CAP · 1099-DIV · 1099-G · 1099-K · 1099-LS · 1099-LTC · 1099-MISC · 1099-NEC · 1099-OID · 1099-PATR · 1099-Q · 1099-QA · 1099-R · 1099-S · 1099-SA · 1099-SB · 3921 · 3922 · 5498 · 5498-ESA · 5498-SA · W-2G · 1099-DA · Comparison table
Sources: IRS Publication 1099 (2026), General Instructions for Certain Information Returns, which replaced the separate General Instructions starting with tax year 2026; Instructions for Forms 1099-INT and 1099-OID (Rev. January 2024); Pub 1099 (2026); IRC 6049, 3406; Regulations 1.6049-4, 31.3406(g)-3. Threshold amounts are indexed for inflation from calendar year 2027; check IRS.gov/InflationAdjustment for the current year.