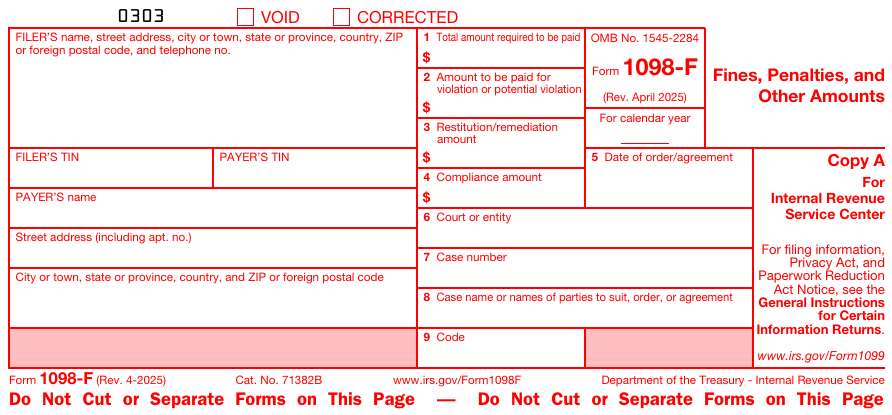
Who must file Form 1098-F
The appropriate official of a government or governmental entity, including a nongovernmental entity treated as governmental under section 162(f)(5) (a self-regulatory organization exercising governmental powers), must file Form 1098-F when a court order, settlement or other agreement with respect to a violation or potential violation of a law requires a payer to pay $50,000 or more in total. Amounts to be paid under several agreements for the same violation are aggregated; when the total is not yet identified but is reasonably expected to reach $50,000, file with $50,000 in box 1 and code E in box 9. Multiple payers jointly liable each receive a form for the full amount with code B.
The form implements section 162(f), which bars deductions for fines and penalties but allows restitution and compliance costs the agreement identifies as such; the payer uses the boxes to support its own deduction.
Threshold: $50,000, aggregate amount the payer is required to pay under the suit, order or agreement, including amounts to be paid over time and amounts not yet determined that the entity reasonably expects to reach the threshold.
What is reported, box by box
| Box | What it reports | Notes |
|---|---|---|
| 1 | Total amount to be paid pursuant to the suit, order or agreement | |
| 2 | Amount to be paid for violation or potential violation | The nondeductible fine or penalty portion. |
| 3 | Restitution / remediation amount | Deductible if identified in the agreement. |
| 4 | Compliance amount | Cost of coming into compliance with the law. |
| 5 | Date of order or agreement | The date the order became binding or the agreement was fully executed. |
| 6 | Court or entity | |
| 7 | Case number | |
| 8 | Case name or names of parties | |
| 9 | Code | A through E: multiple payers, multiple payments, property, services, amounts not identified, and combinations. |
Box titles follow the current revision of the form. The IRS reads the payer and recipient name, TIN, address, account number and the money boxes; the state boxes are for the state copy only.
Payments that are not reported on Form 1098-F
- Suits, orders or agreements under $50,000 in aggregate.
- Amounts paid under agreements that are not for a violation or potential violation of a law (ordinary contract settlements).
- Orders or agreements that became binding before January 1, 2022, the effective date of the final section 6050X regulations.
Due dates and extensions
| Copy | Due | For 2026 returns |
|---|---|---|
| To the IRS, paper | February 28 | Monday, March 1, 2027 (February 28 is a Sunday) |
| To the IRS, electronic | March 31 | Wednesday, March 31, 2027 |
| To the recipient | January 31 | Monday, February 1, 2027 (January 31 is a Sunday) |
An automatic 30-day extension is available on Form 8809, filed by the due date on paper or through IRIS; a second 30 days requires a hardship showing. Recipient statements can be extended 30 days on Form 15397, online or by fax only. 10 or more information returns of any type in aggregate must be e-filed (T.D. 9972); IRIS is the only IRS intake system from filing season 2027, FIRE having been retired. A payer who e-files the originals must e-file the corrections.
For 2026 forms filed in 2027: January 31 falls on a Sunday, so that deadline moves to Monday, February 1, 2027; February 28 also falls on a Sunday, so the paper deadline moves to Monday, March 1, 2027. March 31 (electronic) and March 15 are weekdays. February 28 does not become February 29 in a leap year. The compliance calendar has every date with the weekend shifts applied.
Withholding and TIN matching
The payer pays the government, not the other way round, so backup withholding cannot apply and the form is not in the IRS TIN Matching program. The payer's name and TIN come from the settlement paperwork; because the payer is usually a corporation named in the caption of a case, the return should carry the legal entity that is liable under the agreement, not a parent or a trade name used in the pleadings.
Name and TIN errors on this form
Every information return is matched by the IRS on the first four characters of the payee's name (the name control) against the TIN. A mismatch produces a CP2100 line the following autumn and, unless the solicitation record is in order, a 972CG penalty the year after: $340 per return for 2026 forms filed in 2027 that are late or wrong, $690 for intentional disregard, with annual maximums of $4,191,500 ($1,397,000 for small filers) under Rev. Proc. 2025-32. The errors that recur on Form 1098-F:
- Caption name versus legal name. "ABC Holdings, d/b/a ABC Stores" in a consent decree is reported under the entity that signed and is liable, with its EIN.
- Multiple defendants. One form per payer, each with the full amount and code B, each under its own TIN.
- Individuals. An individual respondent is reported under their own SSN, not the business they operate.
The name control calculator shows what the IRS will derive from a name line, and the CP2100 guide covers what to do when the notice arrives.
Recipient statements and substitutes
The recipient statement for Form 1098-F need not be a copy of the official form: a substitute may be combined with other account statements or reports, provided every required item is numbered and titled as on the official form, the tax year, form number and form name appear together, the recipient instructions are included, and, for the forms Pub 1099 lists, a telephone number with direct access to someone who can answer questions is shown. Publication 1179 (Rev. Proc. 2026-18) has the specifications; logos, slogans and advertising are not permitted on the statement itself. Statements may be furnished electronically only to a recipient who has affirmatively consented in a way that shows they can access the format, after the disclosures in Pub 1099 part M, and must stay posted through October 15. Copy B may show a truncated TIN (xxx-xx-1234); the IRS copy never may.
Corrections and state copies
A wrong amount, code or checkbox is a Type 1 correction: one corrected return with the CORRECTED box checked. A wrong or missing payee TIN, a wrong payee name, or the wrong form type is a Type 2 correction: a zeroed-out copy of the original plus a new original, in that order. Publication 1099 also says you are not required to file a correction for a missing or incorrect TIN if you meet the reasonable-cause standard, only to use the right TIN on the next return, although the IRS encourages the correction. Details and the paper error charts are on the 1099 corrections page.
Form 1098-F is not in the Combined Federal/State Filing program, so any state that requires it must receive it directly. Requirements by state are on the state pages.
Questions people ask about Form 1098-F
Does the payer need the 1098-F to deduct restitution?
The payer needs the agreement to identify the restitution or compliance amount; the 1098-F is the government's report of the same figures and the IRS matches the two.
The settlement total is confidential.
The reporting requirement is statutory; the return goes to the IRS and the payer only, and the payer's statement copy may be furnished electronically with consent.
Is 1098-F in the Combined Federal/State program?
No.
Other federal forms
1042-S · 1097-BTC · 1098 · 1098-C · 1098-E · 1098-Q · 1098-T · 1098-VLI · 1099-A · 1099-B · 1099-C · 1099-CAP · 1099-DIV · 1099-G · 1099-INT · 1099-K · 1099-LS · 1099-LTC · 1099-MISC · 1099-NEC · 1099-OID · 1099-PATR · 1099-Q · 1099-QA · 1099-R · 1099-S · 1099-SA · 1099-SB · 3921 · 3922 · 5498 · 5498-ESA · 5498-SA · W-2G · 1099-DA · Comparison table
Sources: IRS Publication 1099 (2026), General Instructions for Certain Information Returns, which replaced the separate General Instructions starting with tax year 2026; Instructions for Form 1098-F (Rev. April 2025); Pub 1099 (2026); IRC 6050X, 162(f); Regulations 1.6050X-1. Threshold amounts are indexed for inflation from calendar year 2027; check IRS.gov/InflationAdjustment for the current year.