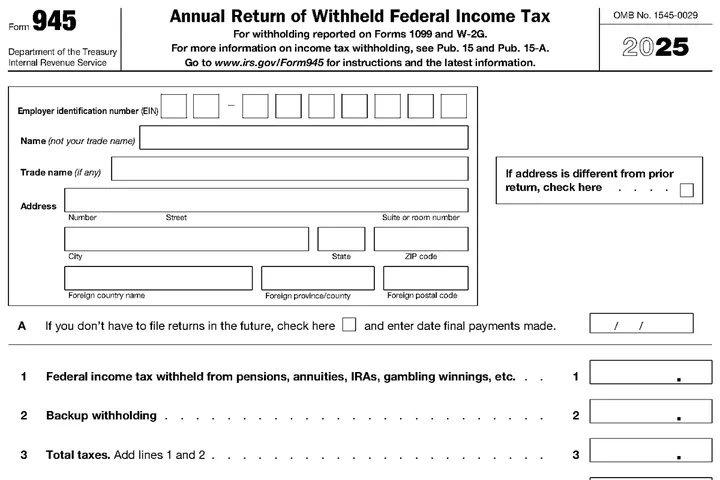
What Form 945 covers
Form 945, Annual Return of Withheld Federal Income Tax, reports income tax withheld from payments that are not wages: backup withholding on 1099 payments, withholding from pensions, annuities and IRA distributions, withholding on gambling winnings, military retirement, and Indian gaming profits. Wage withholding stays on Form 941 (or 944); the two must never be mixed, and deposits for each are made under separate tax types in EFTPS.
A payer files one Form 945 per EIN per year, regardless of how many 1099 types the withholding came from. If you withheld nothing during the year and have no 945 filing requirement, you do not file a zero return unless the IRS has told you to.
Due dates
| Item | Date |
|---|---|
| Form 945 for 2025 | February 2, 2026 (January 31 is a Saturday). February 10 if every deposit was made on time and in full |
| Form 945 for 2026 | February 1, 2027 (January 31 is a Sunday); February 10 with timely deposits |
| Form 945-A (daily liability record) | Attached to the 945 by semiweekly depositors and by anyone who hit the $100,000 next-day rule |
The return is filed electronically through an authorized provider or the Modernized e-File system, or on paper to the address in the instructions. It is separate from the 1099 filing; a payer files the 1099s (showing each payee’s withholding in box 4) by the 1099 due dates and the 945 by the dates above.
The deposit schedule
Deposits go through EFTPS, and the schedule is determined by a lookback period that is different from the 941 lookback: the total tax reported on your Form 945 for the second preceding calendar year. For 2026 deposits, that is the 2024 return.
| If 945 tax in the lookback year was | You are | Deposit by |
|---|---|---|
| $50,000 or less | A monthly depositor | The 15th of the following month |
| More than $50,000 | A semiweekly depositor | Wednesday for withholding on Wednesday–Friday payments; Friday for Saturday–Tuesday payments |
| Any amount, if you accumulate $100,000 or more on any day | Subject to the next-day rule | The next business day, and semiweekly for the rest of the year and the following year |
| Less than $2,500 for the whole year | Exempt from deposits | May pay with the return, if you were not already required to deposit |
A new payer with no 945 history is a monthly depositor in its first year. Because most companies backup withhold only occasionally, they are almost always monthly depositors, and the practical failure is not the schedule but forgetting that a one-off withholding in March creates a deposit due April 15.
Backup withholding is deposited under Form 945, tax type 945, in EFTPS. Depositing it with the payroll 941 deposit is the single most common Form 945 error, and it produces a notice on both returns.
The lines that matter
| Line | What goes there |
|---|---|
| 1 | Federal income tax withheld from pensions, annuities, IRAs, gambling winnings and other nonpayroll payments (not backup withholding) |
| 2 | Backup withholding: the total taken from all payees under section 3406 during the year |
| 3 | Total taxes (lines 1 + 2). If $2,500 or more, complete the monthly summary (line 7) or attach Form 945-A |
| 4 | Total deposits for the year, including any overpayment applied from the prior year |
| 5 / 6 | Balance due or overpayment |
| 7 | Monthly summary of liability, for monthly depositors with line 3 of $2,500 or more |
Reconciling to the 1099s
The IRS compares line 2 of the 945 with the sum of box 4 (federal income tax withheld) across every 1099 you filed under the same EIN. They should be equal. Before you file either, run the reconciliation yourself: the withholding ledger in accounts payable, the box 4 totals in the 1099 file, the EFTPS deposit history, and the 945 draft all showing the same number. A payee who was withheld on must receive a 1099 even if their payments were below the reporting threshold, because the withholding itself is reportable and is their credit.
The backup withholding calculator shows where each figure lands, and the year-round checklist puts the reconciliation in December, before either return is filed.
Mistakes that generate notices
- Withholding shown on 1099s with no Form 945 filed. The IRS sees box 4 amounts, finds no return, and issues a notice for the missing 945.
- Depositing 945 tax as 941 tax. Creates an underpayment on the 945 and an overpayment on the 941; fixing it means a call or a letter.
- Late deposits. Failure-to-deposit penalties of 2% (1–5 days late), 5% (6–15 days), 10% (over 15 days) and 15% (tax still unpaid more than 10 days after the first notice), the same schedule as payroll, plus a flat 10% for a required deposit not made through EFTPS (IRM 20.1.4.7.1)IRM 20.1.4.7.1Internal Revenue Manual, irs.gov. The 15% tier is held five cycles to let a payment post, so paying the CP 161 inside its window avoids it (IRM 20.1.4.14.4)IRM 20.1.4.14.4Internal Revenue Manual, irs.gov.
- Paying with the return at $2,500 or more. The de minimis rule for Form 945 is a single annual test with no prior-year lookback: "If the total tax is $2,500 or more, any amount paid with the return is subject to the 10 percent avoidance penalty" (IRM 20.1.4.6(6))IRM 20.1.4.6(6)Internal Revenue Manual, irs.gov. A payer that guessed it would stay under $2,500 and did not is penalized on the whole amount paid with the return, at 10%, regardless of how late.
- A late return, but deposits were complete. No failure-to-file penalty: "no penalty for filing late is asserted if the taxpayer paid ... 100 percent of the tax required to be paid on or before the due date for payment" (IRM 20.1.2.2.3.1(7))IRM 20.1.2.2.3.1(7)Internal Revenue Manual, irs.gov. And the 60-day minimum failure-to-file penalty that applies to income tax returns "does not apply to employment tax" returns, which includes Form 945 (IRM 20.1.2.3.7.4(3))IRM 20.1.2.3.7.4(3)Internal Revenue Manual, irs.gov. Where FTF does apply it is 5% per month to 25%, reduced by any failure-to-pay penalty for the same month.
- Automatic penalty relief (AEP) and First Time Abate. From July 2026 the IRS applies an Automatic Exemption from Penalty that replaces First Time Abate: a payer that timely filed Form 945 and timely paid for the prior three years is not assessed failure-to-file, failure-to-pay or failure-to-deposit penalties when the return is processed, except a deposit penalty for not depositing by EFT (Instructions for Form 945 (2026)); see automatic penalty relief. For periods AEP does not consider, First Time Abate covers the same three penalties on a clean three-year history (IRM 20.1.1.3.3.2.1)IRM 20.1.1.3.3.2.1Internal Revenue Manual, irs.gov, and is applied before reasonable cause is considered. It is expressly unavailable for "Form 1099 series information returns" (IRM 20.1.1.3.3.2.1(8))IRM 20.1.1.3.3.2.1(8)Internal Revenue Manual, irs.gov, so the 972CG penalty for the same TINs has to be argued on reasonable cause alone.
- Missing or mismatched Form 945-A. A semiweekly depositor whose 945-A is blank, negative or does not add to line 3 gets a CP 207 with 45 days to fix it; unresolved, the IRS assesses an "averaged" penalty that spreads the year's tax evenly across deposit dates, and "Reasonable cause cannot be considered or denied on an averaged FTD penalty assessment" until a valid schedule is supplied (IRM 20.1.4.18, 20.1.4.26.1(2))IRM 20.1.4.18Internal Revenue Manual, irs.govIRM 20.1.4.26.1(2)Internal Revenue Manual, irs.gov.
- Refunding withheld amounts to the payee. Once withheld and deposited, the money belongs to the IRS; the payee claims it on their return. The payer cannot give it back after the fact.
- Skipping withholding because the 945 process is unfamiliar. A payer that should have withheld and did not is liable for the amount it failed to withhold. That is the real cost, and it dwarfs the paperwork.
Three ways a Form 945 fails to post
The unpostable manual (IRM 3.12.279IRM 3.12.279Internal Revenue Manual, irs.gov, rev. Nov. 4, 2025, effective Jan. 1, 2026) shows what stops a Form 945 before it reaches your account, and none of it produces a letter:
- The period is not December. Form 945 is annual and calendar-year only; "any TC addressing MFT 16 with ... input tax period [that] does not end in 12 (YYYY12)" unposts as UPC 490 RC 5 and is researched by hand (IRM 3.12.279.101.4)IRM 3.12.279.101.4Internal Revenue Manual, irs.gov. A 945 coded to a quarter, as some payroll systems do when they treat it like a 941, sits in the unpostable queue while the deposit penalty clock keeps running.
- The credits claimed exceed the deposits posted. A Form 945 that claims more backup-withholding deposits than are on the account (by more than a redacted tolerance) unposts as UPC 305 RC 4. If the missing credits are not found under "parent, subsidiary or associated EINs," the return posts with a Q freeze and a CP 267 computation notice (IRM 3.12.279.27)IRM 3.12.279.27Internal Revenue Manual, irs.gov. The usual cause is a deposit made under a related EIN or under Form 941 instead of 945.
- The entity is not set up for Form 945. An unpostable examiner will not establish a Form 945 filing requirement without coordinating with the entity unit, except where the EIN used is found on the business name files, in which case the account is set up and the return posts (IRM 3.12.279.18.10(2)IRM 3.12.279.18.10(2)Internal Revenue Manual, irs.gov, row d). A first-year 945 filer whose EIN was assigned without the 945 filing requirement can expect a delay of a cycle or two before the return posts. The posting-delay estimator has the ranges.
If you never filed: the compliance check
A payer that filed 1099s with blank payee TINs, or with box 4 withholding, and never filed a Form 945 is selected by a dedicated IRS unit working from Payer Master File data (IRM 4.19.26)IRM 4.19.26Internal Revenue Manual, irs.gov. What follows is Letter 6112, then Letter 6112-A with a Form 945 the examiner prepared, then a substitute return under IRC 6020(b)IRC 6020Internal Revenue Code, Cornell LII.
- Sign and return the prepared Form 945 even when you agree you owe the tax: First Time Abate, which can remove the 25% failure-to-file and the deposit penalties, is available only on a return you filed or signed, never on a 6020(b) return, and the automatic exemption that replaces it is applied when the IRS processes a return you filed.
- Send a liability schedule (line 7 or Form 945-A) with any response; without it every deposit is treated as more than 15 days late and penalized at 10%.
- If an affiliate filed the Form 945 under a different EIN, say so; the manual allows the case to close if that return covers the withholding, otherwise a Form 945-X under the other EIN is required.
Full detail, with subsection citations: the Form 945 non-filer program.
Four account traps the manuals describe
The Form 945 module (MFT 16 on a transcript) is worked by the same Accounts Management and Notice Review units as Form 941, and their manuals describe several ways a correct return and correct deposits still produce a notice.
1. The deposit keyed as a penalty payment. An EFTPS payment made under the wrong payment type posts as TC 690, a designated penalty payment. When no penalty exists on the module the payment shows up on an internal CP 185 transcript with a credit balance and an H- freeze that "is systemically released eight cycles later" (IRM 21.7.11.4.4(1)IRM 21.7.11.4.4(1)Internal Revenue Manual, irs.gov-(2), Oct. 1, 2025).
"Some taxpayers using EFTPS have been inadvertently inputting the payment in a manner that causes it to post as a TC 690 when it was intended to be a TC 650 or TC 660 (payment of tax). By changing TC 690 to TC 650 in a module subject to FTD penalty, this allows the computer to include the payment in its penalty computation, while a TC 690 is disregarded" (IRM 21.7.11.4.4(4) Note)IRM 21.7.11.4.4(4) NoteInternal Revenue Manual, revised Oct. 1, 2025, irs.gov.
Until an assistor recodes the TC 690 to TC 650 by credit transfer, the deposit does not count in the failure-to-deposit computation at all. A phantom deposit penalty on a year whose deposits you can see on your bank statement is worth checking against this note.
2. The misdirected deposit: CP 108 and Form 15108. CP 108 "generates when the type of tax and/or tax period cannot be figured out on an Electronic Federal Tax Payment System (EFTPS) payment"; it says where the credit was posted and encloses Form 15108, Correction to Your Federal Tax Deposit (FTD), to return if the posting is wrong (IRM 21.7.11.4.1(1))IRM 21.7.11.4.1(1)Internal Revenue Manual, revised Oct. 1, 2025, irs.gov. If the module the payment belongs on "has an immediate return due date (within two weeks of return posting)," the credit transfer is suspended "until the return posts and the module settles" (IRM 21.7.11.4.1(2))IRM 21.7.11.4.1(2)Internal Revenue Manual, irs.gov, so a January deposit misdirected just before the January 31 due date is not moved until after the Form 945 posts. If the payment landed on a form you do not file, the assistor transfers it and removes the filing requirement with CC BNCHG; the manual is describing an EFTPS keystroke that created a filing requirement. The rule the assistor works under: "Always make any necessary credit transfers to move any incorrectly posted payments to the correct EIN, tax period, and MFT" (IRM 21.7.11.4.1.1(9))IRM 21.7.11.4.1.1(9)Internal Revenue Manual, irs.gov.
3. More deposits than tax: CP 267, CP 268 and the Q- freeze. "When a module has more credits than claimed by the taxpayer, a Q- freeze is established and a CP 267, No Math Error - Credit Offset Notice, or a CP 268, Math Error Credit Offset Notice, is generated. These notices list up to 39 credits and request that the taxpayer explain if the credits are to be applied to other accounts or refunded" (IRM 21.7.11.4.9(1))IRM 21.7.11.4.9(1)Internal Revenue Manual, revised Jan. 9, 2026, irs.gov. The credit "is frozen from refunding or offsetting for 15 cycles from the posting of the TC 150" (IRM 3.14.2.6.8(1))IRM 3.14.2.6.8(1)Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. The clocks inside the freeze: "If less than three weeks remain before the freeze expires, do not input any credit transfers" (IRM 21.7.11.4.9(5))IRM 21.7.11.4.9(5)Internal Revenue Manual, irs.gov; with three or more weeks left, a requested refund "will be issued in three to four weeks" (IRM 21.7.11.4.9(6))IRM 21.7.11.4.9(6)Internal Revenue Manual, irs.gov; and if you disown the payment and it cannot be placed, "If the credit is less than one year old, prepare Form 2424 ... for the Unidentified Remittance File (URF). If the payment is at least one year old, prepare Form 8758 ... for the Excess Collection File (XSF)" (IRM 21.7.11.4.9(7))IRM 21.7.11.4.9(7)Internal Revenue Manual, irs.gov. Notice Review releases an unclaimed overpayment on its own when it is explained by a credit elect, a transfer or a rolled payment and is exact or within $10.00; amounts under $9.99 release automatically (IRM 3.14.2.6.8(8)IRM 3.14.2.6.8(8)Internal Revenue Manual, irs.gov, (10), Jan. 1, 2026). One more Form 945 particular: "For Form 940, Form 941, Form 943, Form 944, Form 945, Form 720, Form CT-1, and Form 1042 the computer will not offset additional credit elect after the return posting cycle. A manual credit elect transfer must be input" (IRM 3.14.2.6.1.5.1(2))IRM 3.14.2.6.1.5.1(2)Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. The refund box on the return becomes CCC S; the applied box, or neither box, becomes CCC E. A deposit that lands after the return posts will not roll forward by itself.
4. The January deposit trap. "If a TC 650/660 (Doc Code 97) payment dated later than the last day of the tax period is unclaimed and overpays the module, the payment may roll to the next tax period or into the FTD module. (A rolled payment will post on BMFOLT as TC 650/660 for .00)" (IRM 3.14.2.6.7.3(7))IRM 3.14.2.6.7.3(7)Internal Revenue Manual, revised Jan. 1, 2025, irs.gov. For Form 945 that is the January deposit of December backup withholding: dated after December 31, it can roll into the next year and leave the current year short. Notice Review's selection key 37 exists for exactly this case, a balance-due notice on MFT 16 where up to five TC 650 deposits dated after the period end equal the notice amount within $5 (Exhibit 3.14.2-5). Deposit dates on the Form 945-A are liability dates, not payment dates; the deposit itself carries the January date and the IRS has to match it back.
Three more things the manuals say. A Form 945 showing zero tax with deposits posted is not refunded by the computer: if prior years show tax and the payments fit the pattern, the reviewer deletes the refund, sets a -R freeze and prints the notice (IRM 3.14.2.6.7.2(13)IRM 3.14.2.6.7.2(13)Internal Revenue Manual, irs.gov-(14), Jan. 1, 2026). On statutes, "The ASED for employment tax returns (Form 941, Form 943, Form 944, and Form 945) is based on the later of the return due date (April 15 of the succeeding calendar year) or the return received date" (IRM 21.7.9.4.1.1.2(2))IRM 21.7.9.4.1.1.2(2)Internal Revenue Manual, revised Oct. 6, 2025, irs.gov, and returns "filed before April 15 of the succeeding calendar year are 'deemed filed' on April 15" for the refund statute as well (IRM 4.23.13.2.2)IRM 4.23.13.2.2Internal Revenue Manual, revised July 1, 2024, irs.gov; a January 31 filing does not start the clock in January. And on timing, a selected notice can still be stopped or changed inside its Notice Review cycle: "The cycle will load Friday and will close out the second Monday at 2:00 AM" (IRM 3.14.2.1.9(2))IRM 3.14.2.1.9(2)Internal Revenue Manual, revised Jan. 1, 2025, irs.gov; the refund-intercept cutoff is Thursday 4:00 PM Eastern, and for 2026 "Direct deposit refunds will be released one cycle earlier than paper refund checks. Therefore, direct deposit refunds only have a one week interception timeframe" (IRM 3.14.2.7.1(4)IRM 3.14.2.7.1(4)Internal Revenue Manual, irs.gov-(6), Jan. 1, 2026). Replies to a CP notice never go to that unit; "Notice Review does not process replies to Computer Paragraph notices" (IRM 3.14.2.10)IRM 3.14.2.10Internal Revenue Manual, revised Jan. 1, 2024, irs.gov. For what happens when two Forms 945 post for the same year, see the second Form 945 page.
Why line 2 and box 4 have to agree: the payee's credit
The payee claims the amount you withheld as a credit on their own return, and the IRS allows it by matching the claim to the 1099 you filed. The manual's decision table for withholding credits turns on whether the amount "can be verified on CC IRPTR," and a 1099-R or K-1 showing backup withholding is allowed at "taxpayer's figures" (IRM 21.6.3.4.2.2)IRM 21.6.3.4.2.2Internal Revenue Manual, revised July 8, 2025, irs.gov. Withholding that reached the Treasury through your Form 945 deposits but never appeared in box 4 of a filed 1099 is invisible to that match. The reconciliation this page describes, line 2 equal to the box 4 totals under the payees' TINs, is what makes each payee's credit verifiable; the backup withholding guide has the payee side.
Questions people ask
We backup withheld $400 once, all year. Do we still file?
Yes. Any backup withholding requires a Form 945. Under $2,500 for the year you may pay it with the return instead of depositing, but the return is still due.
Does Form 945 go to the states?
No. Some states have their own backup-withholding or nonpayroll withholding returns; most do not require backup withholding at all. Check the state where the payee lives.
Can we file one 945 for several subsidiaries?
Only if they withheld under one EIN. Each EIN that withheld files its own return, matching the 1099s filed under that EIN.
What if we withheld but the payee later gave us a valid TIN?
Stop withholding on the next payment. Amounts already withheld stay deposited and go on the 945 and the payee’s 1099; the payee gets the credit when they file.