42 letters, emails, statements and logs you can preview before you download
Every template opens on its own page as a full-text preview, so you can read it, copy the text, or print it without downloading anything. The Word and Excel files are there when you want them on your letterhead. The B-Notices follow the sample notices in IRS Publication 1281; the reasonable-cause statements and the solicitation letters follow Treas. Reg. 301.6724-1.
No templates match that. Try fewer words, or search the whole site.
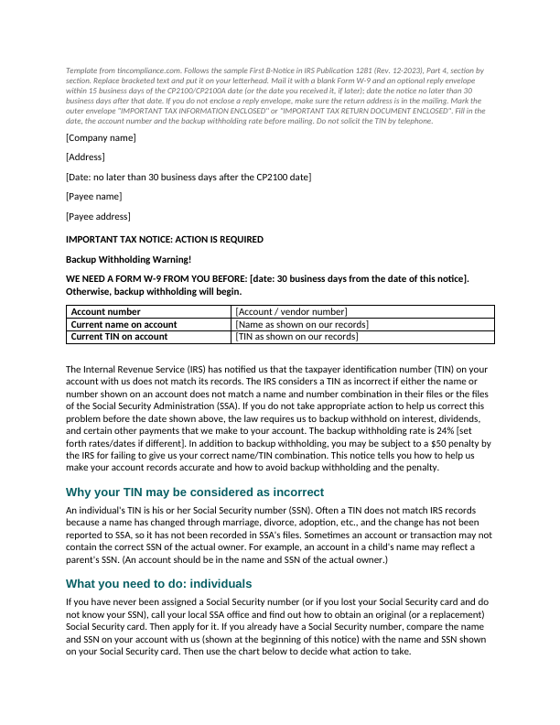
First B-Notice letter
Based on the sample in Pub 1281. Enclose a W-9; mail within 15 business days.
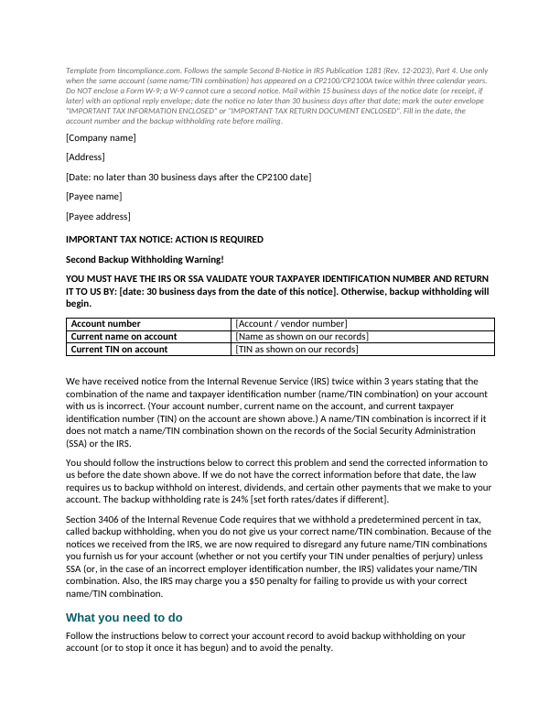
Second B-Notice letter
For the second notice in three years. No W-9; instructs the payee to get an SSA card copy or Letter 147C.
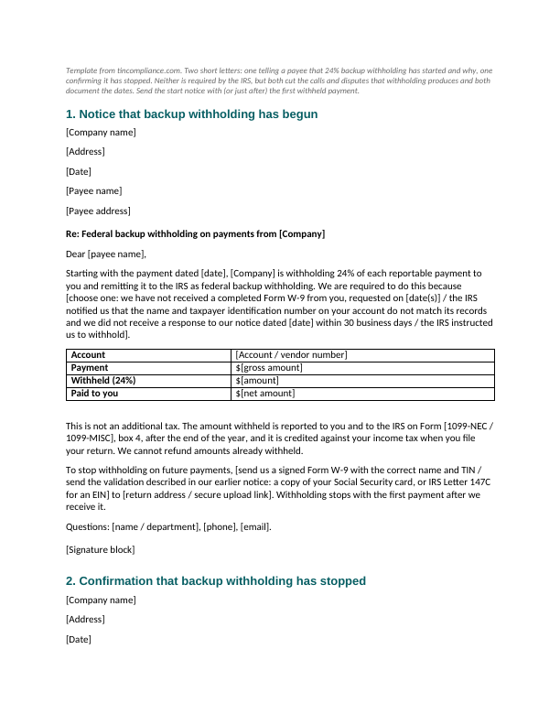
Backup withholding start and stop notices
Two short letters: withholding has begun (and why, with the amounts), and withholding has ended. Cuts the calls and documents the dates.
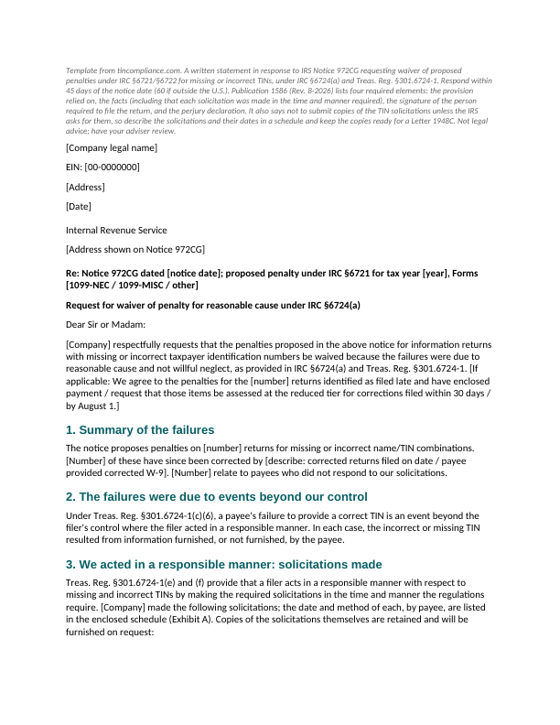
Reasonable-cause statement for Notice 972CG (missing or incorrect TINs)
Structured response under IRC 6724 and Reg. 301.6724-1 with the solicitation exhibits it needs.
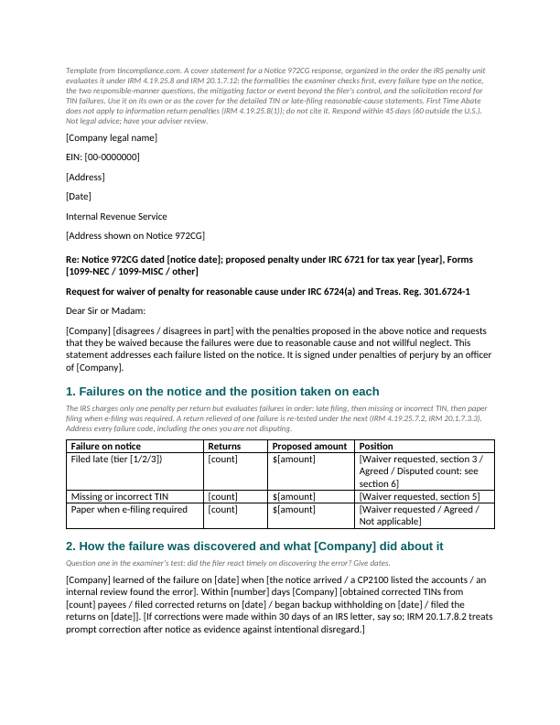
972CG response structured on the examiner's checklist (IRM 4.19.25)
Every failure code on the notice, the two questions the examiner must answer, the mitigating factor with its required evidence, the mail-or-phone solicitation statement, and the officer jurat.
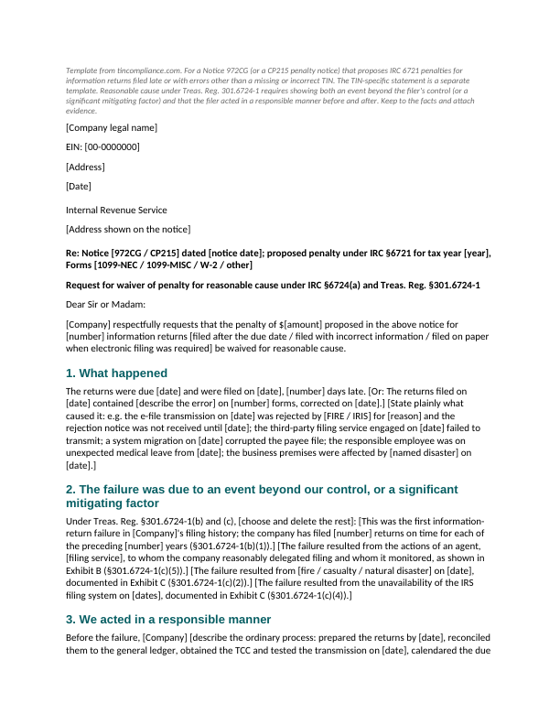
Reasonable-cause statement for late or incorrect filing
For a 972CG or CP215 that penalizes late, paper or erroneous returns rather than TINs: the event, the mitigating factor, and the responsible-manner showing.
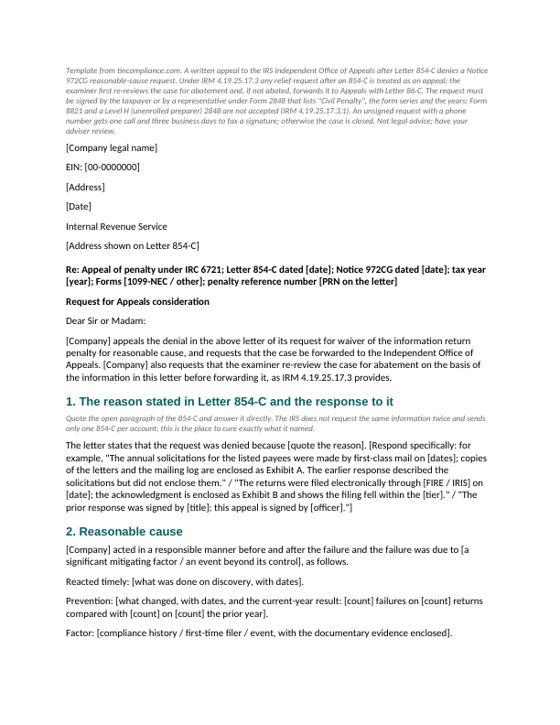
Appeal request after Letter 854-C, with the Form 2848 checklist
Cure the reason the 854-C names, restate the two-prong showing, raise the approval and filer-size points, and get the 2848 right; an 8821 is not accepted.
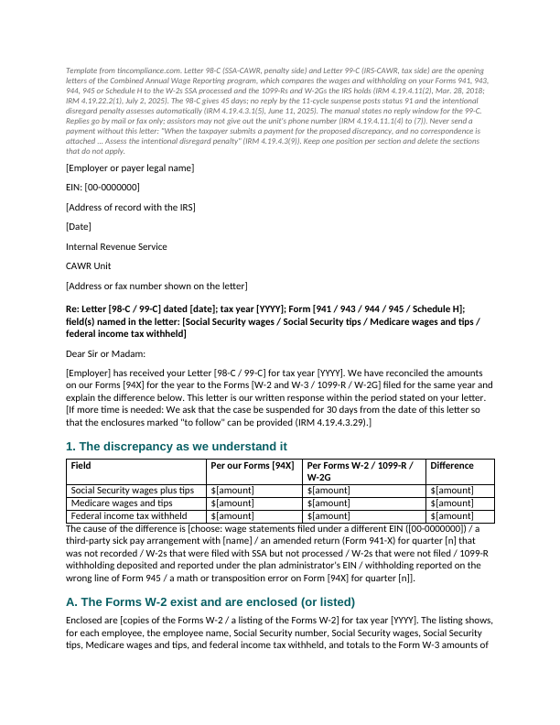
Letter 98-C / 99-C reply
Cover letter for a CAWR reply with the elements examiners look for: W-2 listing fields, W-3 plus non-Copy-A W-2s plus return receipt, signed 941-X, plan administrator EIN, cancelled check front and back.
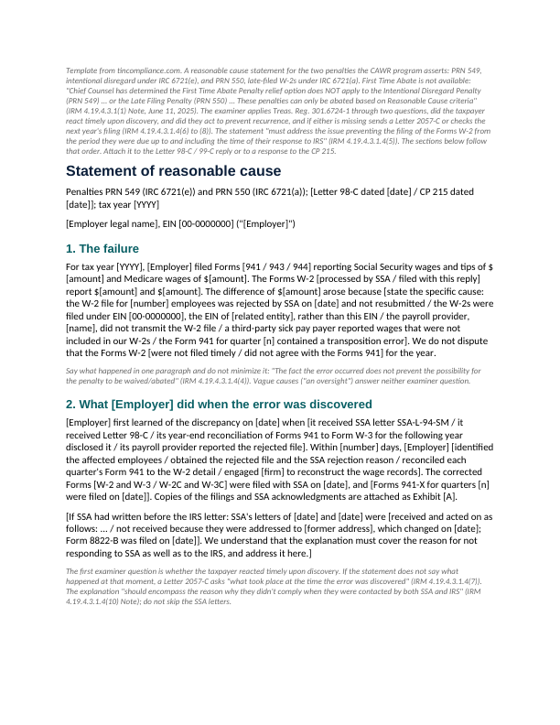
CAWR reasonable-cause statement
Structured on the examiner checklist: what you did when the error was discovered, what you changed so it cannot recur, the reason covering the whole period from due date to reply. Notes that First Time Abate is unavailable.
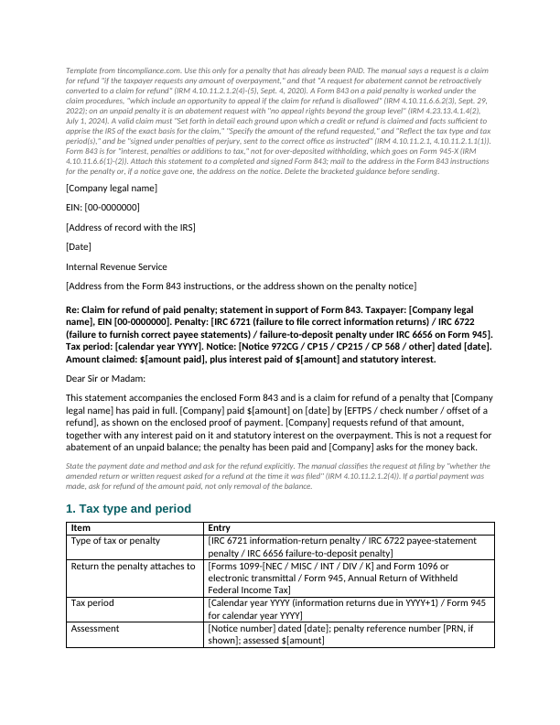
Form 843 penalty refund claim cover statement
Accompanies Form 843 on a paid IRC 6721, 6722 or Form 945 penalty: detailed grounds, amount, tax type and period, the perjury declaration and enclosures, plus an informal-claim letter alternative.
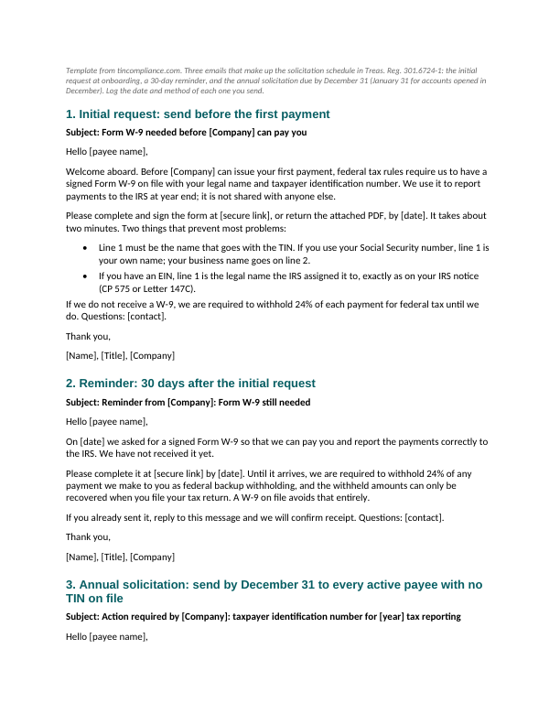
W-9 request emails (initial, reminder, annual)
The three emails that make up the solicitation schedule, with the line-1 guidance that prevents most mismatches.
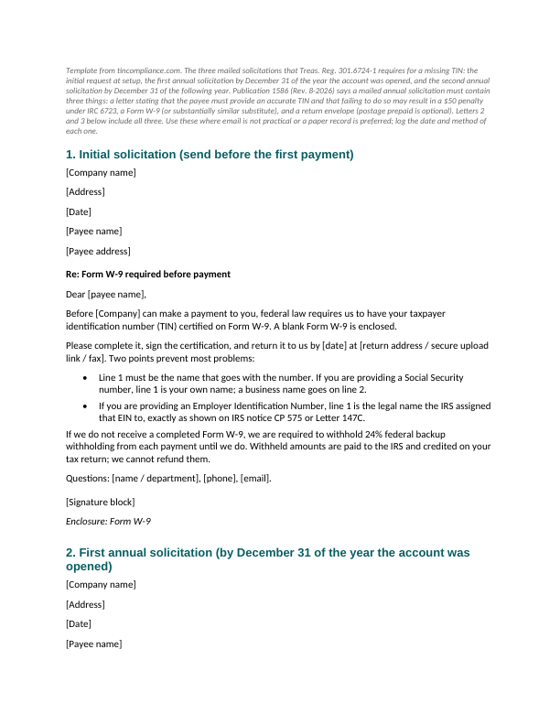
W-9 solicitation letters (initial, first annual, second annual)
The mailed versions of the three solicitations Reg. 301.6724-1 requires for a missing TIN, dated for the penalty-waiver record.
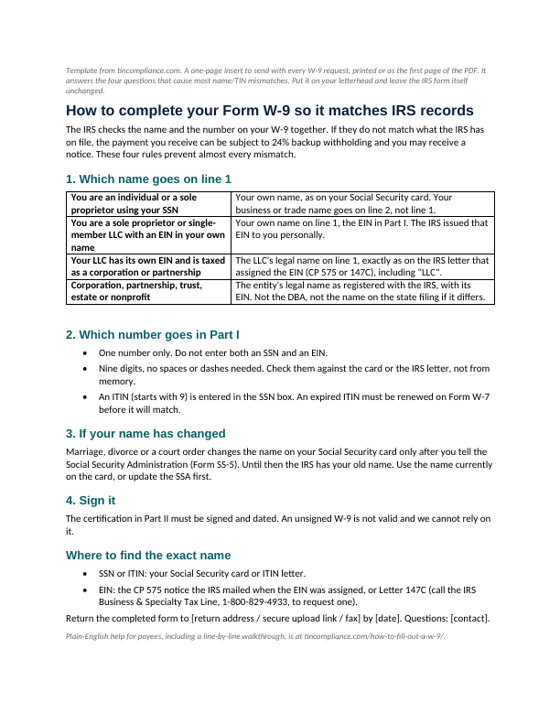
W-9 instructions insert for payees (one page)
Send it with every W-9 request. Which name goes on line 1, which number in Part I, name changes, and the signature.
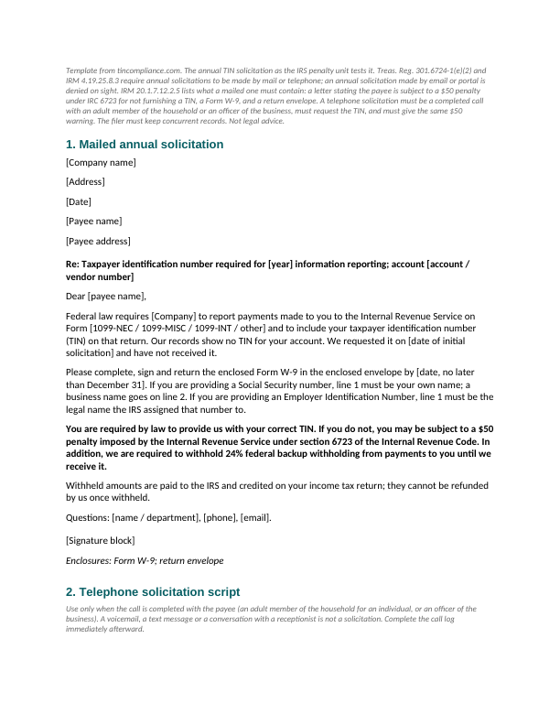
Annual solicitation letter, phone script and call log
The mailed annual solicitation with the three elements the IRS checks, the completed-call script with the $50 warning, and the concurrent call log. Email does not count.
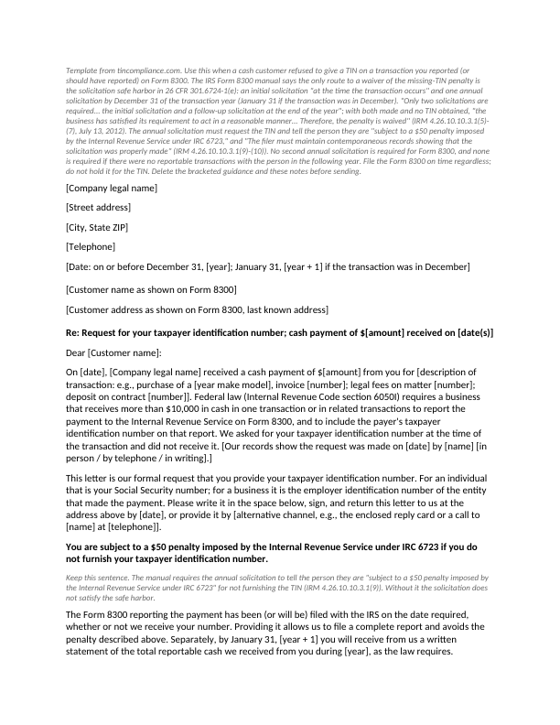
Form 8300 TIN solicitation letter and log
The one annual solicitation the manual requires for a refused TIN, by December 31 (January 31 for December), with the IRC 6723 $50 warning, plus the log that proves both solicitations were made.
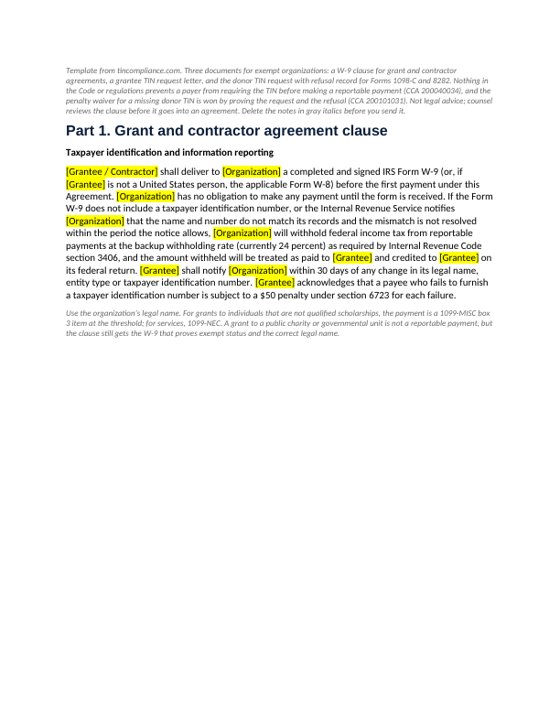
Grant agreement W-9 clause and donor TIN letters
A clause that makes the first grant or contract payment conditional on a Form W-9 (CCA 200040034 says a payer may), the letter that asks a grantee for it, and the donor TIN request for Forms 1098-C and 8282 with the solicitation and refusal record that wins the penalty waiver (CCA 200101031).
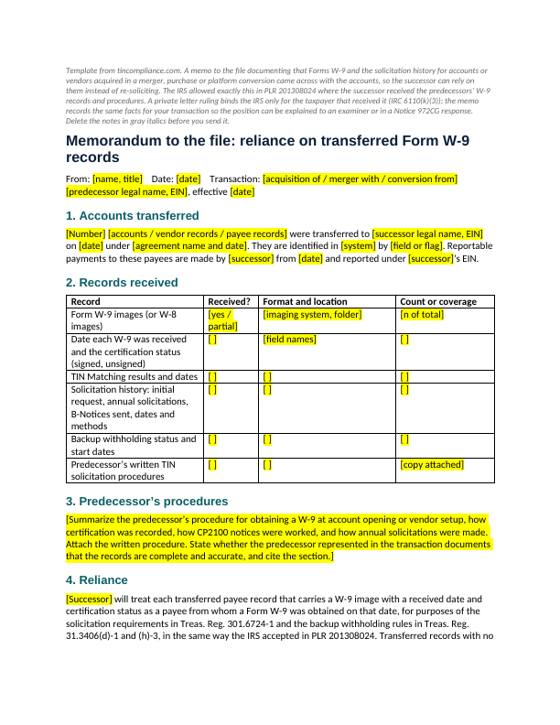
Acquired-account W-9 reliance memo
The memo that records what W-9 records and procedures transferred with acquired accounts or vendors, the predecessor's solicitation practice, the reliance position, and the gap list to re-solicit, so a conversion does not lose the solicitation dates a 972CG response depends on.
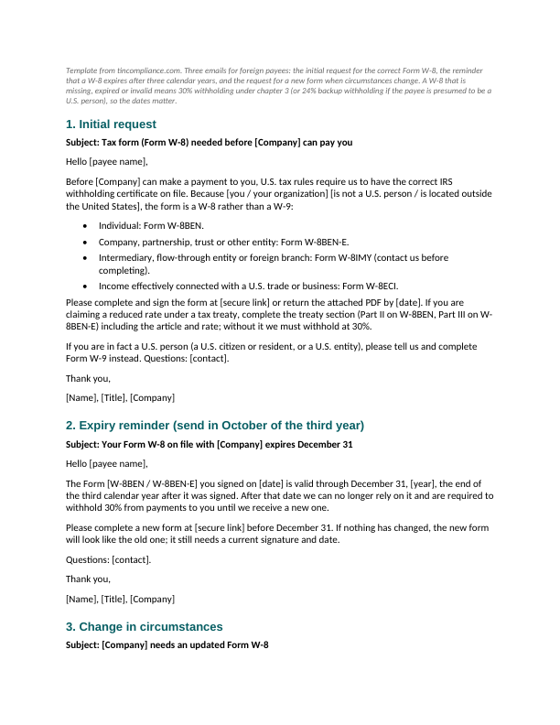
W-8 request, expiry reminder and change-in-circumstances emails
Which W-8 to ask for, the three-calendar-year expiry reminder, and the 30-day change-of-circumstances request.
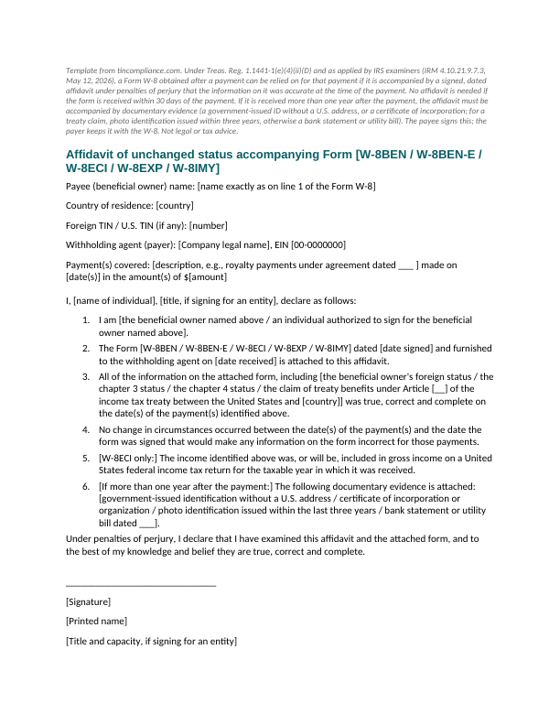
Late W-8 affidavit of unchanged status
For a W-8 that arrives after the payment: the penalties-of-perjury statement that the form was accurate at the time of payment, with the W-8ECI and one-year variants.
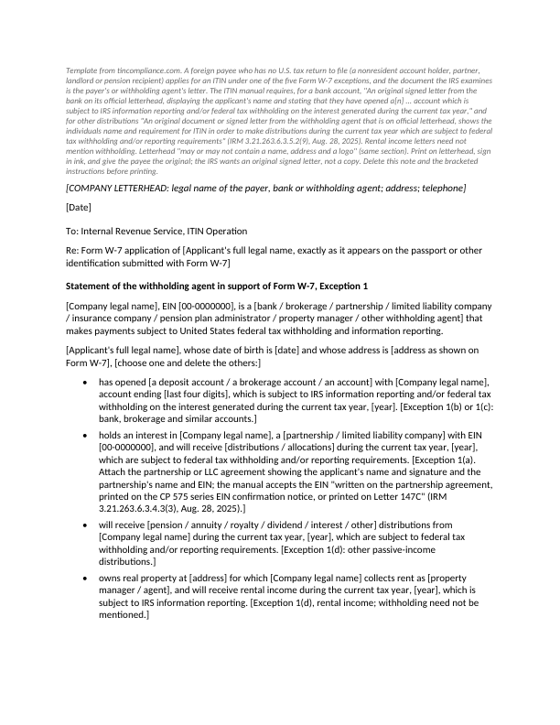
Withholding agent ITIN exception letter
The letterhead letter a payee needs to get an ITIN without a tax return: applicant name, current-year distributions, withholding or reporting requirement. Notes what the IRS rejects (1042-S, 1099 copies, web statements).
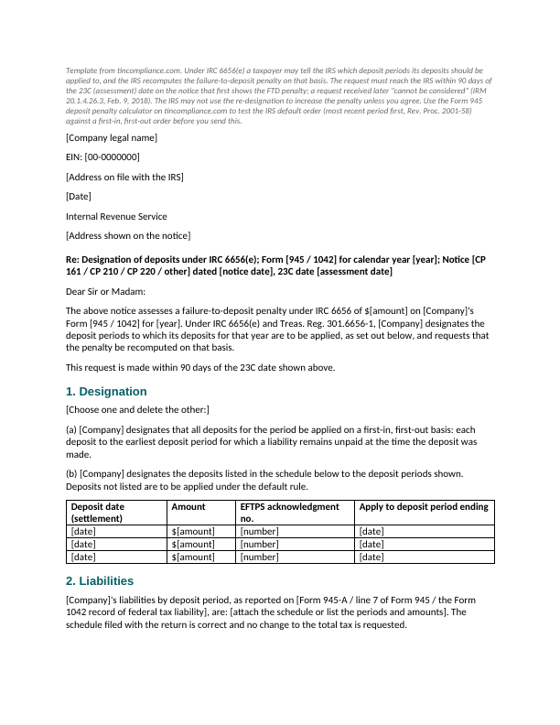
Deposit designation request under IRC 6656(e)
Tells the IRS which deposit periods your deposits apply to so the FTD penalty is recomputed. Must reach the IRS within 90 days of the notice's 23C date.
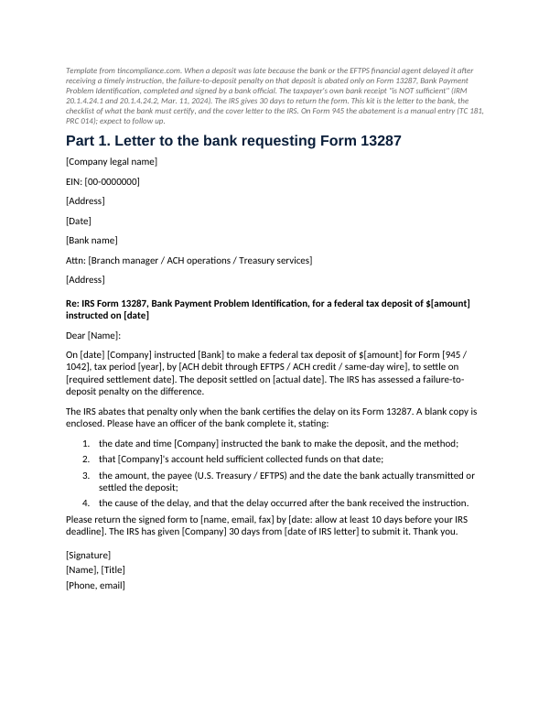
Form 13287 bank-error abatement kit
The bank's certification is the only thing the IRS accepts for a deposit the bank delayed; your receipt is not enough. Letter to the bank, checklist, cover letter to the IRS.
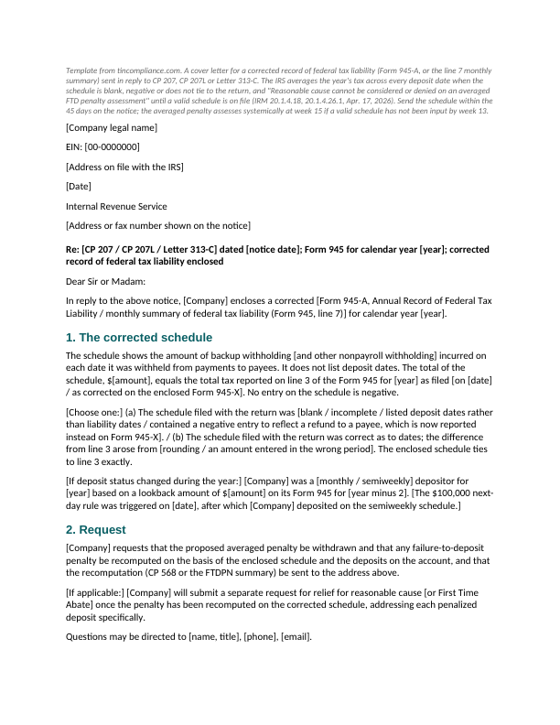
Corrected Form 945-A cover letter (reply to CP 207)
The reply that stops an averaged deposit penalty: a schedule of liability dates that ties to line 3, sent within the 45 days, before any reasonable-cause request.
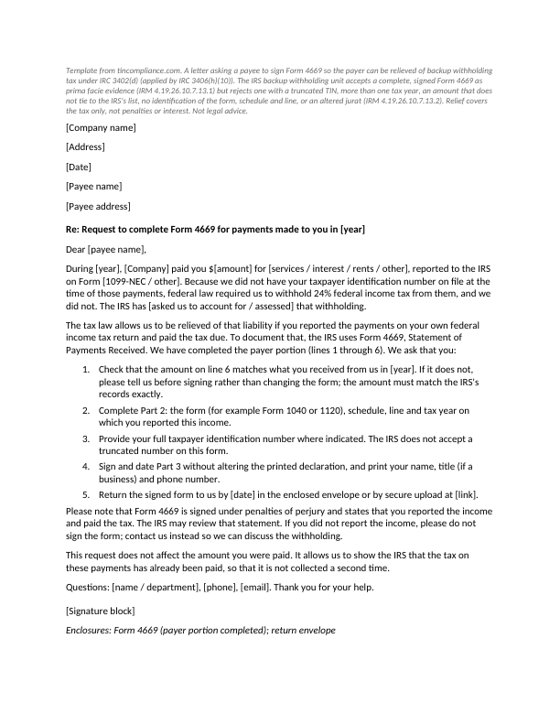
Form 4669 request letter to payees
Asks the payee to confirm the amount, identify the return line, give a full TIN and sign the unaltered jurat; the five things the IRS rejects a 4669 for.
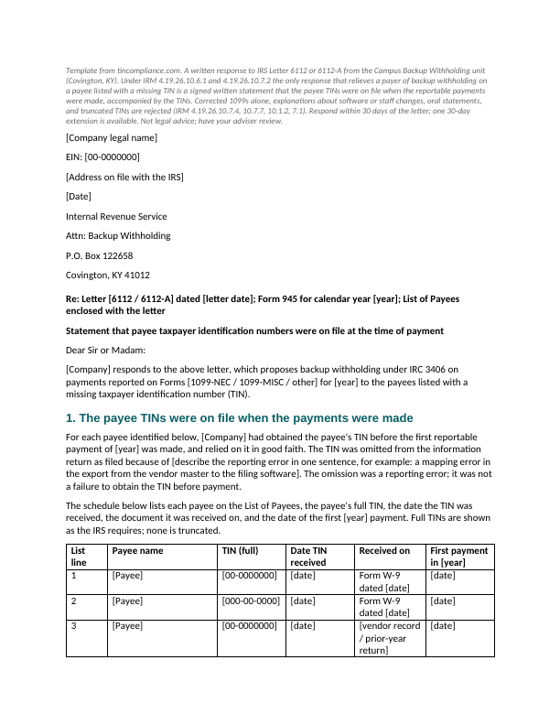
Response to Letter 6112 or 6112-A: TINs were on file at the time of payment
The one response IRM 4.19.26 accepts: a signed statement, payee by payee, that the TIN was on hand before the payment, with full TINs, dated W-9s, and the Form 945 and liability schedule if any withholding is owed.
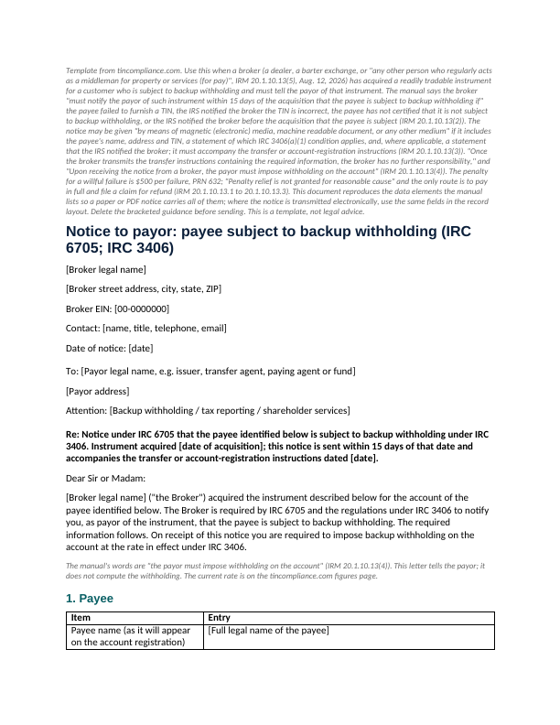
Broker-to-payor backup withholding notice (IRC 6705)
The 15-day notice a broker owes the payor when a payee is subject to backup withholding, with every data element IRM 20.1.10.13 lists, plus a payor acknowledgment. No reasonable-cause defense if skipped.
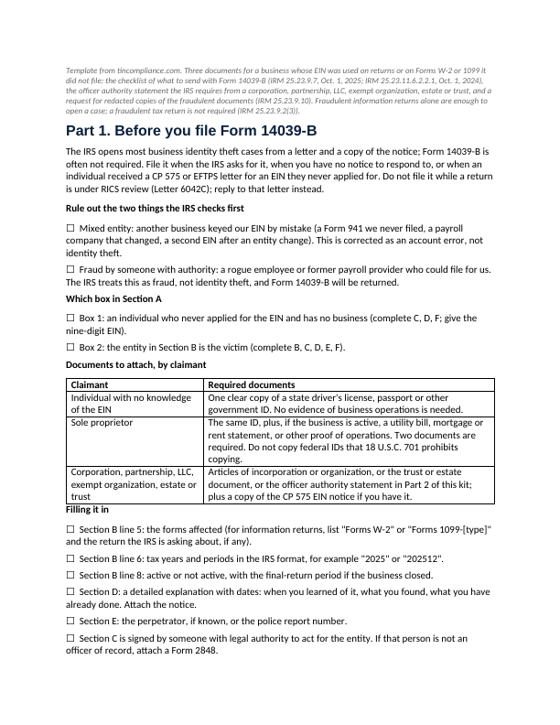
Business identity theft kit: Form 14039-B checklist, officer statement, redacted-copy request
What to attach to Form 14039-B, the letterhead statement the IRS requires from a corporation or LLC, and the letter that gets you redacted copies of what was filed under your EIN.
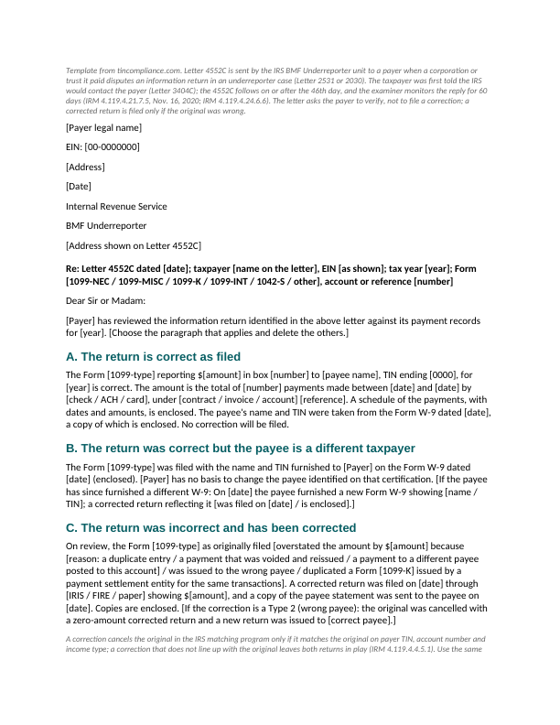
Letter 4552C payer reply (BMF Underreporter)
Four positions for the 1099 the IRS asks you to verify: correct as filed, right per the W-9, corrected, or a nominee payment. Reply within the 60 days the examiner monitors.
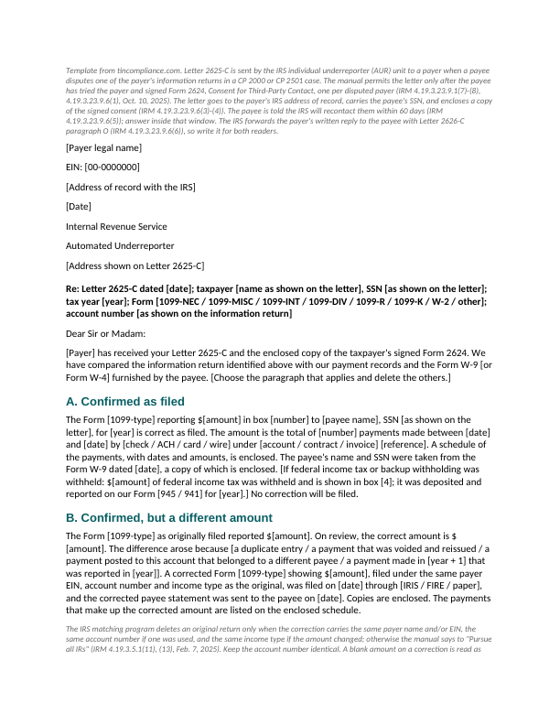
Letter 2625-C payer reply
Four positions for the underreporter unit: confirmed as filed, different amount with a correction, not paid to that SSN, nominee. Written to be read by the payee too, because it will be.
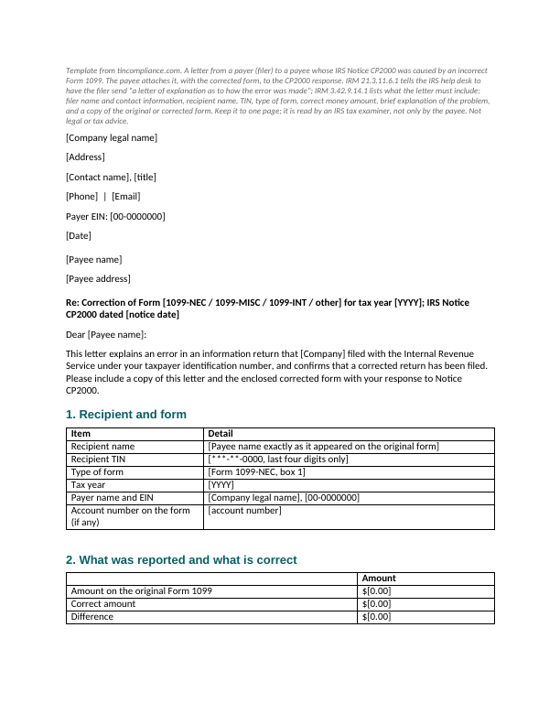
CP2000 letter of explanation to the payee
For the payee to attach to a CP2000 response: the seven elements the IRS requires, for duplicate, overstated and wrong-TIN 1099s.
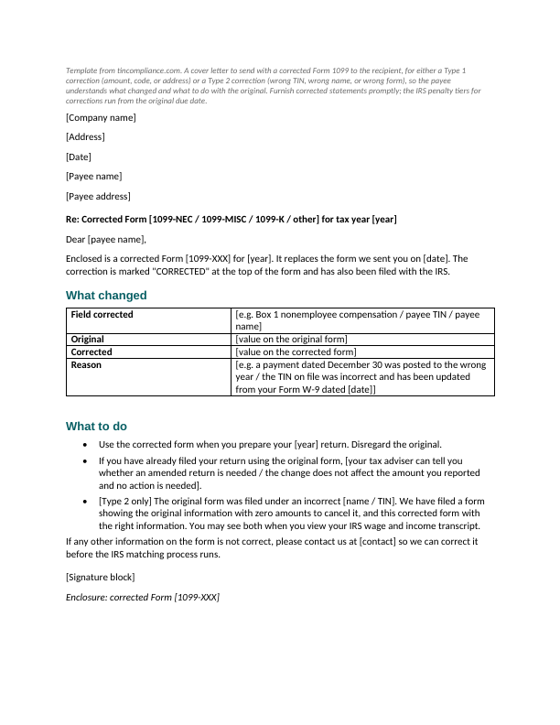
Corrected 1099 cover letter to the payee
What changed, why, and what to do with the original, for Type 1 and Type 2 corrections.
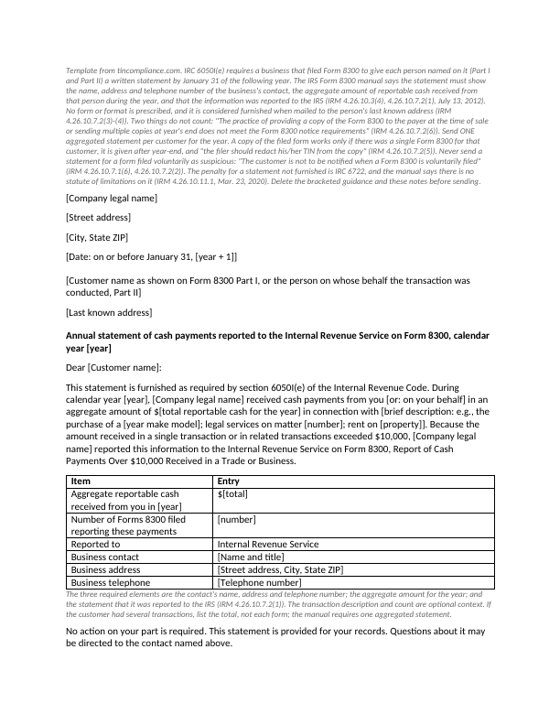
Form 8300 annual customer statement
The January 31 statement with the elements the manual requires: contact name, address and phone, the aggregate reportable cash for the year, and that it was reported to the IRS. One statement per customer.
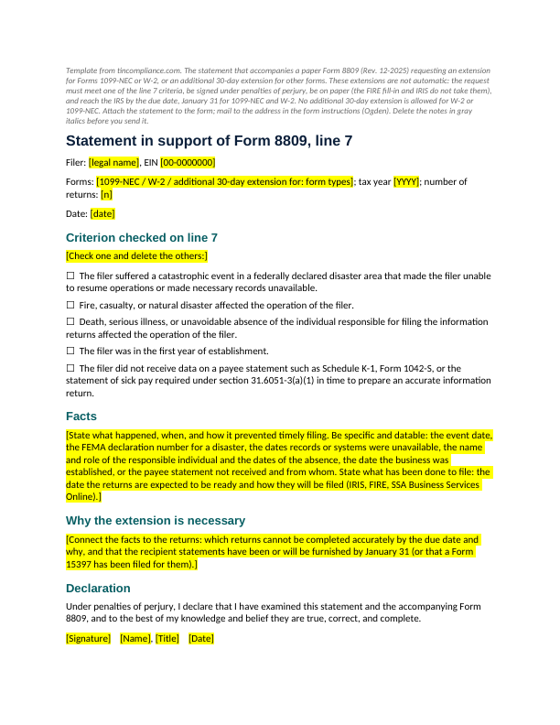
Form 8809 hardship statement for 1099-NEC and W-2
Extensions for 1099-NEC and W-2 are not automatic: the paper Form 8809 must meet one of the line 7 criteria, be signed under penalties of perjury and reach the IRS by January 31. This is the statement that goes with it, criterion by criterion.
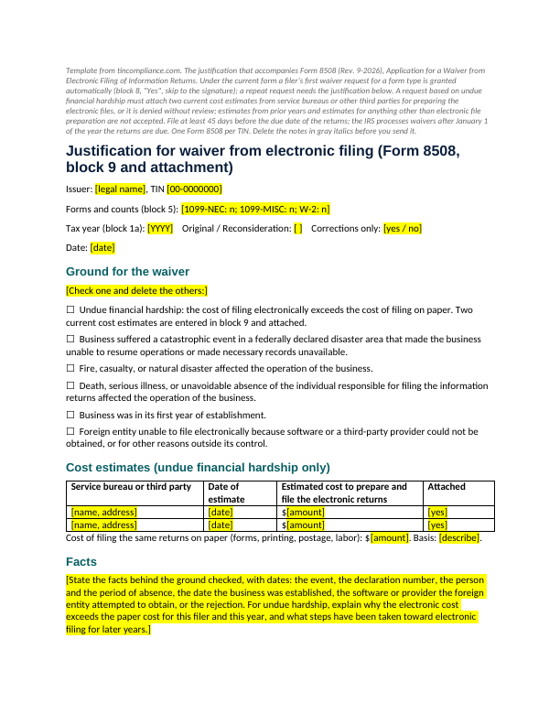
Form 8508 e-file waiver request
A first waiver request is granted automatically under the current Form 8508; a repeat request needs a justification, and an undue-hardship request needs two current third-party cost estimates or it is denied without review. This is the attachment, with the grounds the form lists and the estimate table.
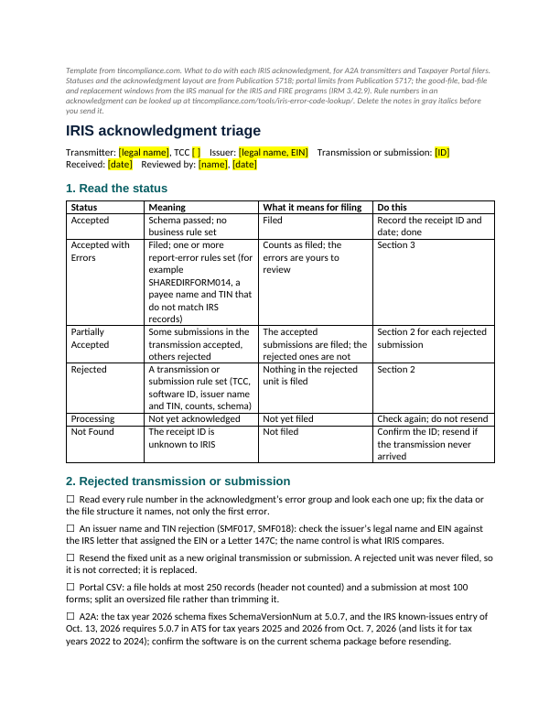
IRIS acknowledgment triage checklist
What to do with each IRIS acknowledgment: a rejected unit is replaced, not corrected; accepted with errors is filed and the errors are data questions; name and TIN errors go to TIN Matching and a W-9 request; and the ten-day window in which a good file can be marked bad and replaced instead of corrected.
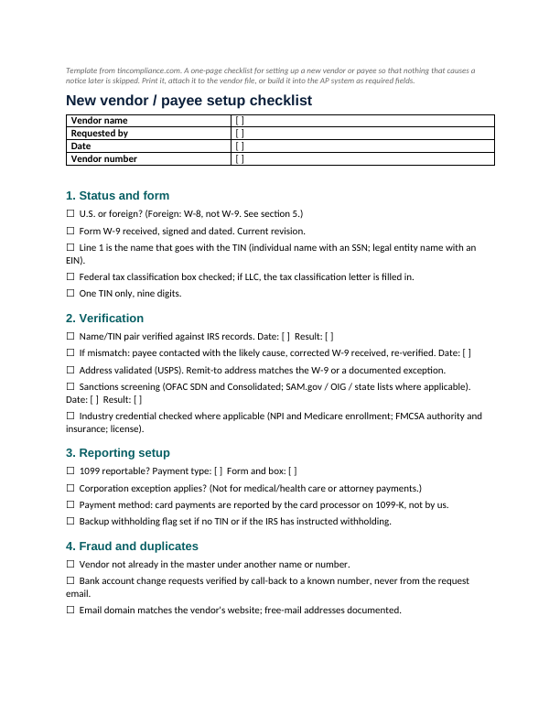
New vendor / payee setup checklist (one page)
Status and form, verification, reporting setup, fraud checks, foreign payees and the file, as tick boxes.
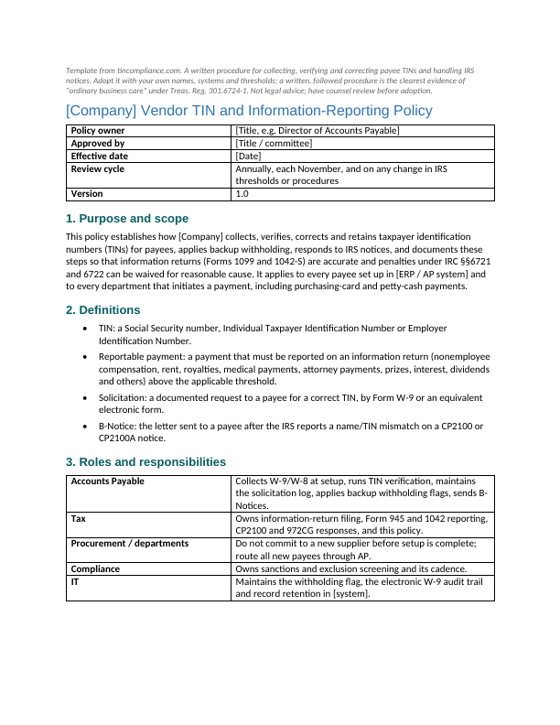
Vendor TIN & information-reporting policy
A written procedure covering scope, onboarding, solicitation schedule, verification, B-Notices, withholding, records and roles. What an auditor or a 972CG response asks for.

TIN solicitation log (Excel)
One row per payee: solicitations, TIN match result, CP2100 and B-Notice dates. Deadlines and status calculate; it is Exhibit A of a reasonable-cause statement.
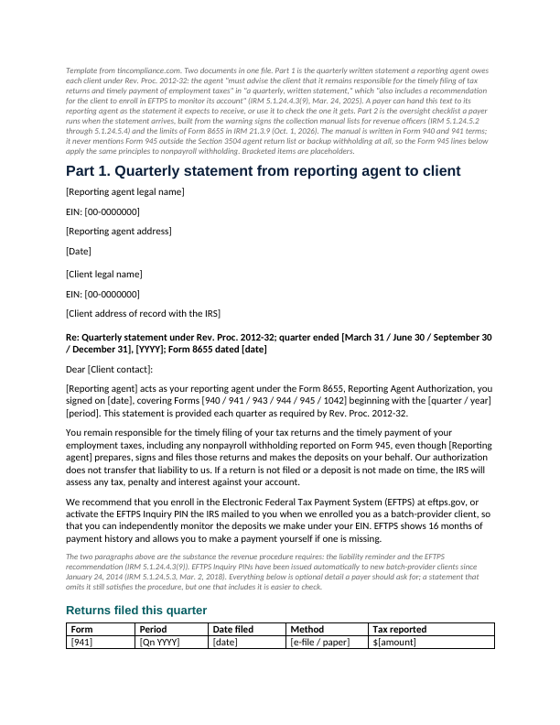
Quarterly provider statement and oversight checklist
The statement your reporting agent must send each quarter under Rev. Proc. 2012-32, and the checks a payer runs alongside it: EFTPS Inquiry PIN, address of record, notice copies, RAF status.
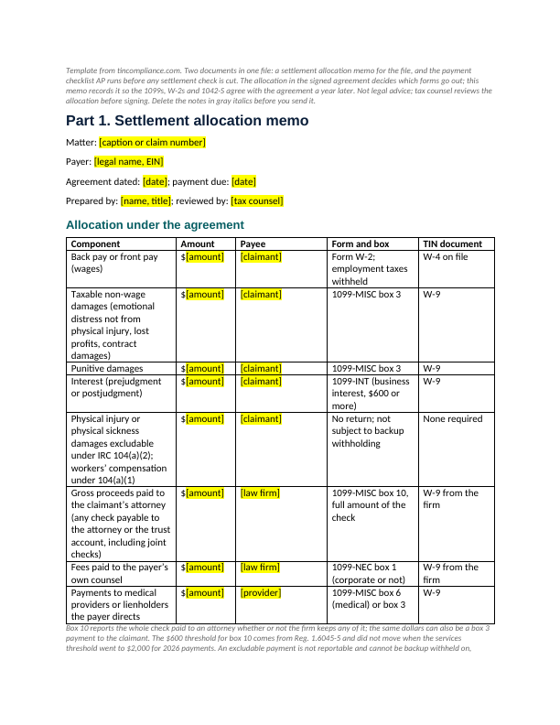
Settlement payment checklist and allocation memo
The allocation memo that records which settlement dollars are wages, taxable damages, excludable damages, attorney proceeds or interest, and the checklist AP runs before the check: W-9s, joint checks, backup withholding, and the excludable payment you cannot hold for a W-9.
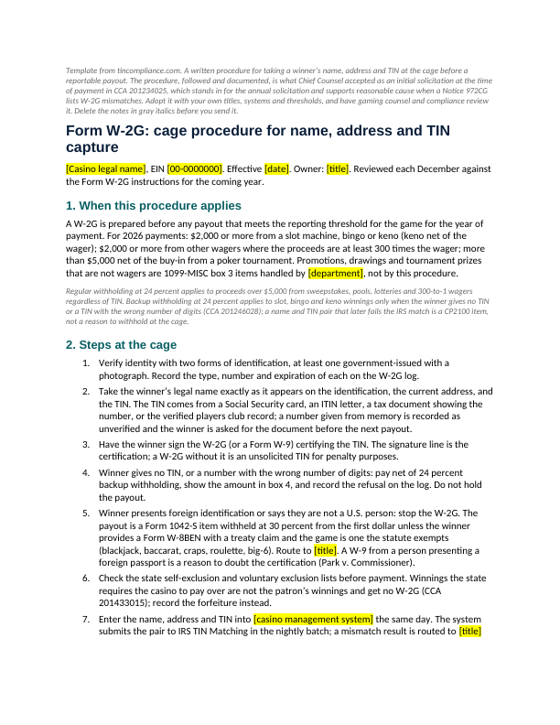
W-2G cage TIN capture procedure
The written procedure a casino, racetrack or sportsbook follows at the cage before a reportable payout, and the log that goes with it; followed and documented, it is the initial solicitation at the time of payment that answered a Notice 972CG in CCA 201234025.
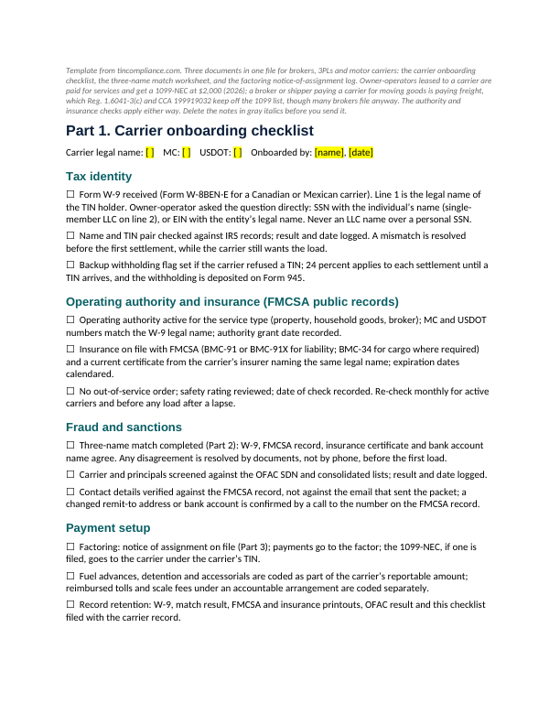
Carrier onboarding packet
The checklist that puts the W-9, the IRS match, the FMCSA authority and insurance checks and the sanctions screen on one record, a worksheet that matches the legal name across the W-9, FMCSA, insurance and bank, and a log for factoring assignments that keeps the carrier as the 1099 payee.
TIN compliance calendar 2026–2027
Every filing and statement due date, Form 945, the solicitation deadlines, the CP2100 and 972CG seasons and W-8 expiry, with your own dates added on the calendar page.
These templates are general-purpose starting points, not legal advice. The IRS sample notices in Publication 1281 are the authoritative wording; the templates track them, but your facts, and your counsel, control what you send.