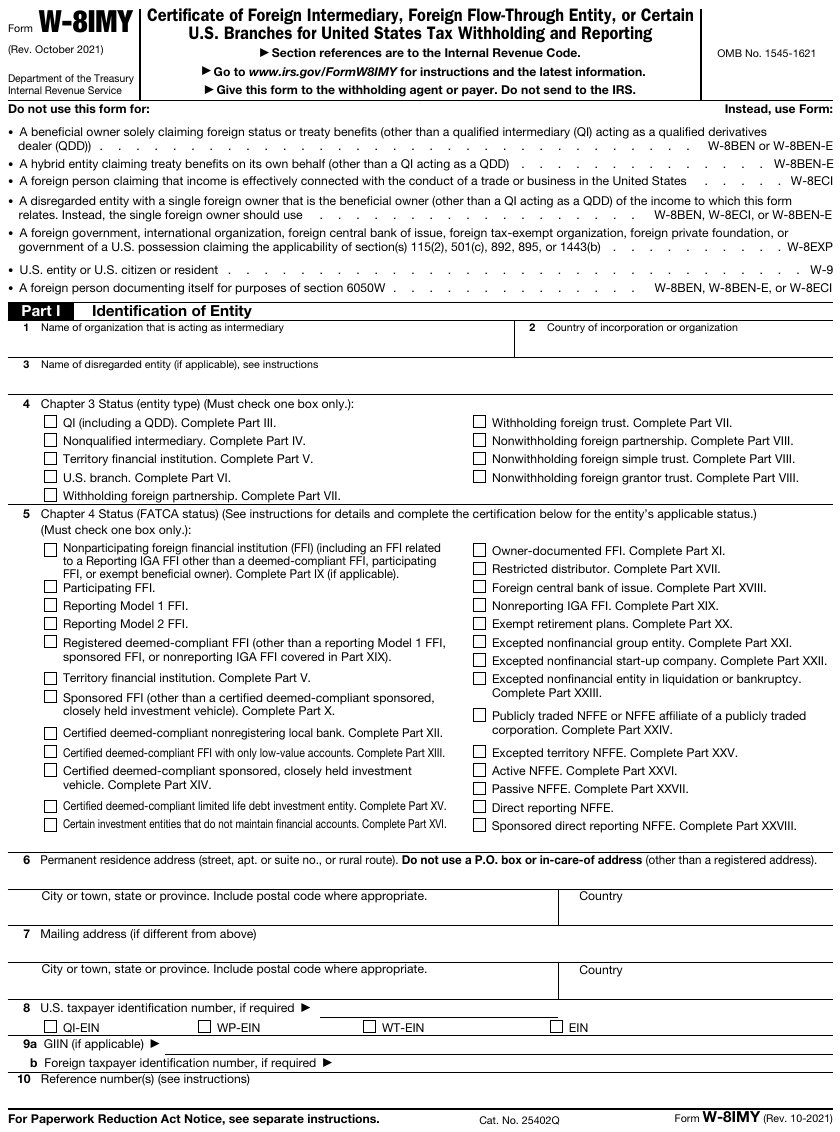
Who completes it and who asks for it
Form W-8IMY is completed by a qualified intermediary (QI, a foreign financial institution with a QI agreement, which may or may not assume primary withholding responsibility), a nonqualified intermediary (NQI), a withholding foreign partnership or trust (which has agreed to withhold on its own partners or beneficiaries), a nonwithholding foreign partnership, simple trust or grantor trust (which passes the documentation of its owners up to the agent), a qualified derivatives dealer, a territory financial institution, and a U.S. branch of a foreign bank or insurance company that is treated as a U.S. person or not. The beneficial owners behind it document themselves on W-8BEN, W-8BEN-E or W-9, and those forms, or a pooled withholding statement, travel with the W-8IMY.
The withholding agent requesting it is the payer of income to an account held in the intermediary's name: an issuer or paying agent, a U.S. broker with a foreign correspondent, a company paying a foreign partnership. When the recipient is a U.S. nonexempt person behind an NQI or flow-through, the agent files a 1099 to that person with "IMY" and the intermediary's name on the second name line; if the recipient cannot be identified, the 1099 goes to "unknown recipient" with the NQI's EIN.
The parts that matter
| Part | What goes there | Where it goes wrong |
|---|---|---|
| I, lines 1 to 5 | Legal name, country, chapter 3 status (the role: QI, NQI, WP, WT, nonwithholding foreign partnership or trust, U.S. branch, QDD, territory FI) and chapter 4 status. | A flow-through partnership checking beneficial owner statuses meant for W-8BEN-E; the wrong role, which changes who withholds. |
| I, lines 6 to 10 | Permanent address, U.S. TIN (a QI-EIN, WP-EIN or WT-EIN is required for those roles), GIIN, reference numbers. | A QI without its QI-EIN; a GIIN missing for a participating FFI. |
| III to VIII. Role certifications | For a QI: whether it assumes primary chapter 3 and 4 withholding and primary Form 1099 reporting and backup withholding. For an NQI or nonwithholding flow-through: that a withholding statement and the underlying payee documentation are provided. For WP/WT: the agreement. | A QI that does not assume primary responsibility but sends no withholding statement; an NQI without the underlying W-8BENs and W-9s. |
| IX to XXVIII. Chapter 4 certifications | The certification matching the chapter 4 status on line 5. | Omitted for withholdable payments. |
| XXIX. Certification | Signed under penalties of perjury by an authorized person; also certifies that the entity will provide a new form within 30 days of a change in circumstances. | Unsigned. |
What the withholding agent relies on
The W-8IMY tells the agent whether it can pay the intermediary gross and let the intermediary withhold (a QI assuming primary responsibility, a WP or WT) or must withhold itself, payee by payee, according to the withholding statement that allocates the payment among the underlying owners and their documentation. The agent reports on Forms 1042-S by recipient (pooled for a QI, by beneficial owner for an NQI) and on Forms 1099 for U.S. nonexempt recipients an NQI or flow-through discloses. A W-8IMY itself is valid indefinitely absent a change in circumstances (three years for a QDD), but the underlying W-8BENs and documentary evidence expire on their own schedules, and the withholding statement must be kept current; an agent may not rely on a statement it knows is stale.
Where these go wrong
- The missing statement. A W-8IMY from an NQI without a withholding statement and payee documentation is not enough to avoid presuming every payment is to an undocumented payee.
- Flow-throughs paid as if beneficial owners. A foreign partnership paid consulting fees for U.S. work is a flow-through; withholding is determined partner by partner, and a W-8BEN-E from the partnership is the wrong form unless it is the beneficial owner under the treaty (a hybrid).
- Two-name-line 1099s. U.S. persons disclosed by an NQI get a 1099 in their own name with "IMY" and the intermediary's name on line 2; dropping the second line, or reporting under the intermediary's name, is a name/TIN mismatch.
Questions people ask about Form W-8IMY
Do we withhold when we receive a W-8IMY?
It depends on the role certified. A QI assuming primary responsibility, a WP or a WT withholds itself; for an NQI or nonwithholding flow-through you withhold payee by payee according to the withholding statement.
How long is it valid?
Indefinitely unless circumstances change (three years for a QDD), but the underlying documentation and the withholding statement have their own validity.
What if we cannot associate a payment with a payee?
Presume an undocumented U.S. nonexempt recipient for the unallocated portion, backup withhold 24%, and file a 1099 to 'unknown recipient' with the NQI or flow-through named on the second line.
The other certification forms
W-9 · W-9S · W-8BEN · W-8BEN-E · W-8ECI · W-8EXP · Comparison table
Sources: Form W-8IMY and instructions (Rev. October 2021); Instructions for the Requester of Forms W-8 (Rev. June 2022); Pub 1099 (2026) part S; Publication 515; Regulations 1.1441-1(e)(3), 1.1441-5.