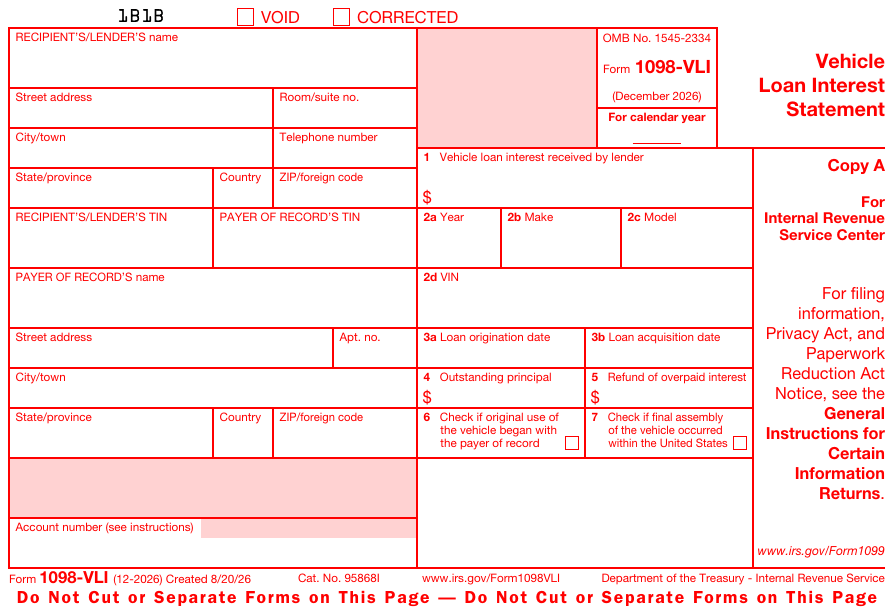
Who must file Form 1098-VLI
File Form 1098-VLI if, in the course of your trade or business, you receive $600 or more of interest during the year on a specified passenger vehicle loan from an individual, a decedent's estate or a nongrantor trust. An SPVL is debt incurred after 2024 to buy an applicable passenger vehicle (a car, minivan, van, SUV, pickup or motorcycle under 14,000 pounds, whose original use begins with the borrower and whose final assembly occurred in the United States) for personal use, secured by a first lien on that vehicle. Amounts customarily financed with the purchase (service plans, GAP, credit insurance, sales tax, title fees) count; negative equity rolled in from a trade-in, cash out, and a trailer or boat do not, and the interest must be allocated. Loans to related parties are excluded; a refinancing keeps SPVL status up to the refinanced balance.
The deduction on the borrower's side (up to $10,000 of interest, phased out above $100,000 of modified AGI, $200,000 joint) is available for tax years 2025 through 2028, so the reporting requirement has a defined life. For 2025 interest, Notice 2025-57 let lenders furnish the information to borrowers by any reasonable method without filing with the IRS; the December 2026 form and instructions are the first full filing, for 2026 interest, due in early 2027.
Threshold: $600, of interest received in the year on each specified passenger vehicle loan (SPVL) from an individual, a decedent's estate or a nongrantor trust; the test is per loan.
What is reported, box by box
| Box | What it reports | Notes |
|---|---|---|
| 1 | Vehicle loan interest received by lender | Interest received during the year on the SPVL portion of the loan. |
| 2a to 2d | Vehicle year, make, model and VIN | The VIN the borrower must put on their return; the substitute vehicle's VIN if the original was replaced after a total loss. |
| 3a | Loan origination date | |
| 3b | Loan acquisition date | If you acquired the loan during the year. |
| 4 | Outstanding principal | As of January 1, or the origination date if later. |
| 5 | Refund of overpaid interest | Reimbursements of a prior year's overpayment. |
| 6 | Original use of the vehicle began with the borrower | Checkbox. |
| 7 | Final assembly of the vehicle occurred in the United States | Checkbox; you may rely on the VIN plant code or the window label. |
Box titles follow the current revision of the form. The IRS reads the payer and recipient name, TIN, address, account number and the money boxes; the state boxes are for the state copy only.
Payments that are not reported on Form 1098-VLI
- Loans on which you received less than $600 of interest for the year (per loan), and interest on the non-SPVL portion of a mixed loan.
- Used vehicles, leases, fleet or business-use vehicles, vehicles assembled outside the United States, and loans to related parties.
- Loans made before 2025, and interest received from a corporation, partnership or other non-individual borrower.
Due dates and extensions
| Copy | Due | For 2026 returns |
|---|---|---|
| To the IRS, paper | February 28 | Monday, March 1, 2027 (February 28 is a Sunday) |
| To the IRS, electronic | March 31 | Wednesday, March 31, 2027 |
| To the recipient | January 31 | Monday, February 1, 2027 (January 31 is a Sunday) |
An automatic 30-day extension is available on Form 8809, filed by the due date on paper or through IRIS; a second 30 days requires a hardship showing. Recipient statements can be extended 30 days on Form 15397, online or by fax only. 10 or more information returns of any type in aggregate must be e-filed (T.D. 9972); IRIS is the only IRS intake system from filing season 2027, FIRE having been retired. A payer who e-files the originals must e-file the corrections.
For 2026 forms filed in 2027: January 31 falls on a Sunday, so that deadline moves to Monday, February 1, 2027; February 28 also falls on a Sunday, so the paper deadline moves to Monday, March 1, 2027. March 31 (electronic) and March 15 are weekdays. February 28 does not become February 29 in a leap year. The compliance calendar has every date with the weekend shifts applied.
Withholding and TIN matching
Interest received on a loan is not a payment to the borrower, so backup withholding does not apply and the form is outside the IRS TIN Matching program. The borrower's TIN is the SSN captured on the credit application, and the return needs it: an incorrect or missing TIN carries the ordinary IRC 6721 penalty. Auto lenders and captive finance companies that have never filed a 1099-series form before are the ones building this from scratch, and the two things to get right are the borrower's legal name as the SSA holds it (not the dealer's DMS record) and the per-loan $600 test.
Name and TIN errors on this form
Every information return is matched by the IRS on the first four characters of the payee's name (the name control) against the TIN. A mismatch produces a CP2100 line the following autumn and, unless the solicitation record is in order, a 972CG penalty the year after: $340 per return for 2026 forms filed in 2027 that are late or wrong, $690 for intentional disregard, with annual maximums of $4,191,500 ($1,397,000 for small filers) under Rev. Proc. 2025-32. The errors that recur on Form 1098-VLI:
- Dealer-originated data. The credit application flows from the dealership's system, where names are often abbreviated or mistyped; the 1098-VLI carries whatever came through. Verify the name/SSN pair when the loan is boarded.
- Co-borrowers. The return goes to the payer of record, the first-named borrower, under that person's SSN.
- Loans sold or serviced. The person receiving the interest files; a servicer files for the loans it collects on, and a purchaser reports from the acquisition date (box 3b).
The name control calculator shows what the IRS will derive from a name line, and the CP2100 guide covers what to do when the notice arrives.
Recipient statements and substitutes
The recipient statement for Form 1098-VLI need not be a copy of the official form: a substitute may be combined with other account statements or reports, provided every required item is numbered and titled as on the official form, the tax year, form number and form name appear together, the recipient instructions are included, and, for the forms Pub 1099 lists, a telephone number with direct access to someone who can answer questions is shown. Publication 1179 (Rev. Proc. 2026-18) has the specifications; logos, slogans and advertising are not permitted on the statement itself. Statements may be furnished electronically only to a recipient who has affirmatively consented in a way that shows they can access the format, after the disclosures in Pub 1099 part M, and must stay posted through October 15. Copy B may show a truncated TIN (xxx-xx-1234); the IRS copy never may.
Corrections and state copies
A wrong amount, code or checkbox is a Type 1 correction: one corrected return with the CORRECTED box checked. A wrong or missing payee TIN, a wrong payee name, or the wrong form type is a Type 2 correction: a zeroed-out copy of the original plus a new original, in that order. Publication 1099 also says you are not required to file a correction for a missing or incorrect TIN if you meet the reasonable-cause standard, only to use the right TIN on the next return, although the IRS encourages the correction. Details and the paper error charts are on the 1099 corrections page.
Form 1098-VLI is not in the Combined Federal/State Filing program, so any state that requires it must receive it directly. Requirements by state are on the state pages.
Questions people ask about Form 1098-VLI
Did we have to file for 2025?
No. Notice 2025-57 provided transition relief: lenders could furnish the interest, VIN and vehicle information to borrowers by any reasonable method and were not required to file with the IRS. The 2026 forms filed in 2027 are the first mandatory filing.
Does a used-car loan qualify?
No. Original use must begin with the borrower, and final assembly must be in the United States.
What if the loan included a trailer or negative equity?
Only the SPVL portion is reported; allocate principal and interest between the qualifying and non-qualifying parts.
Is 1098-VLI in the Combined Federal/State program?
No.
Other federal forms
1042-S · 1097-BTC · 1098 · 1098-C · 1098-E · 1098-F · 1098-Q · 1098-T · 1099-A · 1099-B · 1099-C · 1099-CAP · 1099-DIV · 1099-G · 1099-INT · 1099-K · 1099-LS · 1099-LTC · 1099-MISC · 1099-NEC · 1099-OID · 1099-PATR · 1099-Q · 1099-QA · 1099-R · 1099-S · 1099-SA · 1099-SB · 3921 · 3922 · 5498 · 5498-ESA · 5498-SA · W-2G · 1099-DA · Comparison table
Sources: IRS Publication 1099 (2026), General Instructions for Certain Information Returns, which replaced the separate General Instructions starting with tax year 2026; Instructions for Form 1098-VLI (December 2026); Pub 1099 (2026) What's New; Notice 2025-57; IRC 6050AA, 163(h)(4); Regulations 1.163-16. Threshold amounts are indexed for inflation from calendar year 2027; check IRS.gov/InflationAdjustment for the current year.