TIN ComplianceA resource from TIN Comply
Foreign payees

Paying someone outside the United States

Chapter 3 withholding, FATCA, treaty rates for 65 countries, the W-8 series and Form 1042-S, in one place. For AP, tax and treasury teams that pay foreign contractors, licensors, lenders and shareholders.

Updated November 18, 2026Reading time 9 minutesSources IRC 1441 to 1474; Publication 515 (2026); Instructions for Form 1042-S (2026); IRS Tax Treaty Tables

Start here

A foreign contractor working abroad

The most common case. Collect a W-8BEN or W-8BEN-E, withhold nothing, file nothing.

Royalties, interest or dividends

U.S.-source and withheld on at 30% unless a treaty or the Code reduces it.

Someone working in the United States

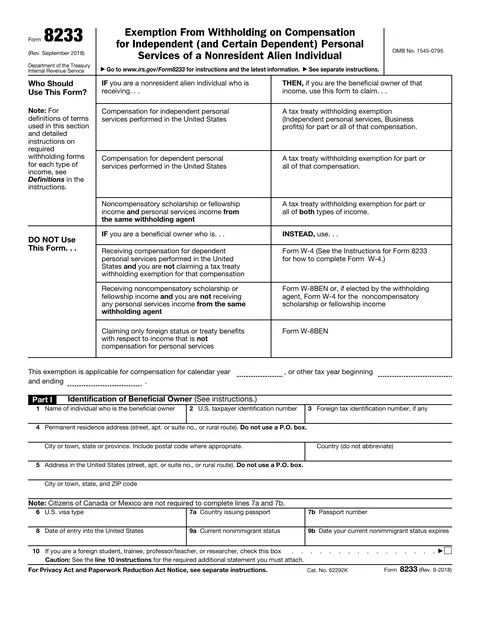
Pay for U.S. services is U.S.-source. A treaty exemption for an individual is claimed on Form 8233.

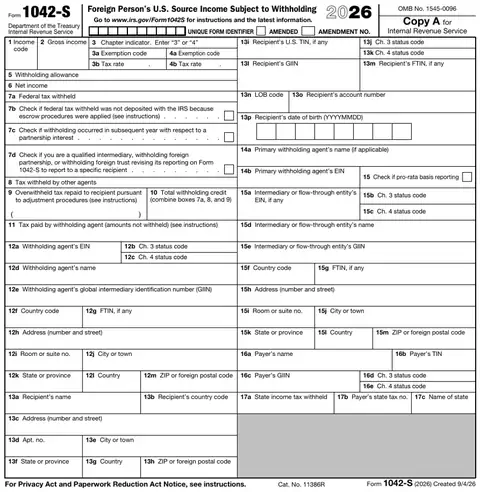
Year end: Forms 1042-S and 1042

Due March 15, e-filed through IRIS for 2026 forms, with a code for every box.

Treaty rates by country

Select a country for its page: interest, dividend, royalty and pension rates with the article and the IRS conditions, and the exemptions for pay for services performed in the United States. Countries left uncolored have no income tax treaty with the United States, so U.S.-source income paid there is withheld at 30% unless the Code exempts it.

Zimbabwe: no income tax treatyZambia: no income tax treatyYemen: no income tax treatyVietnam: Signed, not in forceVenezuela: Treaty in forceUzbekistan: 1973 U.S.S.R. treatyUruguay: No treaty (information exchange only)United States: United StatesUnited States: United StatesS. Geo. and the Is.: no income tax treatyFalkland Is.: no income tax treatyUnited Kingdom: Treaty in forceUnited Arab Emirates: no income tax treatyUkraine: Treaty in forceUganda: no income tax treatyTurkmenistan: 1973 U.S.S.R. treatyTurkey: Treaty in forceTunisia: Treaty in forceTrinidad and Tobago: Treaty in forceTogo: no income tax treatyTimor-Leste: no income tax treatyThailand: Treaty in forceTanzania: no income tax treatyTajikistan: 1973 U.S.S.R. treatyTaiwan: no income tax treatySyria: no income tax treatySwitzerland: Treaty in forceSweden: Treaty in forceeSwatini: no income tax treatySuriname: no income tax treatyS. Sudan: no income tax treatySudan: no income tax treatySri Lanka: Treaty in forceSpain: Treaty in forceSouth Korea: Treaty in forceSouth Africa: Treaty in forceSomalia: no income tax treatySomaliland: no income tax treatySlovak Republic: Treaty in forceSlovenia: Treaty in forceSierra Leone: no income tax treatySerbia: no income tax treatySenegal: no income tax treatySaudi Arabia: No treaty (information exchange only)Rwanda: no income tax treatyRussia: Treaty suspendedRomania: Treaty in forceQatar: no income tax treatyPortugal: Treaty in forcePoland: Treaty in forcePhilippines: Treaty in forcePeru: no income tax treatyParaguay: no income tax treatyPapua New Guinea: no income tax treatyPanama: No treaty (information exchange only)Pakistan: Treaty in forceOman: no income tax treatyNorway: Treaty in forceNorth Korea: no income tax treatyNigeria: no income tax treatyNiger: no income tax treatyNicaragua: no income tax treatyNew Zealand: Treaty in forceNetherlands: Treaty in forceNepal: no income tax treatyNamibia: no income tax treatyMozambique: no income tax treatyMorocco: Treaty in forceW. Sahara: no income tax treatyMontenegro: no income tax treatyMongolia: no income tax treatyMoldova: 1973 U.S.S.R. treatyMexico: Treaty in forceMauritania: no income tax treatyMali: no income tax treatyMalaysia: no income tax treatyMalawi: no income tax treatyMadagascar: no income tax treatyNorth Macedonia: no income tax treatyLithuania: Treaty in forceLibya: no income tax treatyLiberia: no income tax treatyLesotho: no income tax treatyLebanon: no income tax treatyLatvia: Treaty in forceLaos: no income tax treatyKyrgyzstan: 1973 U.S.S.R. treatyKuwait: no income tax treatyKosovo: no income tax treatyKenya: no income tax treatyKazakhstan: Treaty in forceJordan: no income tax treatyJapan: Treaty in forceJamaica: Treaty in forceItaly: Treaty in forceIsrael: Treaty in forcePalestine: no income tax treatyIreland: Treaty in forceIraq: no income tax treatyIran: no income tax treatyIndonesia: Treaty in forceIndia: Treaty in forceIceland: Treaty in forceHungary: Treaty terminatedHonduras: no income tax treatyHaiti: no income tax treatyGuyana: no income tax treatyGuinea-Bissau: no income tax treatyGuinea: no income tax treatyGuatemala: no income tax treatyGreece: Treaty in forceGhana: no income tax treatyGermany: Treaty in forceGeorgia: 1973 U.S.S.R. treatyGambia: no income tax treatyGabon: no income tax treatyFrance: Treaty in forceNew Caledonia: no income tax treatyFr. S. Antarctic Lands: no income tax treatyFinland: Treaty in forceFiji: no income tax treatyEthiopia: no income tax treatyEstonia: Treaty in forceEritrea: no income tax treatyEq. Guinea: no income tax treatyEl Salvador: no income tax treatyEgypt: Treaty in forceEcuador: No treaty (information exchange only)Dominican Rep.: no income tax treatyDjibouti: no income tax treatyGreenland: no income tax treatyDenmark: Treaty in forceCzech Republic: Treaty in forceN. Cyprus: no income tax treatyCyprus: Treaty in forceCuba: no income tax treatyCroatia: Signed, not in forceCôte d'Ivoire: no income tax treatyCosta Rica: No treaty (information exchange only)Dem. Rep. Congo: no income tax treatyCongo: no income tax treatyColombia: no income tax treatyChina: Treaty in forceChile: Treaty in forceChad: no income tax treatyCentral African Rep.: no income tax treatyCanada: Treaty in forceCameroon: no income tax treatyCambodia: no income tax treatyMyanmar: no income tax treatyBurundi: no income tax treatyBurkina Faso: no income tax treatyBulgaria: Treaty in forceBrazil: no income tax treatyBotswana: no income tax treatyBosnia and Herz.: no income tax treatyBolivia: no income tax treatyBhutan: no income tax treatyBenin: no income tax treatyBelize: no income tax treatyBelgium: Treaty in forceBelarus: 1973 U.S.S.R. treatyBangladesh: Treaty in forceAzerbaijan: 1973 U.S.S.R. treatyAustria: Treaty in forceAustralia: Treaty in forceArmenia: 1973 U.S.S.R. treatyArgentina: No treaty (information exchange only)Angola: no income tax treatyAlgeria: no income tax treatyAlbania: no income tax treatyAfghanistan: no income tax treatyCayman Islands: No treaty (information exchange only)Jersey: No treaty (information exchange only)Guernsey: No treaty (information exchange only)Isle of Man: No treaty (information exchange only)Trinidad and Tobago: Treaty in forceSingapore: No treaty (information exchange only)Malta: Treaty in forceLuxembourg: Treaty in forceJamaica: Treaty in forceCyprus: Treaty in forceHong Kong: No treaty (information exchange only)Barbados: Treaty in force
Treaty in force1973 U.S.S.R. treatySigned, not in forceTerminated or suspendedInformation exchange onlyNo treaty
Select a country for its rates and articles. Dots mark jurisdictions too small to show at this scale.

Guides

Foreign payees and screening

Chapter 3 withholding for payers who are not banks: who is foreign, what is U.S.-source, and what to withhold

The three questions behind every payment to a foreign person, the source rules, the 30% rate and its exceptions, the presumption rules, deposits, and Forms 1042-S and 1042.

Foreign payees and screening

Accepting a tax treaty claim: what the payer checks before applying a reduced rate

Residence, beneficial ownership, limitation on benefits, the TIN requirement, reason to know, how long a claim lasts, and what happens to the payer when the claim was wrong.

Foreign payees and screening

FATCA (chapter 4) for ordinary payers: when it applies to a vendor or licensor, and when it does not

Withholdable payments and the excluded nonfinancial payments, active and passive NFFEs, substantial U.S. owners, GIIN checks, and how chapter 4 and chapter 3 meet on Form 1042-S.

Foreign payees and screening

Foreign vendors: W-8 instead of W-9, and what Form 1042-S means

How to tell a foreign payee from a U.S. one, which W-8 to collect, 30% chapter 3 withholding and treaty claims, and why a foreign vendor on a CP2100 is a filing error.

Foreign payees and screeningIRM

How the IRS examines a payer's foreign vendors: W-8s, presumption rules and the Form 1042 clock

The three-step vendor-file sweep, the W-8 checklist and U.S. indicia, the 24% or 30% presumption fork, the late-W-8 cure at 30 days and one year, validity periods, and the Form 1042 deposit schedule.

Foreign payees and screeningIRM

What happens to a paper Form 1042-S inside the IRS: Ogden's Code and Edit rules

Only Copy A counts, a 1042-T without Copy A is destroyed with no letter, recipient TINs equal to your EIN or repeating digits are deleted unresearched, two income codes become one, new 2026 codes.

Foreign payees and screening

FIRPTA withholding: Forms 8288, 8288-A and 8288-B

The buyer as withholding agent: the 15%, 10% and zero rates, the W-9 that ends withholding, the 20-day filing, stamped Copy B, missing seller TINs, and the withholding certificate as Ogden processes it.

Foreign payees and screening

Why the IRS rejected your e-filed Form 1042: every F1042 business rule in plain English

The 16 Form 1042 MeF business rules translated into the lines they test (62, 63, 64, Section 2, the monthly totals) with the fix for each, plus the general MeF rules that catch first-time and foreign filers: EFIN, name control, duplicates, test EINs.

Foreign payees and screening

Getting an EFIN to e-file Form 1042: the ITIN, SSN and foreign EFIN routes

Who must e-file Form 1042, and the three IRS tutorials for getting an EFIN: a responsible official with an ITIN (Large Taxpayer option), one with an SSN, or a foreign EFIN held by a U.S. provider in your business-related group.

Tools
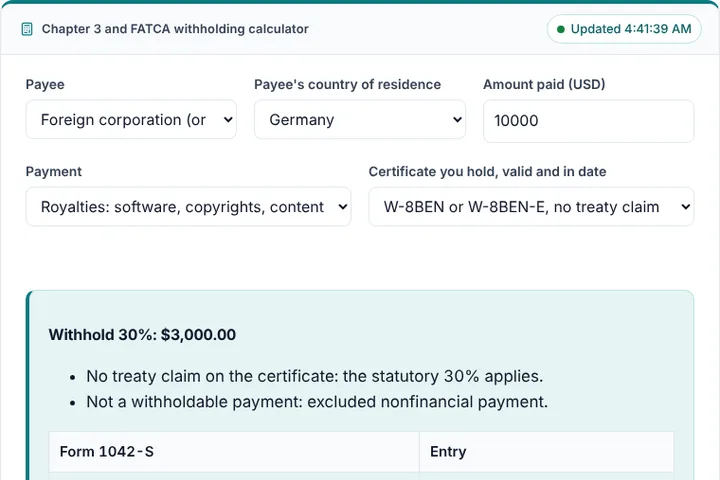
Chapter 3 and FATCA withholding calculator filled in with a sample result
Calculator

Chapter 3 and FATCA withholding calculator

One payment to a foreign person: source, the chapter 3 rate and tax, whether FATCA chapter 4 withholding applies, and every Form 1042-S code.
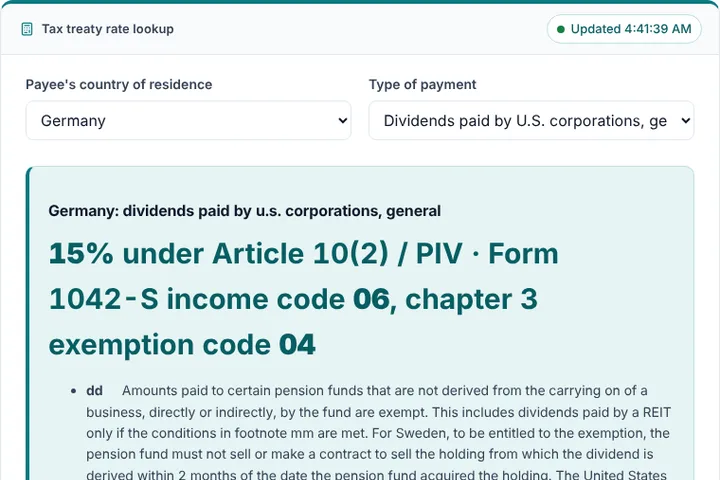
Tax treaty rate lookup filled in with a sample result
Calculator

Tax treaty rate lookup

Treaty country and payment type in; the U.S. withholding rate, the article, the IRS conditions and the Form 1042-S codes out, for all 57 treaties, plus the countries with no treaty in effect.
Form 1042-S code finder filled in with a sample result
Calculator

Form 1042-S code finder

Every 2026 Form 1042-S code, searchable: income, chapter 3 and 4 exemption, recipient status and LOB codes, with the pairings for common payments.
LOB code finder filled in with a sample result
Calculator

LOB code finder

Every limitation-on-benefits test in every U.S. tax treaty, with the Form 1042-S box 13n code and the W-8BEN-E line 14b box it maps to.
QI list lookup filled in with a sample result
Calculator

QI list lookup

Search the IRS list of approved qualified intermediaries, QI branches and QDDs by name, GIIN or country, and check a W-8IMY's QI-EIN digits and GIIN against it.
W-8 form selector filled in with a sample result
Calculator

W-8 form selector

Which certificate a payee owes you: W-9, W-8BEN, W-8BEN-E, W-8ECI, W-8EXP, W-8IMY or Form 8233, from a few questions about who they are and what the payment is for.
W-8BEN-E and W-8EXP status finder filled in with a sample result
Calculator

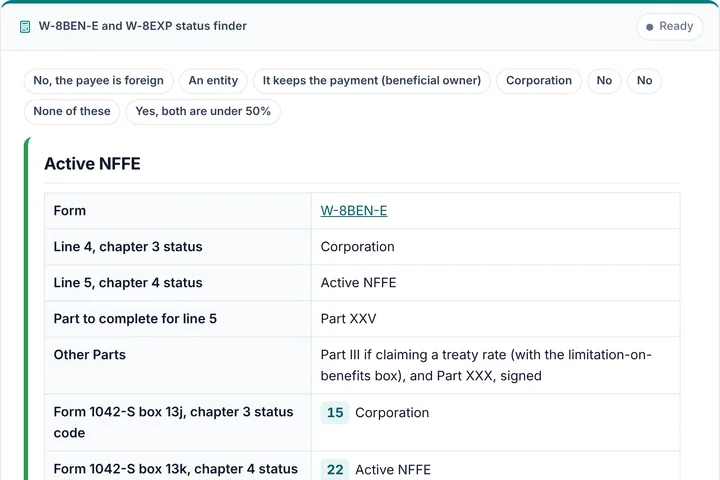
W-8BEN-E and W-8EXP status finder

A foreign entity's chapter 3 and FATCA chapter 4 statuses as they go on the W-8BEN-E or W-8EXP, the Part to complete, and the Form 1042-S status codes, from plain questions about what it does.
W-8 validity and late-cure calculator filled in with a sample result
Calculator

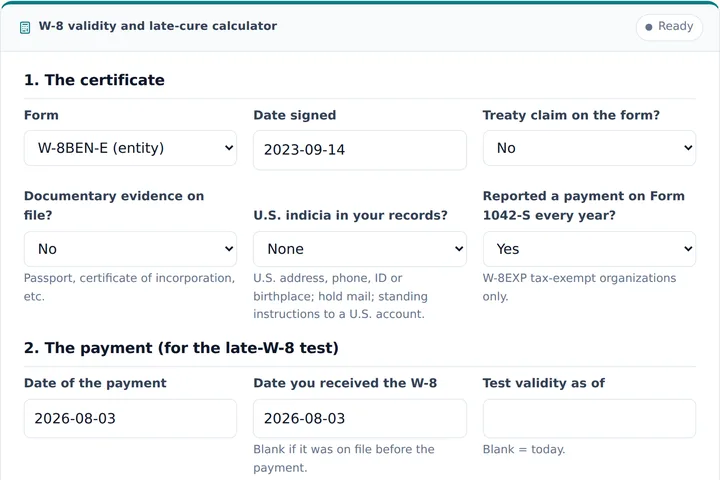
W-8 validity and late-cure calculator

When a W-8 expires, the separate treaty-claim clock, the 30-day and one-year late-W-8 rules, U.S. indicia, and the vendor-file screen examiners run first.
Form 1042 deposit penalty calculator filled in with a sample result
Calculator

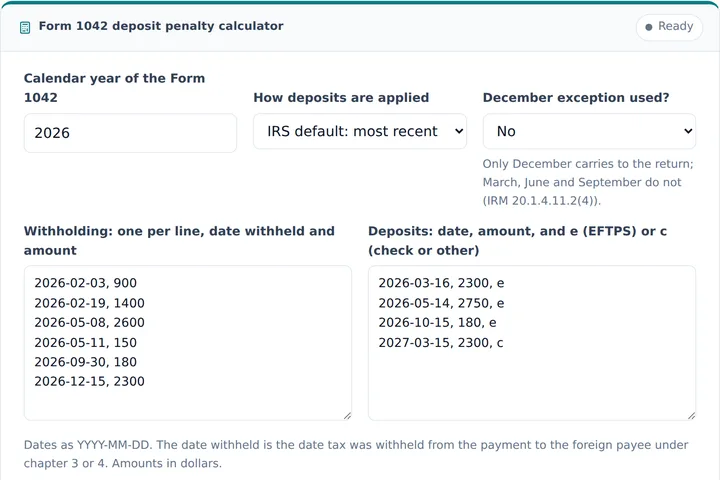
Form 1042 deposit penalty calculator

Each Form 1042 deposit due date under the quarter-monthly $2,000, $200 and December rules, and the failure-to-deposit penalty under the IRS default application or a designated order.

Forms
Form

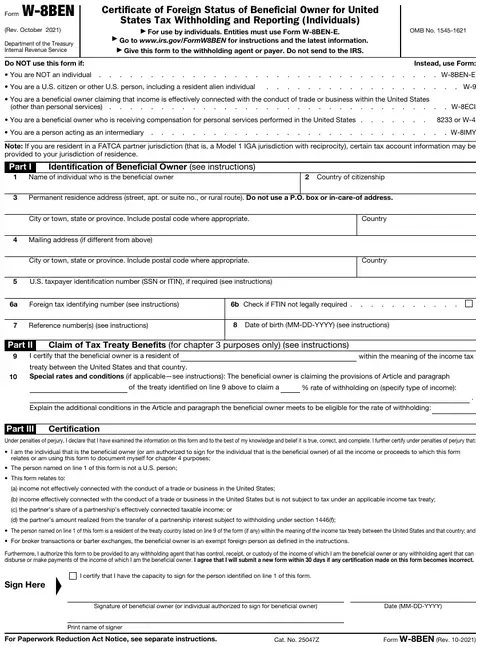
Form W-8BEN

Foreign individuals.

Form

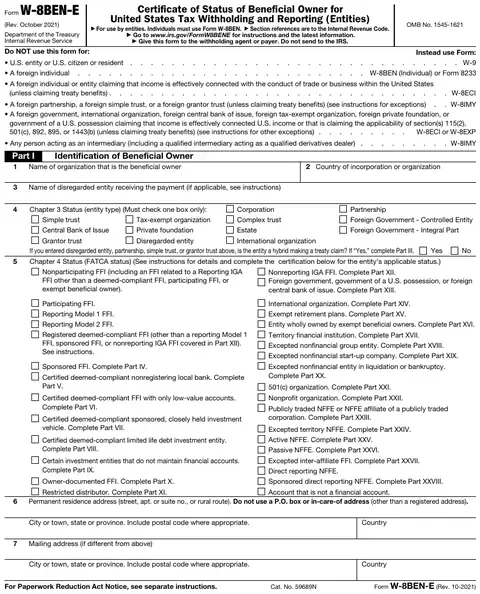
Form W-8BEN-E

Foreign entities.

Form

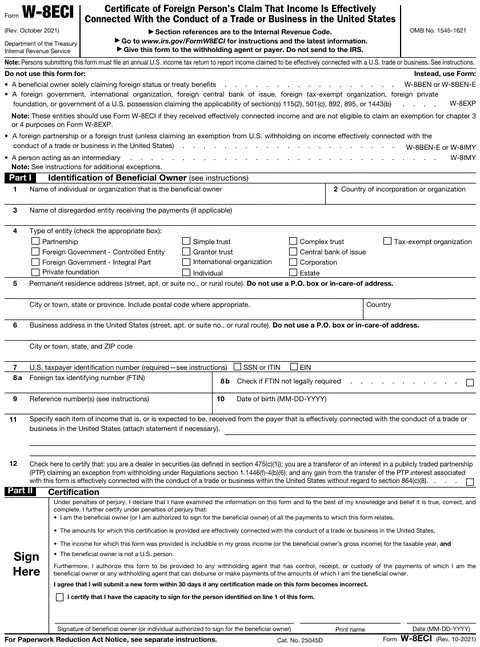
Form W-8ECI

Effectively connected income.

Form

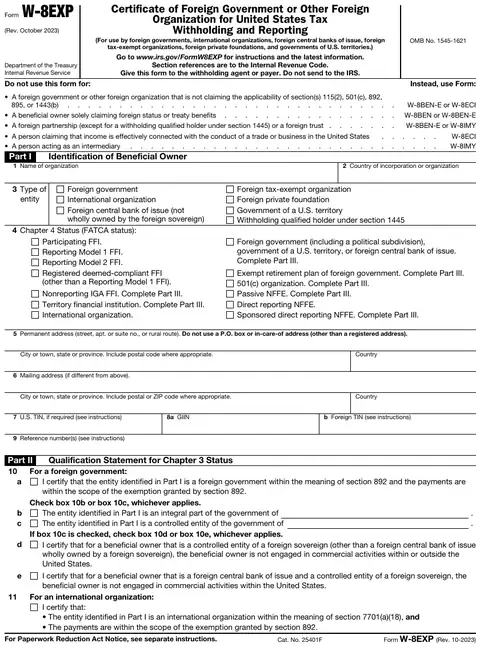
Form W-8EXP

Governments and exempt bodies.

Form

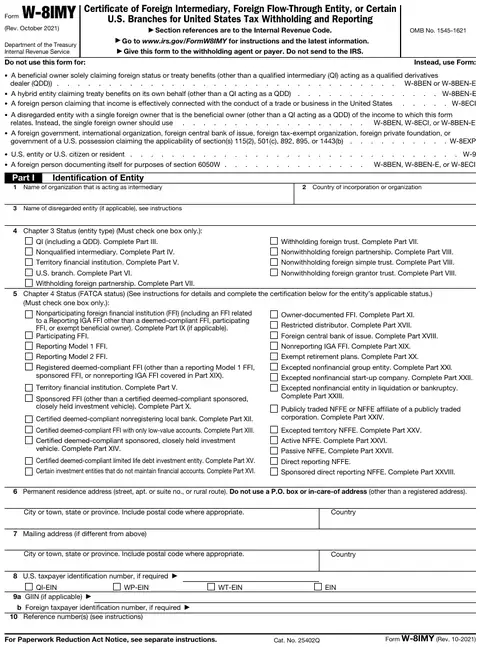
Form W-8IMY

Intermediaries and flow-throughs.

Form

Form 8233

Treaty-exempt pay for U.S. services.

Form

Form 1042-S

What you file for each payee.

Templates: W-8 request and expiry emails · Late W-8 affidavit · Withholding agent ITIN exception letter