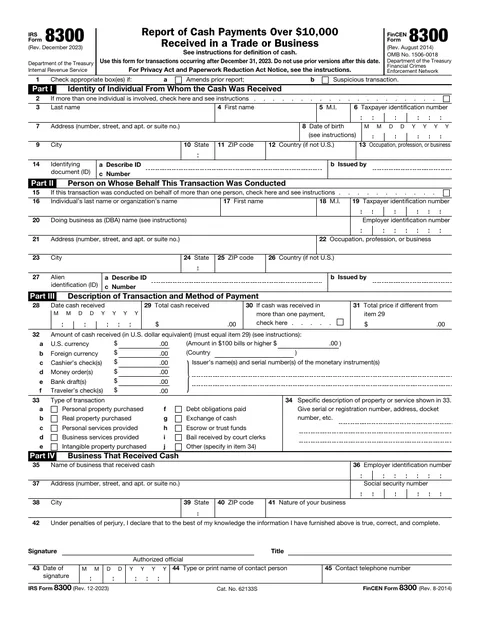
- Who must file
- The $10,000 rule and related transactions
- What counts as cash
- The 15-day deadline and how to file
- The January 31 statement to the customer
- The TIN requirement and a customer who refuses
- Penalties: what carries over from 1099s and what does not
- Statutes of limitation
- How a Form 8300 exam starts and runs
- Targeted industries and the red flags examiners are given
- Governments, universities and summary forms: three Counsel memos
- Questions people ask
Who must file
The manual's rule: any "person" engaged in a trade or business who receives more than $10,000 in cash in one transaction, or in two or more related transactions, must file Form 8300 by the 15th day after receipt (IRM 4.26.10.3(1); 4.26.10.5.1)IRM 4.26.10.3(1)Internal Revenue Manual, revised July 13, 2012, irs.govIRM 4.26.10.5.1Internal Revenue Manual, revised Mar. 23, 2020, irs.gov. One form is "dual purpose," satisfying IRC 6050IIRC 6050IInternal Revenue Code, Cornell LII and 31 USC 5331 at once (IRM 4.26.10.1.2)IRM 4.26.10.1.2Internal Revenue Manual, revised Mar. 23, 2020, irs.gov. Receipts explicitly covered include payments to "accountants, attorneys, doctors, and other service providers," including cash held in trust; a collection agency's receipts "for any one account"; sales of business assets; and cash received on behalf of another (IRM 4.26.10.5.2(2))IRM 4.26.10.5.2(2)Internal Revenue Manual, revised July 13, 2012, irs.gov. A casino's shops, restaurants and hotel are separate trades or businesses that must file (IRM 4.26.12.3(3))IRM 4.26.12.3(3)Internal Revenue Manual, revised Aug. 21, 2019, irs.gov.
Exempt: financial institutions and large casinos that file CTRs, receipts outside the trade or business, transactions entirely outside the United States, and governmental units other than criminal court clerks (IRM 4.26.10.6)IRM 4.26.10.6Internal Revenue Manual, revised July 13, 2012, irs.gov. An agent who passes all the cash within 15 days into a second reportable transaction and discloses the principal's name, address and TIN need not report the first receipt (IRM 4.26.10.5.2(2))IRM 4.26.10.5.2(2)Internal Revenue Manual, irs.gov.
The $10,000 rule and related transactions
Any transactions between the same payer (or agent) and recipient within 24 hours are related, and so are transactions over a longer period if the recipient "knows, or has reason to know" they are a connected series (IRM 4.26.10.5.5(2))IRM 4.26.10.5.5(2)Internal Revenue Manual, revised July 13, 2012, irs.gov. The manual's attorney example is $8,000 in cash one month and $4,000 the next on the same case: one $12,000 transaction, reportable; a retainer plus hourly billing aggregates the same way (IRM 4.26.12.2.1(2), 4.26.12.2.4.4)IRM 4.26.12.2.1(2)Internal Revenue Manual, revised Aug. 21, 2019, irs.govIRM 4.26.12.2.4.4Internal Revenue Manual, revised Aug. 21, 2019, irs.gov. For installments the rule is in three steps (IRM 4.26.12.12.1(3)IRM 4.26.12.12.1(3)Internal Revenue Manual, irs.gov-(5), Aug. 21, 2019): if the first payment exceeds $10,000, report within 15 days; if not, aggregate payments within one year until the total exceeds $10,000 and report within 15 days of the tipping payment; then file a new Form 8300 each time previously unreported payments in a 12-month window exceed $10,000. For a dealership taking weekly cash lease or loan payments, "Each time the payments aggregate over $10,000, another Form 8300 must be filed" (IRM 4.26.12.10.1(6))IRM 4.26.12.10.1(6)Internal Revenue Manual, irs.gov.
In construction the transaction is the contract or accepted bid "including all change orders and add-ons" (IRM 4.26.12.4.6(1))IRM 4.26.12.4.6(1)Internal Revenue Manual, revised June 1, 2006, irs.gov. Vehicle accessories agreed at purchase but paid later are related, and a husband and wife splitting one purchase is a flagged pattern (IRM 4.26.12.10.6)IRM 4.26.12.10.6Internal Revenue Manual, irs.gov. A rental agent receiving cash rent files with the lessee in Part I and the lessor in Part II; if the agent does not file, "the responsibility of the lessor to file may still exist" (IRM 4.26.12.12.1(12))IRM 4.26.12.12.1(12)Internal Revenue Manual, irs.gov.
What counts as cash
IRM 4.26.10.5.3IRM 4.26.10.5.3Internal Revenue Manual, irs.gov, 4.26.10.5.4 (July 13, 2012); IRM 4.26.12.11.1IRM 4.26.12.11.1Internal Revenue Manual, irs.gov (Aug. 21, 2019).
Cash is coin and currency, plus a cashier's check, bank draft, traveler's check or money order of $10,000 or less received in a "designated reporting transaction" or in any transaction where the recipient knows the instrument is being used to avoid reporting; a personal check is never cash (IRM 4.26.10.5.3)IRM 4.26.10.5.3Internal Revenue Manual, revised July 13, 2012, irs.gov. A designated reporting transaction is a retail sale of a consumer durable (tangible, personal-use, useful a year or more, sales price over $10,000), a collectible under IRC 408(m)(2)IRC 408Internal Revenue Code, Cornell LII, or travel or entertainment over $10,000 (IRM 4.26.10.5.4(2))IRM 4.26.10.5.4(2)Internal Revenue Manual, irs.gov. Even there, an instrument is not cash when it is bank loan proceeds (you may rely on a copy of the loan document), a payment on an ordinary-course installment contract where the first 60 days of payments do not exceed half the price, or a down payment received more than 60 days before the sale (IRM 4.26.10.5.4(3))IRM 4.26.10.5.4(3)Internal Revenue Manual, irs.gov.
The dealer trap: sales tax and fees count toward the amount you report but not toward whether the item is a consumer durable. A $9,900 car plus $600 tax and fees, paid with a $9,900 cashier's check and $600 in currency, needs no Form 8300; the same car paid with $10,500 in currency does; the same car paid with $6,000 in money orders and a $4,500 cashier's check does not (IRM 4.26.12.10.1(4)IRM 4.26.12.10.1(4)Internal Revenue Manual, irs.gov-(5), Aug. 21, 2019). A service department reports more than $10,000 in currency within 24 hours, but cash equivalents paid for service are not reportable "because services are not a designated reporting transaction" (IRM 4.26.12.10.1(1))IRM 4.26.12.10.1(1)Internal Revenue Manual, irs.gov. A wholesaler reports instruments only with actual knowledge, but "cannot deliberately avoid knowledge of the facts... willful blindness" (IRM 4.26.12.11.1)IRM 4.26.12.11.1Internal Revenue Manual, irs.gov.
The 15-day deadline and how to file
IRM 4.26.10.3IRM 4.26.10.3Internal Revenue Manual, irs.gov, 4.26.10.7.1, 4.26.10.7.2, 4.26.10.10.3.1 (July 13, 2012 and Mar. 23, 2020); IRM 4.26.11.10.4(5)IRM 4.26.11.10.4(5)Internal Revenue Manual, irs.gov (Aug. 4, 2021).
On paper the postmark controls if it is on or before day 15; later, the form is filed when received. For e-file, "the date and time in the filer's time zone when the Form 8300 is transmitted controls" and the acknowledgment "will serve as evidence of when the form was filed" (IRM 4.26.10.7.1(2))IRM 4.26.10.7.1(2)Internal Revenue Manual, revised Mar. 23, 2020, irs.gov. Keep each form five years (IRM 4.26.10.7.1(7))IRM 4.26.10.7.1(7)Internal Revenue Manual, irs.gov; verify identity before completing the transaction and record the document on the form (IRM 4.26.10.7.1(4)IRM 4.26.10.7.1(4)Internal Revenue Manual, irs.gov-(6)).
The e-file mandate, as the processing manual states it: from January 1, 2024 a business must e-file Forms 8300 if it must file at least 10 information returns of other types (1099s, W-2s) in the year, and a hardship waiver allows paper "for the duration of the calendar year" (IRM 3.11.250.3(2))IRM 3.11.250.3(2)Internal Revenue Manual, revised Dec. 13, 2024, irs.gov. The exam manual contradicts it: IRM 4.26.11.10.8(6)IRM 4.26.11.10.8(6)Internal Revenue Manual, irs.gov (Aug. 4, 2021) still says "Taxpayers currently still have the option to paper file Form 8300... e-file is currently under consideration." The processing chapter is the later statement; a business with 10 or more other returns should assume the mandate applies (see the e-file waiver guide). A paper form is keyed at Kansas City, and a missing last name, TIN (unless an ID is shown), date, total cash, business name or EIN, or any white-out, gets it pulled rather than filed; clerks "Do not enter data from a copy of Driver's License, invoice, and or other documents attached" (IRM 3.11.250.11.6.2; 3.11.250.11.6.7)IRM 3.11.250.11.6.2Internal Revenue Manual, revised Dec. 13, 2024, irs.govIRM 3.11.250.11.6.7Internal Revenue Manual, revised Jan. 1, 2023, irs.gov.
The January 31 statement to the customer
By January 31 of the following year the business must give each person named on a Form 8300 a written statement with the name, address and telephone number of the business's contact, the aggregate reportable cash received from that person during the year, and that it was reported to the IRS (IRM 4.26.10.3(4), 4.26.10.7.2(1))IRM 4.26.10.3(4)Internal Revenue Manual, revised July 13, 2012, irs.govIRM 4.26.10.7.2(1)Internal Revenue Manual, revised July 13, 2012, irs.gov. No format is prescribed; mailing to the last known address is furnishing (IRM 4.26.10.7.2(3)IRM 4.26.10.7.2(3)Internal Revenue Manual, irs.gov-(4)).
"The practice of providing a copy of the Form 8300 to the payer at the time of sale or sending multiple copies at year's end does not meet the Form 8300 notice requirements" (IRM 4.26.10.7.2(6))IRM 4.26.10.7.2(6)Internal Revenue Manual, revised July 13, 2012, irs.gov. When a customer had more than one reportable transaction, one aggregated statement is required. A copy of the filed form is acceptable only when there was a single Form 8300 for that customer in the year, it is given after year-end, and "the filer should redact his/her TIN from the copy" (IRM 4.26.10.7.2(5))IRM 4.26.10.7.2(5)Internal Revenue Manual, irs.gov.
"The customer is not to be notified when a Form 8300 is voluntarily filed" (IRM 4.26.10.7.1(6), 4.26.10.7.2(2))IRM 4.26.10.7.1(6)Internal Revenue Manual, revised July 13, 2012, irs.govIRM 4.26.10.7.2(2)Internal Revenue Manual, revised July 13, 2012, irs.gov. A suspicious-transaction form (Box 1b) filed at any amount stays out of the January 31 statement.
A Title 26 exam checks the statements, and that check "will extend into" the following January (IRM 4.26.11.8.3.2(11))IRM 4.26.11.8.3.2(11)Internal Revenue Manual, revised Aug. 4, 2021, irs.gov; examiners may contact customers to verify (IRM 4.26.11.13.3(1))IRM 4.26.11.13.3(1)Internal Revenue Manual, irs.gov. The annual statement template carries the required elements.
The TIN requirement and a customer who refuses
The form must carry the payer's name, address and TIN, the amount, date and nature of the transaction, and the ID used. "Failure to complete the form in its entirety is considered an incomplete form and is subject to a penalty." If the customer refused, "the business can notate in the corresponding field that the customer refused to provide identification. If not indicated on Form 8300, examiner should inquire if an attempt was made" (IRM 4.26.10.7.1(3))IRM 4.26.10.7.1(3)Internal Revenue Manual, revised Mar. 23, 2020, irs.gov. A missing TIN is never inconsequential (IRM 4.26.10.10.1(7))IRM 4.26.10.10.1(7)Internal Revenue Manual, irs.gov, and the only route to a waiver is the solicitation safe harbor the manual lays out (IRM 4.26.10.10.3.1(3)IRM 4.26.10.10.3.1(3)Internal Revenue Manual, irs.gov-(10), July 13, 2012):
- Initial solicitation "at the time the transaction occurs," oral or written in person, or by the same channel for a mail, phone or electronic transaction; an account application asking for the TIN counts.
- One annual solicitation by December 31 of the transaction year, or January 31 if the transaction was in December, telling the person they are "subject to a $50 penalty imposed by the Internal Revenue Service under IRC 6723IRC 6723Internal Revenue Code, Cornell LII" for not furnishing it.
- Contemporaneous records: "The filer must maintain contemporaneous records showing that the solicitation was properly made."
- No second annual solicitation, and none at all if there were no reportable transactions with that person the following year.
"Only two solicitations are required... the initial solicitation and a follow-up solicitation at the end of the year." With both made and no TIN obtained, "the business has satisfied its requirement to act in a reasonable manner... Therefore, the penalty is waived" (IRM 4.26.10.10.3.1(6)IRM 4.26.10.10.3.1(6)Internal Revenue Manual, irs.gov-(7), July 13, 2012). Miss one and "the penalty will apply to the year in which the filer failed to make the initial solicitation" (IRM 4.26.10.10.3.1(8))IRM 4.26.10.10.3.1(8)Internal Revenue Manual, irs.gov.
The solicitation letter and log template has the $50 warning and a log page; the W-9 solicitation guide covers the general regime.
One processing detail decides whether a paper form with a refused TIN is filed at all. If the TIN box and the ID box are both blank, the Kansas City clerk pulls the form, unless the Comments or an attached statement says the TIN was "refused," "denied," "not given," "not provided" or "unknown," in which case the ID is keyed "Other" and "Unknown" and the form goes into the FinCEN database (IRM 3.11.250.11.6.5, 3.11.250.11.6.6)IRM 3.11.250.11.6.5Internal Revenue Manual, revised Jan. 1, 2023, irs.govIRM 3.11.250.11.6.6Internal Revenue Manual, revised Jan. 1, 2023, irs.gov. Write the refusal in the Comments; a blank box is a form that never gets filed.
Penalties: what carries over from 1099s and what does not
IRC 6721IRC 6721Internal Revenue Code, Cornell LII covers a form not filed, late or incomplete; IRC 6722IRC 6722Internal Revenue Code, Cornell LII covers the customer statement. The 6721 figures the manual prints are dated: $50 per return with a $500,000 cap if corrected within 30 days, otherwise $260 ($270 after January 1, 2019) with a $3,000,000 cap, and unprinted "lower caps" for gross receipts of $5 million or less; examiners are sent to a "BSA Policy SharePoint for penalty rates and maximum amounts with inflationary adjustments" (IRM 4.26.10.10.1(5)IRM 4.26.10.10.1(5)Internal Revenue Manual, irs.gov-(6), Mar. 23, 2020). A background section elsewhere says "$250 per return" and "$500 per form, with no cap" if intentional (IRM 4.26.11.1.1)IRM 4.26.11.1.1Internal Revenue Manual, revised Feb. 6, 2026, irs.gov; the manual does not reconcile the two. The penalty calculator uses the 4.26.10 figures and says so.
Two 1099 features do not apply: the "corrected by August 1" tier and the de minimis exception, "because Form 8300 is not due February 28/March 15" (IRM 4.26.10.10.1(8))IRM 4.26.10.10.1(8)Internal Revenue Manual, irs.gov. Intentional disregard is the greater of $25,000 per return or the cash received in the transaction up to $100,000, no annual cap (IRM 4.26.10.10.1(9))IRM 4.26.10.10.1(9)Internal Revenue Manual, irs.gov. Those are the base amounts in the statute. Indexed for inflation, the figure is the greater of $34,930 or the cash received up to $139,500 for a return required to be filed in 2027 (Rev. Proc. 2025-32, sec. 3.57), and the greater of $36,060 or the cash received up to $144,000 for a return required to be filed in 2028 (Rev. Proc. 2026-35, sec. 3.62). For 6722 the manual prints $50 within 30 days, $100 by August 1, $260 or $270 after, and for intentional disregard the greater of $500 per statement or 10 percent of the aggregate amount, no cap (IRM 4.26.10.10.2)IRM 4.26.10.10.2Internal Revenue Manual, irs.gov. Structuring carries the same civil penalties (IRM 4.26.10.10.5.1)IRM 4.26.10.10.5.1Internal Revenue Manual, irs.gov.
In a non-filing exam the examiner may let the business file a single Form 8300 covering all the missed receipts from one customer in a prior year, with the dates in the Comments and a statement that it is filed at the examiner's request. That is a filing convenience only: "penalties... should be assessed on the total number of delinquent Forms 8300" (IRM 4.26.11.10.8.1)IRM 4.26.11.10.8.1Internal Revenue Manual, revised Aug. 4, 2021, irs.gov.
The penalty is proposed by letter after an exam, not through the 972CG stream, and assessed manually on Form 8278 (IRM 4.26.11.12.4)IRM 4.26.11.12.4Internal Revenue Manual, revised Aug. 4, 2021, irs.gov. Under Title 31, which reaches insurers and precious-metals dealers with anti-money-laundering programs, only FinCEN can assess, and "There are no limitations or reductions. There is no waiver for reasonable cause" (IRM 4.26.10.10.4)IRM 4.26.10.10.4Internal Revenue Manual, revised Mar. 23, 2020, irs.gov; in practice Form 8300 penalties from a Title 31 exam are assessed under Title 26 afterward (IRM 4.26.11.13.8(2), (4))IRM 4.26.11.13.8(2)Internal Revenue Manual, irs.gov.
"The business is required to prove reasonable cause, not the examiner" (IRM 4.26.11.10.8(2))IRM 4.26.11.10.8(2)Internal Revenue Manual, revised Aug. 4, 2021, irs.gov: a mitigating factor or an event beyond the filer's control, responsible conduct before and after, and rectification "ordinarily... within 30 days after the date the impediment is removed" (IRM 4.26.10.10.3)IRM 4.26.10.10.3Internal Revenue Manual, revised July 13, 2012, irs.gov. First-time abatement is not mentioned in the Form 8300 manual.
Statutes of limitation
| Penalty | Period | Source |
|---|---|---|
| IRC 6721IRC 6721Internal Revenue Code, Cornell LII on a filed Form 8300 | Three years from the later of the due date or filing | IRM 4.26.10.11.1IRM 4.26.10.11.1Internal Revenue Manual, irs.gov (Mar. 23, 2020) |
| IRC 6721IRC 6721Internal Revenue Code, Cornell LII on an unfiled Form 8300 | "Penalties may be assessed at any time" | IRM 4.26.10.11.1IRM 4.26.10.11.1Internal Revenue Manual, irs.gov |
| IRC 6722IRC 6722Internal Revenue Code, Cornell LII on the customer statement | No statute at all | IRM 4.26.10.11.1IRM 4.26.10.11.1Internal Revenue Manual, irs.gov; 4.26.11.13.9 (May 29, 2019) |
| Title 31 (FinCEN) | Six years from the transaction, filed or not | IRM 4.26.10.11.2IRM 4.26.10.11.2Internal Revenue Manual, irs.gov (July 13, 2012) |
An extension uses Form 872 with "tax" lined through and "penalties prescribed by IRC 6721IRC 6721Internal Revenue Code, Cornell LII" written in; no form exists for 6722 (IRM 4.26.11.13.9(6)IRM 4.26.11.13.9(6)Internal Revenue Manual, irs.gov-(7), May 29, 2019).
How a Form 8300 exam starts and runs
Cases are built from BSA Search, the FinCEN database: the business's own filing history, Forms 8300 filed on the business or its owners, bank CTRs showing large cash deposits (which "indicates that the business might be receiving more than $10,000 in cash"), and SARs (IRM 4.26.11.8.3(6))IRM 4.26.11.8.3(6)Internal Revenue Manual, revised Feb. 6, 2026, irs.gov; the selection criteria at IRM 4.26.11.4(2)IRM 4.26.11.4(2)Internal Revenue Manual, irs.gov-(4) are redacted. Income tax examiners refer violations on Form 5346 (IRM 4.26.11.3(2))IRM 4.26.11.3(2)Internal Revenue Manual, revised Aug. 4, 2021, irs.gov. Initial contact is by mail only, Letter 2277 with a Form 4564 document request, a blank Form 8300 and Publications 1, 1544 and 5264, and no phone call until 14 calendar days after mailing (IRM 4.26.11.9, 4.26.11.9.2)IRM 4.26.11.9Internal Revenue Manual, revised Aug. 4, 2021, irs.govIRM 4.26.11.9.2Internal Revenue Manual, revised Aug. 4, 2021, irs.gov. The examiner opens by saying it is "NOT an income tax examination," though information "may be used for any tax matter permitted by the Internal Revenue Code" (IRM 4.26.11.10.1(2), 4.26.11.10.2(8))IRM 4.26.11.10.1(2)Internal Revenue Manual, irs.govIRM 4.26.11.10.2(8)Internal Revenue Manual, irs.gov.
The period is the last full calendar year, with six risk-selected months examined in depth, expanded if violations or weak controls appear (IRM 4.26.11.8.3.2)IRM 4.26.11.8.3.2Internal Revenue Manual, irs.gov. The records list: retained Forms 8300 reconciled to BSA Search; bank CTRs compared to Forms 8300 for "filing to reporting ratios"; deposit slips; cash receipts journals; the customer statements; a trace of one cash receipt to its filing; and an employee list showing separation of duties (IRM 4.26.11.10.4(5)IRM 4.26.11.10.4(5)Internal Revenue Manual, irs.gov-(6)). Closing letters (IRM 4.26.11.7.1.1; 4.26.11.11.3.2-3)IRM 4.26.11.7.1.1Internal Revenue Manual, revised Feb. 6, 2026, irs.govIRM 4.26.11.11.3.2-3Internal Revenue Manual, irs.gov:
| Letter | Meaning | Appeal |
|---|---|---|
| Letter 4280 | Form 8300 no issue | None needed |
| Letter 4595 | Penalty proposed, no intentional disregard, 30 days, Form 14141 agreement | No pre-assessment appeal: write for a manager meeting, then assessed, appeal afterward |
| Letter 4596 | Intentional disregard proposed, 30 days, Form 14141 | Pre-assessment Appeals; small case request at $25,000 or less (Form 12203), formal protest above |
| Letter 1112 | Title 31 violation notification | Penalty, if any, is FinCEN's |
Verbatim: "Except for the intentional disregard penalties... the business does not have pre-assessment appeal rights" (IRM 4.26.11.11.3.2(11)IRM 4.26.11.11.3.2(11)Internal Revenue Manual, irs.gov-(12), Feb. 6, 2026). Delinquent returns are secured at the exam unless intentional disregard or a criminal referral is being weighed (IRM 4.26.11.10.8)IRM 4.26.11.10.8Internal Revenue Manual, irs.gov. The notice decoder covers Letters 2277, 4280, 4595 and 4596.
On the audit inventory system a Form 8300 review is opened under activity code 509, “Form 8300 Compliance Review” (Document 6209, 2023, Section 12).
Targeted industries and the red flags examiners are given
IRM 4.26.12IRM 4.26.12Internal Revenue Manual, irs.gov gives its own subsection to attorneys, casinos, construction, court clerks, escrow and title, mobile housing, bail bonds, collection agencies, medical practices, real estate brokers, travel agencies, antique, art, coin, jewelry and pawn dealers, vehicle and watercraft dealers, beverage and tobacco wholesalers, rentals and insurers. The history section describes targeting that moved from "car dealerships, real estate, and jewelry" to "automated systems to identify non-filers" and then "data analytics and artificial intelligence... cash-based businesses" (IRM 4.26.11.1.1(4))IRM 4.26.11.1.1(4)Internal Revenue Manual, revised Feb. 6, 2026, irs.gov.
Indicators examiners are told to look for (IRM 4.26.11.10.10)IRM 4.26.11.10.10Internal Revenue Manual, revised Aug. 4, 2021, irs.gov: "Few filed Form 8300, but many CTRs filed on the business"; multiple accounts or entities for deposits; more than one receipt per transaction; receipts recorded over several days; two cash deposits against one receipt; advising customers how to structure; and the date of the first Form 8300 ever filed, used as proof of knowledge for later failures. Worked examples: an $11,500 necklace paid $9,900 in cash plus a $1,600 check (IRM 4.26.11.10.4(7))IRM 4.26.11.10.4(7)Internal Revenue Manual, irs.gov; twenty-two $500 money orders (IRM 4.26.12.2.1(5))IRM 4.26.12.2.1(5)Internal Revenue Manual, irs.gov; "Use of money orders and cashier's checks less than $3,000 could be an indication of structuring" (IRM 4.26.12.9.5(7))IRM 4.26.12.9.5(7)Internal Revenue Manual, irs.gov; voided receipts and held checks later redeemed in currency (IRM 4.26.12.10.5-6)IRM 4.26.12.10.5-6Internal Revenue Manual, irs.gov. On attorneys, every case the manual cites holds client identity and fee amount are not privileged (IRM 4.26.12.2.1.1)IRM 4.26.12.2.1.1Internal Revenue Manual, revised Aug. 21, 2019, irs.gov.
Governments, universities and summary forms: three Counsel memos
Three Chief Counsel memoranda fill gaps the manual leaves. None is precedent, but each is the position an examiner will be shown.
- Governmental units do not file (PMTA 2014-014, July 24, 2014). “Governmental units are exempt from reporting under I.R.C. § 6050IIRC 6050IInternal Revenue Code, Cornell LII,” and “A State department of revenue is a governmental unit and therefore is not required to file Form 8300 for the receipt of cash.” Counsel read the exemption narrowly, “to maximize the reporting under Section 6050I.”
- Instrumentalities and state universities may have to (PMTA 2014-013, July 22, 2014). “The exclusion from reporting under I.R.C. § 6050IIRC 6050IInternal Revenue Code, Cornell LII by filing Form 8300 for “governmental units” does not extend to instrumentalities of government.” Whether a public college reports cash tuition over $10,000 depends on whether it is a governmental unit or a separate entity such as a section 501(c)(3) corporation: “state colleges and universities may or may not be required under I.R.C. § 6050IIRC 6050IInternal Revenue Code, Cornell LII to report cash payments, in excess of $10,000, including tuition payments, depending upon whether they meet the definition of governmental unit.”
- One summary form for missed years (PMTA 2018-11, April 12, 2018). In a non-filing exam the examiner may ask for one Form 8300 summarizing a customer's cash for a past year: “there is no legal prohibition against the IRS requesting that a business file one Form 8300 that summarizes what the business should have previously reported on multiple Forms 8300.” Attach the request, and expect no discount: “Penalties under I.R.C. § 6721(a)IRC 6721Internal Revenue Code, Cornell LII or I.R.C. § 6721(e)IRC 6721Internal Revenue Code, Cornell LII, if appropriate, should be asserted on the total number of delinquent Forms 8300.”
Questions people ask
We gave the customer a copy of the Form 8300 at the sale. Is the January 31 statement still due?
Yes. The manual says a copy at the time of sale "does not meet the Form 8300 notice requirements" (IRM 4.26.10.7.2(6))IRM 4.26.10.7.2(6)Internal Revenue Manual, irs.gov. Send one statement after year-end covering the year's total; if there was only one form for that customer, a copy given after year-end works, with your TIN redacted.
The customer refused to give a TIN. Can we still file?
File on time without it and write the refusal in the Comments section; on a paper form that is what gets it keyed instead of pulled (IRM 3.11.250.11.6.5)IRM 3.11.250.11.6.5Internal Revenue Manual, irs.gov. Then make the annual solicitation with the $50 IRC 6723IRC 6723Internal Revenue Code, Cornell LII warning by December 31 (January 31 for a December transaction) and keep contemporaneous records. Two solicitations made and documented, and the manual says the penalty is waived (IRM 4.26.10.10.3.1(6))IRM 4.26.10.10.3.1(6)Internal Revenue Manual, irs.gov.
A customer pays $3,000 a month on a $30,000 contract. When do we file?
Aggregate within the year; the fourth payment takes the unreported total over $10,000, so file within 15 days of it. Then start a new count, and file again each time the previously unreported payments in a 12-month window exceed $10,000 (IRM 4.26.12.12.1(3)IRM 4.26.12.12.1(3)Internal Revenue Manual, irs.gov-(5)). A new form each time, not one form for the contract.
We found unfiled Forms 8300 from three years ago. Is the IRS out of time?
Not on an unfiled form: "Penalties may be assessed at any time," and there is no statute on the 6722 statement penalty either (IRM 4.26.10.11.1)IRM 4.26.10.11.1Internal Revenue Manual, irs.gov. Filing now starts the three-year period on 6721 and is what the manual's reasonable-cause standard calls rectification.