- What it is
- The deadline
- What to do
- Where CP504 sits in the collection sequence
- The three things that stop it
- What comes after CP504 on a business account
- Paying it off in instalments
- If the balance is Form 945 backup withholding: the people behind the business
- The business payment plan, as the field manual grants it
- CDP hearing or CAP: which appeal does what
- The lien that usually follows, and its own hearing
- Arguing the balance itself in the hearing: the prior-opportunity rule
- Questions
Is this about your personal tax return, not a business? A CP504 on a personal account means a balance is unpaid and the IRS intends to levy your state tax refund, and can move on to wages or bank accounts after further notice. You have 30 days from the notice date. Pay what you can, set up a payment plan at irs.gov/payments, or call the number on the notice if the balance is wrong. The IRS page for this notice. The rest of this page goes deeper, from the side of the businesses that file 1099s; the parts on how the IRS handles the letter apply to you too.
What CP504 / CP504B is
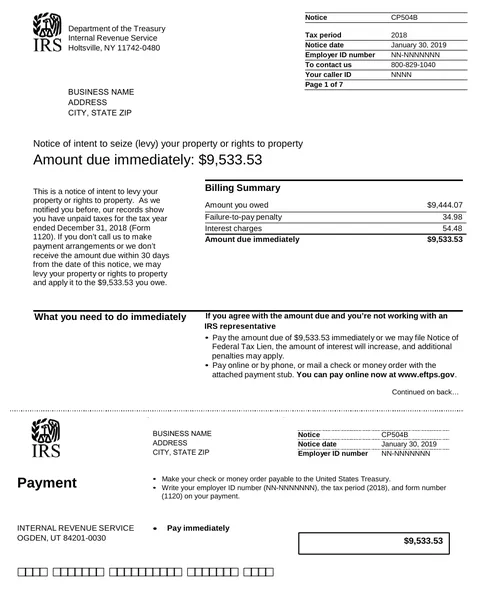
A collection notice for an unpaid balance, including an assessed information-return penalty that was never paid or abated, or a Form 945 assessment from the backup withholding compliance check. On a business account it is the second and last notice before lien or levy: per IRM 4.19.26.14.3IRM 4.19.26.14.3Internal Revenue Manual, irs.gov, "the first and final notices are the only notices issued."
Where this sits: CP2100 (the mismatch list) → B-Notices to payees → Notice 972CG a year later (the proposed penalty) → CP15 or CP215 if it isn't waived (the assessment) → CP504 if it isn't paid (collection). Letters 1948-C, 854-C and 6304-C are the IRS's replies to your 972CG response.
The deadline
Pay, set up a payment plan, or resolve the underlying penalty before the date shown. This is late in the process; a reasonable-cause request is still possible but collection is now running in parallel.
What to do
Find the original 972CG and CP15/CP215, or the Letter 6112-A; if you have a reasonable-cause case or a TIN-on-file statement that was never made, make it now and ask for a collection hold while it is considered.
Where CP504 sits in the collection sequence
A business balance that goes unpaid produces a short, fixed series of notices. The first is the bill itself: a CP15 or CP215 for an assessed penalty, a CP161 or CP210 for a tax balance such as a Form 945 assessment. If nothing happens, the account moves to CP504 (CP504B on a business account), which the IRS titles a Notice of Intent to Levy. Its immediate legal effect is narrower than the title suggests: it authorizes the IRS to take a state tax refund and begins the search for assets, but a levy on a bank account or receivables requires one more letter, the LT11 or Letter 1058, which carries the right to a Collection Due Process hearing. CP504 is the warning that the letter is next, and on a business account it is the last warning the IRS is required to send before it.
It also marks a change in who you are dealing with. Up to this point the balance belongs to the campus that assessed it; after CP504 it can be assigned to Automated Collection or a revenue officer, and a reasonable-cause request mailed to the penalty unit no longer stops anything by itself.
The three things that stop it
Paying the balance ends it. A business that cannot pay in full can request an installment agreement, online for smaller balances or on Form 9465 or by phone for larger ones, and collection action pauses while a request is pending and while an agreement is in good standing. The third route is to attack the balance itself: if the penalty was assessed because a Notice 972CG went unanswered, or a Letter 6112-A was never disputed, a reasonable-cause or TIN-on-file statement can still be made now, and the request should say in its first paragraph that a CP504 has issued and ask for a collection hold while it is considered. Make that request to the unit that assessed the penalty, pay anything that is not in dispute, and keep the CP504 and the mailing proof together. If the LT11 arrives before the matter is resolved, the Collection Due Process request on Form 12153 must be filed within 30 days of that letter; it is the point in the process where an independent Appeals officer can consider the underlying penalty, and it should not be missed. The after-the-denial guide covers the reconsideration and appeal routes.
What comes after CP504 on a business account
CP504 is the last campus notice. The next letter is the Collection Due Process notice: "ACS uses an LT11 (Notice of Intent to Levy and Your Notice of a Right to a Hearing) to inform taxpayers of our intent to levy and provide due process hearing rights prior to levy," revenue officers use Letter 1058, and "The taxpayer MUST have been issued an LT11 or equivalent on or after 1/19/99 in order to levy" (IRM 5.19.4.3.1)IRM 5.19.4.3.1Internal Revenue Manual, revised July 10, 2023, irs.gov. It goes certified to the last known address, "A minimum of thirty days must elapse between issuance of the LT11 and the date the levy is requested," and ACS sets "a systemic 53-day follow-up" to levy (IRM 5.19.4.3.1)IRM 5.19.4.3.1Internal Revenue Manual, irs.gov. The LT11 is issued "ONLY where the next action will be to levy" and only if a levy source exists (IRM 5.19.4.3.1)IRM 5.19.4.3.1Internal Revenue Manual, irs.gov; the sources are built from information returns, so a payer's own 1099 filings are where ACS looks (see the vendor levy page).
Form 945 is employment tax, and that changes one thing. Under the Disqualified Employment Tax Levy, the IRS may levy "without prior CDP rights" when the taxpayer "requested a CDP hearing under section 6330 for unpaid employment taxes arising in the two-year period prior to the beginning of the taxable period for which the levy is served," provided the CP504 or a status 58 notice was issued (IRM 5.19.4.3.1.1)IRM 5.19.4.3.1.1Internal Revenue Manual, revised June 1, 2020, irs.gov. A payer that contested one Form 945 assessment at a hearing can be levied on the next one after the CP504 alone, with the hearing afterward.
Paying it off in instalments
The terms depend on which module the balance sits on. A Form 945 balance is trust-fund tax and qualifies for the "Simple Payment Plan (Business Trust Fund)": available to businesses "who have an unpaid balance of assessment of $25,000 or less," with no financial statement and no managerial approval, on condition that "Taxpayers must be in filing compliance ... If not, the IA will not be granted," that the business is current on federal tax deposits, and that "The entire liability including accruals must be fully paid by the CSED" (IRM 5.19.1.6.4.2)IRM 5.19.1.6.4.2Internal Revenue Manual, revised Dec. 5, 2025, irs.gov. A business above $25,000 "can choose to reduce their liability to $25,000 or less by making a lump sum payment in order to participate," paid before the agreement is set up (IRM 5.19.1.6.4.2 Note)IRM 5.19.1.6.4.2 NoteInternal Revenue Manual, irs.gov. A request with delinquent returns outstanding is denied, and "accounts with delinquent returns do not qualify for independent review or appeal rights" (IRM 5.19.1.6.4.2)IRM 5.19.1.6.4.2Internal Revenue Manual, irs.gov.
An assessed information-return penalty (a CP15 or CP215 balance on the civil penalty module, MFT 13) is not trust fund. Within the employee's authority level it gets a non-trust-fund agreement after a full compliance check: "No financial statement is required. No managerial approval is required. No NFTL determination is required" (IRM 5.19.1.6.4.3)IRM 5.19.1.6.4.3Internal Revenue Manual, revised Sept. 22, 2022, irs.gov. Payments on that module should be marked so they post there: the memo line carries "CVPN" after the TIN and "MFT 13" (IRM 5.19.1IRM 5.19.1Internal Revenue Manual, irs.gov payment-application table). A balance under the collection tolerance may be closed without further action, but the amounts for civil penalty modules are redacted in the manual (IRM 5.19.1.2.6.1)IRM 5.19.1.2.6.1Internal Revenue Manual, revised Mar. 1, 2016, irs.gov.
If the balance is Form 945 backup withholding: the people behind the business
A CP504 on a Form 945 module is a notice about trust fund tax, and the collection manuals treat it differently from a penalty balance. For "Form 945, Annual Return of Withheld Federal Income Tax - TFRP is one hundred percent of the tax" (IRM 5.7.4.3)IRM 5.7.4.3Internal Revenue Manual, revised July 1, 2025, irs.gov: the whole unpaid backup withholding can be assessed personally, under IRC 6672IRC 6672Internal Revenue Code, Cornell LII, against each person who had "Authority to determine which creditors will or will not be paid" (IRM 5.7.3.4.1)IRM 5.7.3.4.1Internal Revenue Manual, revised Aug. 6, 2015, irs.gov and let other creditors be paid first. The revenue officer interviews every potentially responsible person on Form 4180 at first contact, then issues each one a Letter 1153 with Form 2751, certified or by hand, with 60 days to protest to Appeals before the assessment (IRM 5.7.4.7; 5.7.3.7.2)IRM 5.7.4.7Internal Revenue Manual, revised Mar. 27, 2023, irs.govIRM 5.7.3.7.2Internal Revenue Manual, revised July 24, 2023, irs.gov.
The Simple Payment Plan described above matters here for a second reason: "No TFRP determination is required on cases meeting the requirements for In-Business Trust Fund Express Installment Agreements," and under a full in-business agreement "generally the TFRP will not be assessed if the taxpayer meets the terms" (IRM 5.7.4.8.1)IRM 5.7.4.8.1Internal Revenue Manual, revised July 14, 2023, irs.gov. A business that sets up the plan before the interviews keeps the question off the table. The trust fund recovery penalty guide covers who is responsible, what willful means and how to designate payments.
The business payment plan, as the field manual grants it
The field manual that grants the business plan adds conditions the campus description leaves out. "A Simple Payment Plan (Business Trust Fund) may be granted when all of the following criteria are met": the aggregate unpaid balance of assessment "is $25,000 or less," the balance "must be $25,000 or less at the time the agreement is granted. The taxpayer may pay the balance down before the agreement is granted, but may not use the first installment payment to reduce the balance to the threshold," and it must pay in full by the collection statute (IRM 5.14.5.4)IRM 5.14.5.4Internal Revenue Manual, revised July 21, 2026, irs.gov. No field call, no financial statement and no managerial approval are needed, but "Filing and payment compliance must be verified through IDRS and confirmed with the taxpayer. If the taxpayer is not in filing compliance, a payment plan cannot be granted." It is refused when "The payment plan request is made in conjunction with a request for levy release" or the case looks like a plan "Solely to Delay" collection, including pyramiding or successor entities.
Its value to the people behind the business is conditional: "A TFRP determination is not required only when all of the following conditions are met: The unpaid balance of assessment (UBA) is $25,000 or less; The taxpayer qualifies for and is granted a Simple Payment Plan (Business Trust Fund); The entire liability will be paid in full by the Collection Statute Expiration Date (CSED); and The Simple Payment Plan is granted within 120 calendar days of case assignment on ICS" (IRM 5.14.5.4)IRM 5.14.5.4Internal Revenue Manual, irs.gov. Ask for the plan at the first contact, not after the interviews. And once a plan is in place, "Taxpayers are not permitted to designate installment agreement payments"; the agreement form says payments are applied "in the best interests of the United States," and officers who want their own money to reach the trust fund portion should pay from personal funds outside the agreement (IRM 5.14.7.5)IRM 5.14.7.5Internal Revenue Manual, revised Aug. 5, 2010, irs.gov. Balances over $25,000 go to a full in-business agreement with Form 433-B and a TFRP determination (IRM 5.14.7.4)IRM 5.14.7.4Internal Revenue Manual, revised Mar. 15, 2022, irs.gov. The TFRP guide covers the rest.
CDP hearing or CAP: which appeal does what
Two appeal routes follow a CP504, and they are not interchangeable. A Collection Due Process hearing is available once the LT11 or Letter 1058 issues: the request "Must be in writing" on Form 12153 or an equivalent, "Must be filed on or before the date that is 30 days after the date of the Notice of Intent to Levy," and must state "The reason(s) why the taxpayer disagrees with the action" (IRM 5.1.9.3.2)IRM 5.1.9.3.2Internal Revenue Manual, revised Aug. 28, 2025, irs.gov. A timely request suspends levy on the periods in the notice and suspends the collection statute; a late request within one year can be an equivalent hearing, which Appeals holds the same way but which ends in a decision letter with no Tax Court review and no statute suspension (IRM 5.1.9.3.2.2)IRM 5.1.9.3.2.2Internal Revenue Manual, revised Oct. 19, 2023, irs.gov. "Late CDP hearing requests are not automatically treated as EH requests"; the box on Form 12153 or a written statement is needed. Discussions with Collection "do not suspend the running of (or otherwise extend) the 30-day period."
The Collection Appeals Program is faster and narrower. It covers a "Levy or seizure action that has been or will be taken," a lien filing, and "Rejected, proposed for modification, modified, proposed for termination or terminated installment agreements"; "There is no deadline for requesting a CAP appeal in most situations," the request may be oral or on Form 9423, and it goes first to the group manager (IRM 5.1.9.4, 5.1.9.4.2)IRM 5.1.9.4Internal Revenue Manual, revised Aug. 28, 2025, irs.govIRM 5.1.9.4.2Internal Revenue Manual, revised Aug. 28, 2025, irs.gov. What it cannot do is the thing a payer usually wants: "CAP cannot be used to determine a taxpayer's liability including reopening examinations or claims for refund," and "Penalty appeals" and "Claims for refund or abatement" are excluded (IRM 5.1.9.4.1)IRM 5.1.9.4.1Internal Revenue Manual, irs.gov. Use CAP to stop a levy or rescue a payment plan; use the CDP hearing, where the underlying liability was never the subject of a prior opportunity to dispute it, to argue the balance; use the abatement and claim routes for the penalty itself.
The lien that usually follows, and its own hearing
A lien usually follows a balance of this size. The filing manual's rule is "the aggregate UBA is $10,000 or more: file an NFTL," with the note that "Generally NFTLs will not be filed when the UBA is less than $10,000," and almost never below $2,500 (IRM 5.12.2.6)IRM 5.12.2.6Internal Revenue Manual, revised Oct. 14, 2013, irs.gov. An installment agreement "does not meet streamlined, guaranteed, or in-business trust fund express criteria: file an NFTL," which is one more reason to qualify for the Simple Payment Plan, where "an NFTL filing determination is not required" (IRM 5.12.2.6; 5.14.5.4)IRM 5.12.2.6Internal Revenue Manual, irs.govIRM 5.14.5.4Internal Revenue Manual, irs.gov. The Notice of Federal Tax Lien is public: its purpose is to "inform certain third parties (typically a purchaser, holder of a security interest, mechanic's lienor, or judgment lien creditor) of the existence of the statutory lien" and to "establish the Government's right of priority against these same creditors," and "the NFTL may impact the taxpayer's credit rating or their ability to get credit (such as a loan, credit card, or lease)" (IRM 5.12.1.4, 5.12.1.4.2)IRM 5.12.1.4Internal Revenue Manual, revised July 11, 2018, irs.govIRM 5.12.1.4.2Internal Revenue Manual, revised July 11, 2018, irs.gov. The lien carries its own hearing right: Letter 3172 within five business days of filing, with 30 days after that period to request the IRC 6320IRC 6320Internal Revenue Code, Cornell LII hearing (IRM 5.1.9.3.2.1)IRM 5.1.9.3.2.1Internal Revenue Manual, irs.gov, and a Letter 3172 is issued again when a later lien adds an assessment the earlier one did not list (IRM 8.22.4.2.2)IRM 8.22.4.2.2Internal Revenue Manual, revised Sept. 24, 2025, irs.gov.
Arguing the balance itself in the hearing: the prior-opportunity rule
Whether you can argue the balance itself in the hearing, and not only how it is collected, turns on the prior-opportunity rule. A taxpayer may challenge the underlying liability in a CDP hearing if they did not receive a notice of deficiency or "Have a prior opportunity to dispute the tax liability" (IRM 8.22.8.3)IRM 8.22.8.3Internal Revenue Manual, revised Sept. 3, 2025, irs.gov. Appeals' list of what is a prior opportunity includes Letter 105-C, Letter 950 for a proposed employment tax assessment, Letter 1085 and Letter 1153; its list of what is not includes "Letter CP15 and CP215, Civil Penalty Notice" and "The taxpayer had the opportunity to pay the tax and file a claim for refund but did not do so" (IRM 8.22.8.3)IRM 8.22.8.3Internal Revenue Manual, irs.gov. A 1099 penalty that was simply assessed and billed can therefore be disputed on the merits at the hearing. For reasonable cause specifically, Appeals' table: where a 105C or 854C was "not issued" and the taxpayer "did not previously challenge penalty," raising it in CDP is "Yes"; where the letter was issued and the 60-day window "expired before the taxpayer requested the CDP hearing," it is "No. ... that constitutes a prior opportunity"; where the CDP request falls inside the 60 days, "Yes. The taxpayer did not have a prior opportunity as the CDP and letter periods overlap" (IRM 8.22.8.10.6)IRM 8.22.8.10.6Internal Revenue Manual, revised Aug. 26, 2020, irs.gov. To raise it, the request must identify "Tax period(s), Type of tax, Specific penalties disputed, Grounds for reasonable cause abatement"; a general "penalties should be abated" is not enough. A Form 945 balance from a compliance check or examination that was closed on a 30-day letter you received is precluded; one assessed with no 30-day letter is not. The doubt-as-to-liability page covers the other route for a penalty you can no longer contest here.
Questions about CP504 / CP504B
Who receives CP504 / CP504B?
Payer. A collection notice for an unpaid balance, including an assessed information-return penalty that was never paid or abated, or a Form 945 assessment from the backup withholding compliance check.
What is the deadline on CP504 / CP504B?
Pay, set up a payment plan, or resolve the underlying penalty before the date shown. This is late in the process; a reasonable-cause request is still possible but collection is now running in parallel.
What should I do when CP504 / CP504B arrives?
Find the original 972CG and CP15/CP215, or the Letter 6112-A; if you have a reasonable-cause case or a TIN-on-file statement that was never made, make it now and ask for a collection hold while it is considered.
Is CP504 / CP504B about my own income tax?
No. This decoder covers information reporting and withholding: the notices a payer, filer or payee sees because of Forms 1099, W-2, 945 and the TINs on them. Individual income-tax notices follow a different track.
Have a different notice? The IRS notice decoder lists all 90 in the order they tend to arrive.