The path through Code and Edit
IRM 3.11.13.6IRM 3.11.13.6Internal Revenue Manual, irs.gov, 3.11.13.7, 3.11.13.12.5, 3.11.13.13.2, 3.11.13.13.3, 3.11.13.20 (Oct. 28, 2025 transmittal).
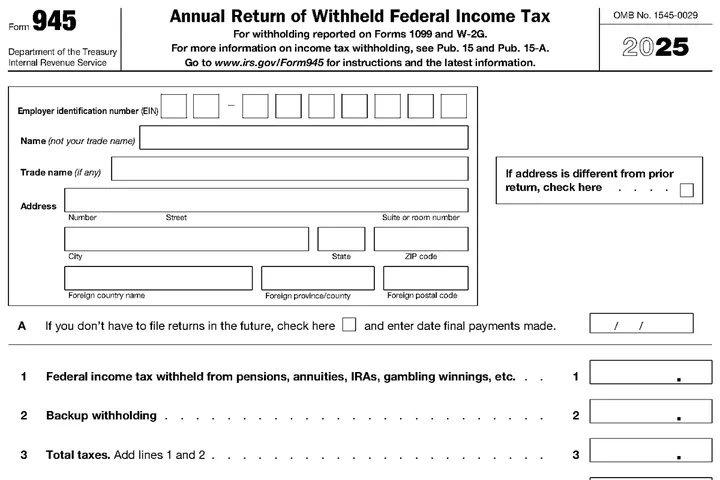
Form 945 is one of five employment tax returns handled under one chapter of the manual, and most of the rules are shared with Forms 941, 943, 944 and CT-1. The manual describes the return's purpose plainly: "Form 945 is used to report income tax withheld from non-payroll payments," the first listed being "Backup withholding" (IRM 3.11.13.20)IRM 3.11.13.20Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. Two routing rules matter before anything else. A Form 945 "with a foreign address or an address of an U.S. Possession must be processed at the Ogden Submission Processing Campus," and "Form 945 returns which have been early filed before the end of the tax year ... must be held until the first cycles of the next year" (IRM 3.11.13.20)IRM 3.11.13.20Internal Revenue Manual, irs.gov. A payer who files in December because the year's withholding is already known should not expect the return to post until January.
What makes a Form 945 unprocessable
A return "must contain specific items before it is considered processable": "An Employer Identification Number (EIN). A legible name (for name control). A valid Tax Period. Legible tax data, if tax liability is shown. A signature attesting to the perjury statement 'Jurat' shown on the document." Among the conditions that make it unprocessable: "The document has two or more different EINs," "The return is unsigned or signed in the wrong location," and tax entries "so incomplete, illegible, or contradictory that the tax liability cannot be determined" (IRM 3.11.13.6)IRM 3.11.13.6Internal Revenue Manual, revised Jan. 3, 2024, irs.gov.
The examiner is told to "Perfect all documents to the extent possible from schedules and other attachments" before giving up, so a missing EIN that appears on the attached Form 945-A is simply edited in. What cannot be perfected goes one of two ways. Entity problems (name, EIN, tax period) are routed to Entity Control or researched on IDRS. "All Other Unprocessable Conditions" draw correspondence (IRM 3.11.13.6)IRM 3.11.13.6Internal Revenue Manual, irs.gov. A refund return whose reply is insufficient or never comes is not left in suspense: the examiner enters a condition code and, if the only entries are deposits, "resolve[s] the computation by entering a sufficient amount on the income tax withholding and total lines to prevent a refund or credit." An unanswered Letter 21C on an overpaid Form 945 ends with the overpayment written away rather than refunded.
Signatures get their own rules, and they are more forgiving than most filers assume.
Form 945 may be signed by machine. "A signature of an officer or duly authorized agent, etc. can be printed, typed, rubber stamped, computer generated, or affixed by some other mechanical device, and is acceptable as a signed return on Form 941, Form 943, Form 944, Form 945, or Form CT-1," provided the filer keeps the Rev. Proc. 2005-39 letter adopting the facsimile. But "Form 8879-EMP is not an acceptable signature substitute for a paper return," and for a missing signature "Only one correspondence attempt is required" (IRM 3.11.13.12.7)IRM 3.11.13.12.7Internal Revenue Manual, revised Mar. 13, 2025, irs.gov.
The signature exceptions include returns "prepared under IRC 6020(b)IRC 6020Internal Revenue Code, Cornell LII" and "Re-entry returns originally filed electronically," and the manual presumes under Treas. Reg. 301.6064-1Treas. Reg. 301.6064-1Treasury regulations, Cornell LII that a signature is genuine. A preparer's "X" in the signature box with a printed name is accepted without correspondence; an "X" with no name is not.
The received date
"The date a document is received in the Campus or IRS Office is the date stamped as the 'IRS Received Date,'" and every return gets one. Where the stamp is after the due date but the postmark or shipment date is on or before it, the examiner edits the received date back to the postmark. Private carriers count only when "designated by the IRS and delivered via an acceptable type of service." For certified mail with no postmark, a "USPS.com Track & Confirm" record attached in front of the envelope supplies the acceptance date (IRM 3.11.13.12.5)IRM 3.11.13.12.5Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. Not every IRS office is a place for filing: a received stamp from the Taxpayer Advocate Service or Chief Counsel is circled out and replaced. If there is no stamp at all, the priority is the earliest legible postmark, then the SCAMPS digital date, then the signature date if in the current year, then the control date minus ten days.
"The taxpayer has 10 days to resubmit an electronically filed return after being rejected and 10 days to submit a paper return after the last rejection." If the paper return's postmark is within 10 days of the rejection and the MeF rejection notice is attached, the IRS received date is edited back to the rejection date; if the notice is not attached, "perfection of the Received Date is not necessary" (IRM 3.11.13.12.5)IRM 3.11.13.12.5Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. Keep the rejection and staple it to the paper return.
EIN and name control
The EIN "needs to be present on each page" and must match page 1; a different EIN on Form 945-A is overwritten from the entity section (IRM 3.11.13.13.2)IRM 3.11.13.13.2Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. An EIN that is a PTIN or ITIN, two EINs on one return, "all zeroes, or all nines," or "Pending, applied for, etc." are researched on IDRS and, if nothing is found, routed to Entity Control for assignment. A Form 945 that "is received in C&E with an EIN beginning with '69'" is forwarded for a new EIN. The name control is the four characters the name control rules describe; the examiner underlines it when it can be determined, and when it cannot, "Edit Action Code 352 (Name Research)" or route to Entity (IRM 3.11.13.13.3)IRM 3.11.13.13.3Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. A return showing "RECEIVER, TRUSTEE or DEBTOR IN POSSESSION" goes to Entity regardless. A Form 945 filed with a prior year's form and no other indication of the year is re-dated to the current year by the examiner, which is how a late return for an old year can post to the wrong one (IRM 3.11.13.13.1.3)IRM 3.11.13.13.1.3Internal Revenue Manual, irs.gov.
How the lines are edited
Lines 1, 2 and 3 are read together. "Line 2 is where the taxpayer reports any backup withholding, including backup withholding on gambling," and "Line 3 must contain an entry if Lines 1 and/or 2 contain an entry." The editing table then supplies what the filer left out: a blank line 3 is computed from lines 1 and 2; lines 1 through 3 all blank with a figure on the December line of the liability summary are filled from that figure; and a line 3 with nothing above it is moved to line 1 (IRM 3.11.13.20.2)IRM 3.11.13.20.2Internal Revenue Manual, revised Jan. 1, 2026, irs.gov.
The line-2 trap: "Line 3 has an amount and Lines 1, and 2 are blank, 'zero', or, none: Edit the Line 3 amount to Line 1 and continue to process the return" (IRM 3.11.13.20.2)IRM 3.11.13.20.2Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. A payer who writes its backup withholding only on the total line has it transcribed as pension withholding on line 1, and the backup withholding unit that reconciles line 2 to box 4 of the 1099s sees nothing on line 2.
Line 4, total deposits, is accepted as written. Lines 5 and 6a (balance due and overpayment) are computed when blank and corrected when the filer put the number on the wrong one: "Line 5 has an amount: If Line 4 amount is more than Line 3 amount, then edit the Line 5 amount to Line 6a" (IRM 3.11.13.20.4)IRM 3.11.13.20.4Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. The examiner is not checking whether your deposits actually posted; that reconciliation happens at the master file, and a mismatch there is what produces the misapplied-deposit notices. A final-return box checked with a date of final payments inside the year gets condition code F; checked with no date and tax data present, the examiner writes to ask for the date.
Form 945-A and the deposit schedule
The monthly summary on the return or the daily Form 945-A "is not required" when line 3 is under $2,500, and "Form 945-A ROFTL is required to be completed when the taxpayer is a semiweekly depositor" (IRM 3.11.13.20.6)IRM 3.11.13.20.6Internal Revenue Manual, revised Jan. 1, 2026, irs.gov. The examiner sets a schedule indicator code that tells transcription to skip the liability record when it is unnecessary, blank or incomplete, or contains a negative figure. Where both the monthly summary and a Form 945-A are completed, both are keyed and "Master File (MF) will determine the correct entry"; multiple Forms 945-A are combined onto one; an entry for a day that does not exist, such as February 29 in a common year, is moved to the last valid day of the month (IRM 3.11.13.20.7)IRM 3.11.13.20.7Internal Revenue Manual, irs.gov. The averaged penalty page explains what happens when the record the examiner keyed does not support the deposits made.
Letter 21C and the correspondence rules
Correspondence is issued "to resolve any conditions causing the return to be unworkable or unprocessable," using Form 13195, the 941/943/944/945/CT-1 correspondence action sheet, which selects paragraphs of Letter 21C (IRM 3.11.13.7)IRM 3.11.13.7Internal Revenue Manual, revised Mar. 13, 2025, irs.gov. The examiner is told to "Examine the return for all unprocessable conditions before initiating correspondence," so one letter should list everything. "It is now acceptable to receive a missing signature, Forms, etc. by fax," and the letter says so. An incomplete return that looks like a payment voucher or says "previously e-filed" goes to a lead, who checks whether a return already posted before deciding what the paper is. The refund page covers what the wait looks like from the outside.
E-filing Form 945: signatures and rejects
Form 945 and, since June 2024, Form 945-X can be filed through MeF (IRM 3.42.4.7.1.5; 3.42.4.7.1.5.1)IRM 3.42.4.7.1.5Internal Revenue Manual, revised Oct. 30, 2024, irs.govIRM 3.42.4.7.1.5.1Internal Revenue Manual, revised Jan. 1, 2026, irs.gov; Form 944-X is the one adjusted employment return that still must be on paper. "Beginning in Tax Year 2025, direct deposit functionality was added to Form 940, Form 943, Form 944, and Form 945." An electronic return "must be signed by the authorized signer of the filing entity," and "If the electronic return does not have an appropriate signature, the return will be rejected" (IRM 3.42.4.11.2)IRM 3.42.4.11.2Internal Revenue Manual, revised Jan. 1, 2024, irs.gov. Three methods matter for a Form 945 filer:
- Form 94x On-Line Signature PIN. "Only the owner or a principal of a business can apply," through approved software, "at least 45 days in advance of the due date"; the signer receives a 10-digit PIN that "must not be disclosed or shared with anyone," and the method "is not acceptable for tax professionals." Online filers are limited to five returns a year and cannot file for other businesses (IRM 3.42.4.11.2.5)IRM 3.42.4.11.2.5Internal Revenue Manual, revised Sept. 10, 2021, irs.gov. The PIN may not be given to a power of attorney, ERO, reporting agent or payroll company (IRM 3.42.4.11.4)IRM 3.42.4.11.4Internal Revenue Manual, irs.gov.
- Reporting Agent PIN. A 5-digit PIN issued to a reporting agent after Form 8655 is on file at Ogden; the agent signs the client's return (IRM 3.42.4.11.2.4)IRM 3.42.4.11.2.4Internal Revenue Manual, irs.gov. The reporting agents guide covers what the Form 8655 does and does not transfer.
- Practitioner PIN (Form 8879-EMP). The ERO method, where the taxpayer signs Form 8879-EMP and the practitioner transmits. The paper manual's warning applies in the other direction: if the e-file rejects and you fall back to paper, the 8879-EMP is not a signature on the paper return.
A rejected return is not a filed return. The ten-day rules in the received-date section above are what preserve timeliness, and only if the rejection notice travels with the paper.
Error resolution: the tax only goes up
A Form 945 that fails a math check goes to error resolution, and the error-resolution chapter treats it differently from Form 941. "Form 945 only reports withholding. Therefore, we would never lower the tax." Its example: a return showing $20,000 on lines 1 and 2 and $45,000 on line 3 is adjusted upward, "we will add $5,000.00 to Field 0201 and allow a notice to be generated" (IRM 3.12.13.80.19)IRM 3.12.13.80.19Internal Revenue Manual, revised June 1, 2021, irs.gov. A total that does not foot is resolved against you.
A negative line 1, the usual sign that a payer netted a prior-year correction into the current return, is removed. If a Form 945-X came with it, the payer gets taxpayer notice code 31 "to advise the taxpayer that their adjustment is being processed in AM"; if not, code 32 "to advise the taxpayer that their adjustment is being denied and to request the adjustment on Form 945-X." Corrections to a prior year belong on Form 945-X, never on line 1 of the current return; the Form 945-X guide covers the mechanics.
The rest of the Form 945 error-resolution chapter turns on what happens when nobody answers. Where a schedule of monthly liabilities is present but line totals are missing and no reply comes, the examiner will "Enter the greater of the two amounts" as the tax and send taxpayer notice code 27, which says the tax was adjusted "because we did not receive a reply to our request for additional information" (IRM 3.12.13.80.17)IRM 3.12.13.80.17Internal Revenue Manual, revised Aug. 23, 2022, irs.gov. A payment that arrives with no usable return data and no reply goes to the next period: "Leave Field 01ARN blank. The excess remittance will be applied to the next tax period" (IRM 3.12.13.80.9)IRM 3.12.13.80.9Internal Revenue Manual, revised Jan. 1, 2016, irs.gov. A payment with a zero-tax return and no reply can end up frozen and moved: "Prepare Form 3465, Adjustment Request, to indicate the amount to be moved to the Unidentified File (URF)" (IRM 3.12.13.80.21)IRM 3.12.13.80.21Internal Revenue Manual, revised Jan. 1, 2016, irs.gov.
Three more rules. The deposit schedule is dropped when it does not tie: for a return with line 3 under $2,500 the examiner enters SIC 1 and deletes any line 7 or Form 945-A entries, and where the schedule still disagrees after correction the examiner will "Enter '1' in Field 01SIC. Use CC DLSEC to delete Sections 03, or 05 through 16, as needed" (IRM 3.12.13.80.24)IRM 3.12.13.80.24Internal Revenue Manual, revised Aug. 24, 2020, irs.gov; the deposit penalty consequences are covered in the averaged FTD penalty. A second return marked amended that is identical to the posted one is not processed: "All information is exactly the same, SSPND 640 and route to Rejects" (IRM 3.12.13.80.8)IRM 3.12.13.80.8Internal Revenue Manual, revised Jan. 1, 2023, irs.gov. And some large refunds or balances are routed for review: absent a prior review, "Attach a Form 4227 and route to Criminal Investigation for review" (IRM 3.12.13.80.26)IRM 3.12.13.80.26Internal Revenue Manual, revised Jan. 1, 2016, irs.gov; the dollar triggers are redacted. Finally, a faxed 945 does not establish a filing date: "The Fax and EEFAX Received Dates are NOT VALID as an IRS Received Date" (IRM 3.24.13.5)IRM 3.24.13.5Internal Revenue Manual, revised Jan. 1, 2019, irs.gov.
What to do
- Put backup withholding on line 2, and put line 3 in as well. A total alone is transcribed as pension withholding. The backup withholding unit reconciles line 2 to box 4 of your 1099s.
- One EIN, on every page, including Form 945-A. A second EIN anywhere makes the return unprocessable; a different one on the 945-A is silently overwritten.
- Sign where the form says, or adopt a facsimile properly. A printed or stamped officer name is accepted if the Rev. Proc. 2005-39 letter exists. Form 8879-EMP is not a paper signature.
- Use the current year's form. A prior-year form with no other date is edited to the current year.
- Keep the MeF rejection. Paper filed within ten days of a rejection, with the notice attached, keeps the rejection date as the received date.
- Answer Letter 21C by fax, completely. One letter lists every defect; the examiner makes one attempt for a signature. On a refund return, no answer means the credit is zeroed, not refunded.
- Do not file in December. Early returns are held to the new year's first cycles anyway.
Questions people ask
Our Form 945 shows only a total on line 3. Is that a problem?
Under the editing rule the total is moved to line 1 and processed as withholding on pensions and similar payments. The return posts, but line 2 shows zero backup withholding. If a Letter 6112 or compliance check later compares line 2 to 1099 box 4, the mismatch is yours to explain; a Form 945-X moving the amount between lines fixes the record.
The e-file rejected on January 31. Are we late?
Not if you resubmit electronically within ten days, or file on paper within ten days with the rejection notice attached and the return signed. Without the notice attached, the paper return's received date is whatever it is.
Can our payroll company sign our Form 945 electronically?
Only as a reporting agent with a Form 8655 on file, using its own 5-digit PIN, or as an ERO with your signed Form 8879-EMP. It may not use your 94x On-Line Signature PIN; the manual lists payroll companies among those who may not have access to it.
Does a stamped signature count?
Yes on Form 945, under Rev. Proc. 2005-39, if an officer has signed a letter adopting the facsimile and you keep it. The examiner accepts a printed, typed, stamped or computer-generated officer name in the signature area.