What CP210 and CP220 is
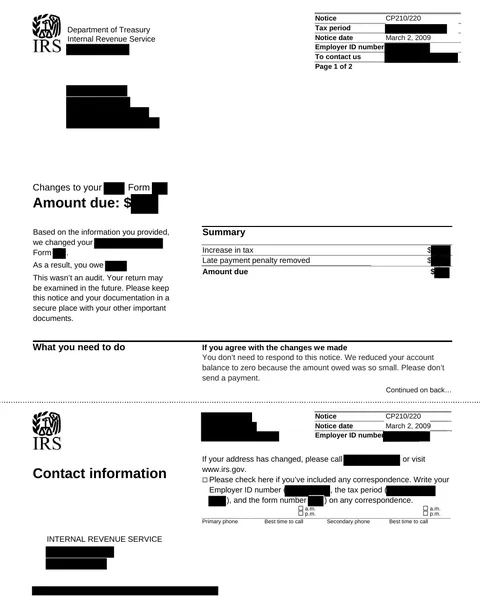
Notice CP210 (overpayment or zero balance) and Notice CP220 (balance due) are the IRS's business account adjustment notices; the manual writes them as CP 210 and CP 220. Both announce that the IRS changed a business account outside normal return processing. "A CP 210 ... notifies the taxpayer of an Examination or Data Processing tax adjustment notice, resulting in overpayment of $1.00 or more or a zero balance," and "A CP 220 ... is an adjustment notice from Exam or Data Processing, resulting in balance due, overpayment, or a even balance"; both are "also issued as a return settlement notice when penalties are assessed on overpaid modules" (IRM 21.3.1.7.29, 21.3.1.7.31)IRM 21.3.1.7.29Internal Revenue Manual, revised Oct. 3, 2022, irs.govIRM 21.3.1.7.31Internal Revenue Manual, revised Oct. 3, 2022, irs.gov. For a payer the common triggers are a Form 945 assessment from a Letter 6112 compliance check or a Form 4668-B examination report (TC 290 or 300 on the 945 module), Forms 4669 and 4670 relief posting as an abatement, and a credit transfer of a timely deposit onto the module, which "causes these penalties to recompute and generate an adjustment notice CP 210/CP 220" that the IRS "cannot suppress" (IRM 21.5.8.4.4)IRM 21.5.8.4.4Internal Revenue Manual, revised Mar. 14, 2024, irs.gov.
The deadline
A CP 220 with a balance due is a notice and demand: 21 calendar days to pay without additional interest. A CP 210 showing a credit means "a refund will be issued within two to three weeks if no other Federal taxes or obligations are owed."
What to do
Read which module and year the notice names and match it to the event: the compliance check letter, the examination report, the 945-X, or the credit transfer you requested. If the adjustment came from an examination you dispute, the assistor's script is audit reconsideration (IRM 21.5.10)IRM 21.5.10Internal Revenue Manual, irs.gov; if it did not come from an examination, "Ask taxpayer to send necessary documentation," by fax while on the call if possible (IRM 21.3.1.7.29)IRM 21.3.1.7.29Internal Revenue Manual, irs.gov. A CP 220 after an unanswered Letter 6112 is the assessment that letter warned of; the Forms 4669 and 4670 route still reduces it.
Questions about CP210 and CP220
Who receives CP210 and CP220?
Payers after a Form 945 compliance check or examination, after a credit transfer that recomputed penalties, or after any adjustment to a business module. Notice CP210 (overpayment or zero balance) and Notice CP220 (balance due) are the IRS's business account adjustment notices; the manual writes them as CP 210 and CP 220.
What is the deadline on CP210 and CP220?
A CP 220 with a balance due is a notice and demand: 21 calendar days to pay without additional interest. A CP 210 showing a credit means "a refund will be issued within two to three weeks if no other Federal taxes or obligations are owed."
What should I do when CP210 and CP220 arrives?
Read which module and year the notice names and match it to the event: the compliance check letter, the examination report, the 945-X, or the credit transfer you requested. If the adjustment came from an examination you dispute, the assistor's script is audit reconsideration (IRM 21.5.10)IRM 21.5.10Internal Revenue Manual, irs.gov; if it did not come from an examination, "Ask taxpayer to send necessary documentation," by fax while on the call if possible (IRM 21.3.1.7.29)IRM 21.3.1.7.29Internal Revenue Manual, irs.gov. A CP 220 after an unanswered Letter 6112 is the assessment that letter warned of; the Forms 4669 and 4670 route still reduces it.
Is CP210 and CP220 about my own income tax?
No. This decoder covers information reporting and withholding: the notices a payer, filer or payee sees because of Forms 1099, W-2, 945 and the TINs on them. Individual income-tax notices follow a different track.
Have a different notice? The IRS notice decoder lists all 90 in the order they tend to arrive.