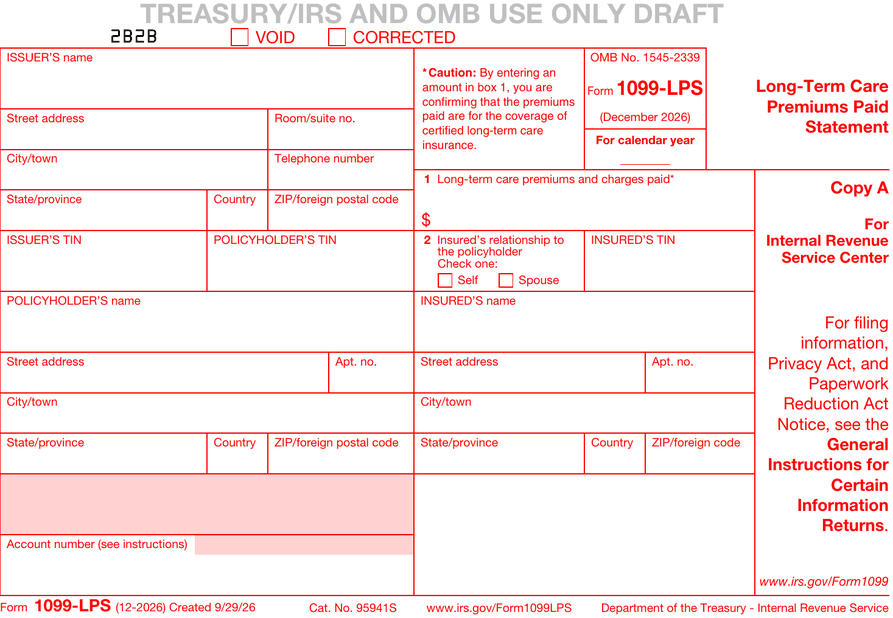
Who must file Form 1099-LPS
File Form 1099-LPS if you are an issuer of certified long-term care insurance and you filed a long-term care premium statement with a defined contribution plan because a policyholder asked to take a qualified long-term care distribution from that plan. If you filed no premium statement with a plan, you file no 1099-LPS.
A qualified long-term care distribution is a distribution from a 401(k) plan, 403(a) annuity, 403(b)(7) custodial account, 403(b)(11) plan or governmental 457(b) plan, made to pay for certified long-term care insurance for the employee or the employee's spouse. It is limited to the smallest of the premiums paid or assessed for the year, 10% of the employee's vested benefit, or an annual cap: $2,600 for 2026, indexed after that. No distribution qualifies unless the issuer has filed a premium statement with the plan, and before an issuer can do that it must file a disclosure with the IRS (Notice 2026-33, Q&A 1 to 3).
Certified long-term care insurance means a qualified long-term care insurance contract under IRC 7702B(b), a chronic-illness rider on a life insurance contract that meets IRC 101(g)(3), or a long-term care rider on an insurance or annuity contract treated as a separate contract under IRC 7702B(e) that meets 7702B(g). The coverage must provide meaningful financial help if the insured needs home-based or nursing home care.
Threshold: All amounts, no dollar threshold; filed for each policyholder for whom the issuer filed a long-term care premium statement with a defined contribution plan.
What is reported, box by box
| Box | What it reports | Notes |
|---|---|---|
| 1 | Long-term care premiums and charges paid | Premiums and charges paid for the certified coverage. Entering an amount confirms that the coverage is certified long-term care insurance. |
| 2 | Insured's relationship to the policyholder | Check Self if the policyholder (the employee) is the insured, or Spouse if the insured is the employee's spouse. Only those two are allowed. |
| Policyholder's and insured's names and TINs | The form carries both. The policyholder is the employee who owns the contract and asked for the premium statement; the insured is the person covered. | |
| Account number | Optional when you file only one form for the recipient; the IRS encourages one on every form. |
Box titles follow the current revision of the form. The IRS reads the payer and recipient name, TIN, address, account number and the money boxes; the state boxes are for the state copy only.
Payments that are not reported on Form 1099-LPS
- Policyholders for whom you did not file a long-term care premium statement with a defined contribution plan, even if they paid premiums for certified coverage.
- Premiums for anyone other than the employee or the employee's spouse.
- Coverage that is not certified long-term care insurance.
Due dates and extensions
| Copy | Due | For 2026 returns |
|---|---|---|
| To the IRS, paper | February 1 | February 1 |
| To the IRS, electronic | February 1 | February 1 |
| To the recipient | January 31 | Monday, February 1, 2027 (January 31 is a Sunday) |
An automatic 30-day extension is available on Form 8809, filed by the due date on paper or through IRIS; a second 30 days requires a hardship showing. Recipient statements can be extended 30 days on Form 15397, online or by fax only. 10 or more information returns of any type in aggregate must be e-filed (T.D. 9972); IRIS is the only IRS intake system from filing season 2027, FIRE having been retired. A payer who e-files the originals must e-file the corrections.
For 2026 forms filed in 2027: January 31 falls on a Sunday, so that deadline moves to Monday, February 1, 2027; February 28 also falls on a Sunday, so the paper deadline moves to Monday, March 1, 2027. March 31 (electronic) and March 15 are weekdays. February 28 does not become February 29 in a leap year. The compliance calendar has every date with the weekend shifts applied.
Withholding and TIN matching
Form 1099-LPS reports premiums the insurer received, not a payment to the policyholder, so backup withholding does not apply and the form is outside the IRS TIN Matching program. The policyholder's and the insured's TINs still have to be right: an incorrect or missing TIN carries the ordinary IRC 6721 and 6722 penalties. Payee statements may show a truncated TIN; the copy filed with the IRS may not.
Name and TIN errors on this form
Every information return is matched by the IRS on the first four characters of the payee's name (the name control) against the TIN. A mismatch produces a CP2100 line the following autumn and, unless the solicitation record is in order, a 972CG penalty the year after: $340 per return for 2026 forms filed in 2027 that are late or wrong, $690 for intentional disregard, with annual maximums of $4,191,500 ($1,397,000 for small filers) under Rev. Proc. 2025-32. The errors that recur on Form 1099-LPS:
- Two people, two TINs. When the insured is the spouse, the form carries the employee's TIN as policyholder and the spouse's as insured; each gets a statement.
- Statements to both. The policyholder gets Copy B and the insured Copy C; when they are the same person, Copy B alone is enough.
- Early statements. A policyholder or insured may ask for a statement before the normal furnishing date; Notice 2026-33 (Q&A 10 and 11) sets special timing for those requests.
The name control calculator shows what the IRS will derive from a name line, and the CP2100 guide covers what to do when the notice arrives.
Recipient statements and substitutes
The recipient statement for Form 1099-LPS need not be a copy of the official form: a substitute may be combined with other account statements or reports, provided every required item is numbered and titled as on the official form, the tax year, form number and form name appear together, the recipient instructions are included, and, for the forms Pub 1099 lists, a telephone number with direct access to someone who can answer questions is shown. Publication 1179 (Rev. Proc. 2026-18) has the specifications; logos, slogans and advertising are not permitted on the statement itself. Statements may be furnished electronically only to a recipient who has affirmatively consented in a way that shows they can access the format, after the disclosures in Pub 1099 part M, and must stay posted through October 15. Copy B may show a truncated TIN (xxx-xx-1234); the IRS copy never may.
Corrections and state copies
A wrong amount, code or checkbox is a Type 1 correction: one corrected return with the CORRECTED box checked. The wrong form type is a Type 2 correction: a zeroed-out copy of the original plus a new original, in that order. A wrong or missing payee TIN or name is also Type 2 on paper, but IRIS corrects it in one step on the original record (Publication 5717). Publication 1099 also says you are not required to file a correction for a missing or incorrect TIN if you meet the reasonable-cause standard, only to use the right TIN on the next return, although the IRS encourages the correction. Details and the paper error charts are on the 1099 corrections page.
Form 1099-LPS is not in the Combined Federal/State Filing program, so any state that requires it must receive it directly. Requirements by state are on the state pages.
Questions people ask about Form 1099-LPS
Is Form 1099-LPS final?
Not yet. The December 2026 form and its instructions are drafts; the IRS posted a revised draft of the form on October 2, 2026. Pub 1099 (2026) lists the form for tax year 2026, filing season 2027.
When is it due?
The Pub 1099 chart gives February 1 for the IRS and January 31 for the recipient. January 31, 2027 is a Sunday, so the recipient statement is due February 1, 2027 as well.
Do we file one for every long-term care policyholder?
No. Only for policyholders whose long-term care premium statement you filed with a defined contribution plan so they could take a qualified long-term care distribution.
How is it filed?
Through IRIS, like every other information return from tax year 2026; FIRE is retired. Paper filing is limited to filers under the 10-return e-file threshold.
Other federal forms
1042-S · 1097-BTC · 1098 · 1098-C · 1098-E · 1098-F · 1098-Q · 1098-T · 1098-VLI · 1099-A · 1099-B · 1099-C · 1099-CAP · 1099-DIV · 1099-G · 1099-INT · 1099-K · 1099-LS · 1099-LTC · 1099-MISC · 1099-NEC · 1099-OID · 1099-PATR · 1099-Q · 1099-QA · 1099-R · 1099-S · 1099-SA · 1099-SB · 3921 · 3922 · 5498 · 5498-ESA · 5498-SA · W-2G · 1099-DA · Comparison table
Sources: IRS Publication 1099 (2026), General Instructions for Certain Information Returns, which replaced the separate General Instructions starting with tax year 2026; Draft Form 1099-LPS (Dec. 2026, posted Oct. 2, 2026); draft Instructions for Form 1099-LPS (Dec. 2026); Pub 1099 (2026); Notice 2026-33. Threshold amounts are indexed for inflation from calendar year 2027; check IRS.gov/InflationAdjustment for the current year.