Who must file Form 5498-QA
Any state, or its agency or instrumentality, that establishes and maintains a qualified ABLE program files Form 5498-QA with the IRS for each ABLE account by May 31 of the following year, and furnishes a statement to the designated beneficiary by March 15. An officer or employee with control of the program, or their designee, may file. The form is required for every account, not only those with contributions: if nothing was contributed during the year, box 1 shows zero and the form still reports the year-end value and the eligibility codes. Distributions from the account are reported separately on Form 1099-QA.
An ABLE account belongs to an eligible individual, who is both the owner and the designated beneficiary. From tax years beginning after December 31, 2025, an individual is eligible if their blindness or disability began before age 46, up from 26. A beneficiary can have only one ABLE account.
The form and instructions became continuous use with the December 2026 revision, which also split the address fields into separate boxes. Because so few paper forms are filed, the IRS offers it as an online fillable form; a program filing 10 or more information returns in total must file electronically. Form 5498-QA has no Pub 1220 layout, so it cannot go through FIRE; IRIS carries it (the tax year 2026 schema includes the Trump account rollover field).
Threshold: All amounts, every ABLE account, every year, including years with no contributions (box 1 shows zero).
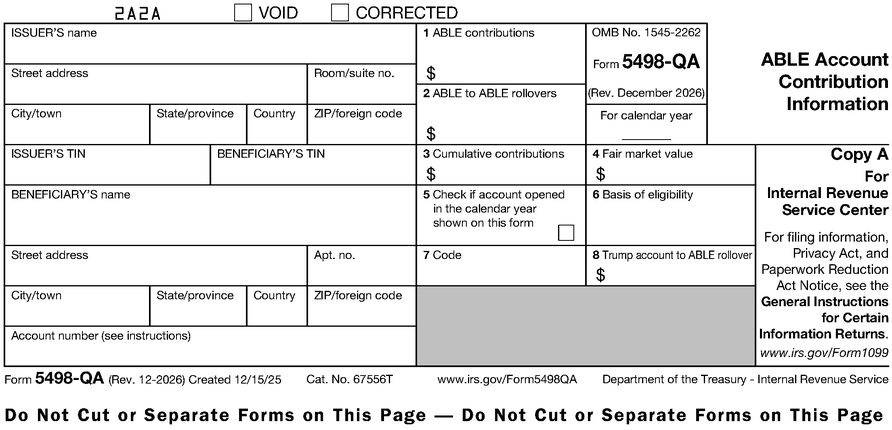
What is reported, box by box
| Box | What it reports | Notes |
|---|---|---|
| 1 | ABLE contributions | All cash contributions for the calendar year, including rollovers and program-to-program transfers from a section 529 qualified tuition program. Leave out excess contributions returned by the beneficiary's return due date and rollovers from other ABLE accounts. Enter zero if nothing was contributed. |
| 2 | ABLE to ABLE rollovers | Rollovers and program-to-program transfers into this account from another ABLE account during the year. Section 529 amounts go in box 1, not here. |
| 3 | Cumulative contributions | Optional: total contributions since the account was established, including those to an earlier ABLE account of the same beneficiary that was rolled over or transferred into this one. |
| 4 | Fair market value | As of December 31. |
| 5 | Account opened in the calendar year | Checkbox. |
| 6 | Basis of eligibility | Required, one code: A, SSDI (Title II); B, SSI (Title XVI); C, a disability certification filed with the IRS in the current year. |
| 7 | Type of disability code | One primary code, 1 to 7 (developmental, intellectual, psychiatric, nervous, congenital, respiratory, other). Used only for aggregate reporting. |
| 8 | Trump account to ABLE rollover | New for 2026: a qualified ABLE rollover contribution of the entire balance of the beneficiary's Trump account, transferred trustee to trustee in the calendar year the beneficiary turns 17. |
| Issuer's and beneficiary's name, TIN and address; account number | The IRS encourages an account number on every form. The beneficiary's TIN may be truncated on the statement, never on the IRS copy; the issuer's TIN is never truncated. |
Box titles follow the current revision of the form. The IRS reads the payer and recipient name, TIN, address, account number and the money boxes; the state boxes are for the state copy only.
Payments that are not reported on Form 5498-QA
- Distributions, terminations and returned excess contributions, which are reported on Form 1099-QA.
- A change of designated beneficiary to an eligible family member, which is not a contribution.
Due dates and extensions
| Copy | Due | For 2026 returns |
|---|---|---|
| To the IRS, paper | May 31 | Tuesday, June 1, 2027 (May 31 is Memorial Day) |
| To the IRS, electronic | May 31 | Tuesday, June 1, 2027 (May 31 is Memorial Day) |
| To the recipient | March 15 | Monday, March 15, 2027 |
An automatic 30-day extension is available on Form 8809, filed by the due date on paper or through IRIS; a second 30 days requires a hardship showing. Recipient statements can be extended 30 days on Form 15397, online or by fax only. 10 or more information returns of any type in aggregate must be e-filed (T.D. 9972); IRIS is the only IRS intake system from filing season 2027, FIRE having been retired. A payer who e-files the originals must e-file the corrections.
For 2026 forms filed in 2027: January 31 falls on a Sunday, so that deadline moves to Monday, February 1, 2027; February 28 also falls on a Sunday, so the paper deadline moves to Monday, March 1, 2027. March 31 (electronic) and March 15 are weekdays. February 28 does not become February 29 in a leap year. The compliance calendar has every date with the weekend shifts applied.
Withholding and TIN matching
Contributions are not payments to the beneficiary, so backup withholding does not apply and the form is outside the IRS TIN Matching program. Failures are penalized under IRC 6693 at $50 per return, not under the IRC 6721 tiers. The beneficiary's SSN is established when the account is opened under the eligibility rules, so mismatches usually come from a parent, guardian or other authorized person being recorded as the account holder.
Name and TIN errors on this form
Every information return is matched by the IRS on the first four characters of the payee's name (the name control) against the TIN. For this form the penalty is IRC 6693: $50 per return for each failure to file or furnish, with no annual maximum, unless the failure was due to reasonable cause. A mismatch still produces a CP2100 line the following autumn. The errors that recur on Form 5498-QA:
- The beneficiary is the owner. The form goes under the designated beneficiary's name and SSN, even when a parent, guardian or representative opened and manages the account.
- Rollovers keep the same person. A rollover or transfer from another ABLE account or a Trump account is for the same beneficiary (or an eligible family member); check that the TIN carried over with the money.
- Truncation is for the statement only. The copy furnished to the beneficiary may show the last four digits; the IRS copy carries the full TIN.
The name control calculator shows what the IRS will derive from a name line, and the CP2100 guide covers what to do when the notice arrives.
Recipient statements and substitutes
The recipient statement for Form 5498-QA need not be a copy of the official form: a substitute may be combined with other account statements or reports, provided every required item is numbered and titled as on the official form, the tax year, form number and form name appear together, the recipient instructions are included, and, for the forms Pub 1099 lists, a telephone number with direct access to someone who can answer questions is shown. Publication 1179 (Rev. Proc. 2026-18) has the specifications; logos, slogans and advertising are not permitted on the statement itself. Statements may be furnished electronically only to a recipient who has affirmatively consented in a way that shows they can access the format, after the disclosures in Pub 1099 part M, and must stay posted through October 15. Copy B may show a truncated TIN (xxx-xx-1234); the IRS copy never may.
Corrections and state copies
A wrong amount, code or checkbox is a Type 1 correction: one corrected return with the CORRECTED box checked. The wrong form type is a Type 2 correction: a zeroed-out copy of the original plus a new original, in that order. A wrong or missing payee TIN or name is also Type 2 on paper, but IRIS corrects it in one step on the original record (Publication 5717). Publication 1099 also says you are not required to file a correction for a missing or incorrect TIN if you meet the reasonable-cause standard, only to use the right TIN on the next return, although the IRS encourages the correction. Details and the paper error charts are on the 1099 corrections page.
Form 5498-QA is not in the Combined Federal/State Filing program, so any state that requires it must receive it directly. Requirements by state are on the state pages.
Questions people ask about Form 5498-QA
When is Form 5498-QA due?
To the IRS by May 31 of the following year, and to the beneficiary by March 15. For 2026 accounts that means March 15 and May 31, 2027.
Do we file when nothing was contributed?
Yes. The form is filed for every ABLE account; box 1 shows zero and the form still reports the year-end value and the eligibility codes.
What is new for 2026?
Box 8 for a rollover from the beneficiary's Trump account, the age limit for eligibility rising from 26 to 46, separate address boxes, and a switch to a continuous-use form and instructions.
Where does a 529 to ABLE rollover go?
Box 1, as a contribution. Box 2 is only for rollovers and transfers from another ABLE account.
Which penalty applies?
$50 per return under IRC 6693, with no annual maximum.
Other federal forms
1042-S · 1097-BTC · 1098 · 1098-C · 1098-E · 1098-F · 1098-Q · 1098-T · 1098-VLI · 1099-A · 1099-B · 1099-C · 1099-CAP · 1099-DIV · 1099-G · 1099-INT · 1099-K · 1099-LPS · 1099-LS · 1099-LTC · 1099-MISC · 1099-NEC · 1099-OID · 1099-PATR · 1099-Q · 1099-QA · 1099-R · 1099-S · 1099-SA · 1099-SB · 3921 · 3922 · 5498 · 5498-ESA · 5498-SA · 5498-TA · W-2G · 1099-DA · Comparison table
Sources: IRS Publication 1099 (2026), General Instructions for Certain Information Returns, which replaced the separate General Instructions starting with tax year 2026; Form 5498-QA (Rev. December 2026); Instructions for Forms 1099-QA and 5498-QA (Rev. December 2026); Pub 1099 (2026), Guide to Information Returns; IRIS A2A schema, tax year 2026 v1.2 (Form 5498-QA); IRC 529A, 6693. Threshold amounts are indexed for inflation from calendar year 2027; check IRS.gov/InflationAdjustment for the current year.