Every form on one table
| Form | Threshold or who files | Due to IRSpaper / e-file | To recipient | Backup withholding | IRS TIN Matching | CF/SF |
|---|---|---|---|---|---|---|
| 1099 series | ||||||
| 1099-A Acquisition or Abandonment of Secured Property | All amounts | February 28 / March 31 | January 31 | No | No | No |
| 1099-B Proceeds From Broker and Barter Exchange Transactions | All amounts | February 28 / March 31 | February 15 | Yes | Yes | Yes |
| 1099-C Cancellation of Debt | $600 | February 28 / March 31 | January 31 | No | No | No |
| 1099-CAP Changes in Corporate Control and Capital Structure | Over $1,000 | February 28 / March 31 | January 31 | No | No | No |
| 1099-DA Digital Asset Proceeds From Broker Transactions | All amounts | February 28 / March 31 | February 15 | Yes | Yes | No |
| 1099-DIV Dividends and Distributions | $10 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-G Certain Government Payments | $10 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-INT Interest Income | $10 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-K Payment Card and Third Party Network Transactions | $20,000 / 200 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-LPS Long-Term Care Premiums Paid Statement | All amounts | February 1 | January 31 | No | No | No |
| 1099-LS Reportable Life Insurance Sale | All amounts | February 28 / March 31 | February 15 | No | No | No |
| 1099-LTC Long-Term Care and Accelerated Death Benefits | All amounts | February 28 / March 31 | January 31 | No | No | No |
| 1099-MISC Miscellaneous Information | $2,000 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-NEC Nonemployee Compensation | $2,000 | January 31 | January 31 | Yes | Yes | Yes |
| 1099-OID Original Issue Discount | $10 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-PATR Taxable Distributions Received From Cooperatives | $10 | February 28 / March 31 | January 31 | Yes | Yes | Yes |
| 1099-Q Payments From Qualified Education Programs | All amounts | February 28 / March 31 | January 31 | No | No | No |
| 1099-QA Distributions From ABLE Accounts | All amounts | February 28 | January 31 | No | No | No |
| 1099-R Distributions From Pensions, Annuities, Retirement Plans, IRAs, Insurance Contracts | $10 | February 28 / March 31 | January 31 | No | No | Yes |
| 1099-S Proceeds From Real Estate Transactions | Generally $600 | February 28 / March 31 | February 15 | No | No | No |
| 1099-SA Distributions From an HSA, Archer MSA, or Medicare Advantage MSA | All amounts | February 28 / March 31 | January 31 | No | No | No |
| 1099-SB Seller's Investment in Life Insurance Contract | All amounts | February 28 / March 31 | February 15 | No | No | No |
| 1098 series and 1097-BTC | ||||||
| 1097-BTC Bond Tax Credit | $10 | February 28 / March 31 | Quarterly | No | No | No |
| 1098 Mortgage Interest Statement | $600 | February 28 / March 31 | January 31 | No | No | No |
| 1098-C Contributions of Motor Vehicles, Boats, and Airplanes | Over $500 | February 28 / March 31 | 30 days from sale or contribution | No | No | No |
| 1098-E Student Loan Interest Statement | $600 | February 28 / March 31 | January 31 | No | No | No |
| 1098-F Fines, Penalties, and Other Amounts | $50,000 | February 28 / March 31 | January 31 | No | No | No |
| 1098-Q Qualifying Longevity Annuity Contract Information | All amounts | February 28 | January 31 | No | No | No |
| 1098-T Tuition Statement | All amounts | February 28 / March 31 | January 31 | No | No | No |
| 1098-VLI Vehicle Loan Interest Statement | $600 | February 28 / March 31 | January 31 | No | No | No |
| 5498 series | ||||||
| 5498 IRA Contribution Information | All amounts | May 31 | January 31 / May 31 | No | No | No |
| 5498-ESA Coverdell ESA Contribution Information | All amounts | May 31 | April 30 | No | No | No |
| 5498-QA ABLE Account Contribution Information | All amounts | May 31 | March 15 | No | No | No |
| 5498-SA HSA, Archer MSA, or Medicare Advantage MSA Information | All amounts | May 31 | May 31 | No | No | No |
| 5498-TA Trump Account Contribution Information | All amounts | Not yet set | May 31 | No | No | No |
| Other information returns: 1042-S, 3921, 3922, W-2G | ||||||
| 1042-S Foreign Person's U.S. Source Income Subject to Withholding | All amounts | March 15 | March 15 | No | No | No |
| 3921 Exercise of an Incentive Stock Option Under Section 422(b) | All amounts | February 28 / March 31 | January 31 | No | No | No |
| 3922 Transfer of Stock Acquired Through an Employee Stock Purchase Plan Under Section 423(c) | All amounts | February 28 / March 31 | January 31 | No | No | No |
| W-2G Certain Gambling Winnings | $2,000 | February 28 / March 31 | January 31 | Yes | No | No |
| Certifications collected from payees | ||||||
| W-9 Request for Taxpayer Identification Number and Certification | Certification: U.S. persons | Not filed; kept by the requester | Valid: no expiry | Without it: 24% backup withholding | n/a | n/a |
| W-9S Request for Student's or Borrower's Taxpayer Identification Number and Certification | Certification: Students and student-loan borrowers | Not filed; kept by the requester | Valid: no expiry | Without it: None; filer may be excused for missing TIN | n/a | n/a |
| W-8BEN Certificate of Foreign Status of Beneficial Owner | Certification: Foreign individuals | Not filed; kept by the requester | Valid: 3 years | Without it: 30%, or presumed U.S. | n/a | n/a |
| W-8BEN-E Certificate of Status of Beneficial Owner | Certification: Foreign entities | Not filed; kept by the requester | Valid: 3 years | Without it: 30% chapter 3 or 4, or presumed U.S. | n/a | n/a |
| W-8ECI Certificate of Foreign Person's Claim That Income Is Effectively Connected With the Conduct of a Trade or Business in the United States | Certification: Foreign persons with U.S. business income | Not filed; kept by the requester | Valid: 3 years | Without it: 30% on gross | n/a | n/a |
| W-8EXP Certificate of Foreign Government or Other Foreign Organization | Certification: Foreign governments, int'l organizations, foreign charities | Not filed; kept by the requester | Valid: indefinite | Without it: 30% (4% private foundations) | n/a | n/a |
| W-8IMY Certificate of Foreign Intermediary, Foreign Flow-Through Entity, or Certain U.S. Branches | Certification: Foreign intermediaries and flow-throughs | Not filed; kept by the requester | Valid: indefinite | Without it: Presumption rules, payee by payee | n/a | n/a |
| 8233 Exemption From Withholding on Compensation for Independent | Certification: Nonresident aliens paid for U.S. services, claiming a treaty | Agent sends a copy to the IRS within 5 days | Valid: one tax year | Without it: 30%, or wage withholding | n/a | n/a |
| Payroll returns | ||||||
| W-4 Employee's Withholding Certificate | Every new employee | Not filed; kept by the employer / Not filed | n/a | n/a | n/a | n/a |
| 941 Employer's Quarterly Federal Tax Return | Any employer paying wages (unless on 944 or 943) | Apr 30, Jul 31, Oct 31, Jan 31 | n/a | n/a | n/a | n/a |
| 941-X Adjusted Employer's Quarterly Federal Tax Return or Claim for Refund | When a filed 941 was wrong | Due date of the 941 for the quarter the error was found | n/a | n/a | n/a | n/a |
| 944 Employer's Annual Federal Tax Return | Employers the IRS notifies to file annually | January 31 | n/a | n/a | n/a | n/a |
| 943 Employer's Annual Federal Tax Return for Agricultural Employees | Employers of farmworkers | January 31 | n/a | n/a | n/a | n/a |
| 940 Employer's Annual Federal Unemployment (FUTA) Tax Return | $1,500 of wages in a quarter, or an employee in 20 weeks | January 31 | n/a | n/a | n/a | n/a |
| W-2 Wage and Tax Statement | Wages paid to employees | January 31 (to SSA) | January 31 | n/a | n/a | n/a |
| W-3 Transmittal of Wage and Tax Statements | With paper W-2s | January 31 (to SSA) / Not used | n/a | n/a | n/a | n/a |
| W-2c Corrected Wage and Tax Statement | When a filed W-2 was wrong | As soon as possible (to SSA) | As soon as possible | n/a | n/a | n/a |
| 8027 Employer's Annual Information Return of Tip Income and Allocated Tips | Large food or beverage establishments | February 28 / March 31 | n/a | n/a | n/a | n/a |
| Withholding returns | ||||||
| 945 Annual Return of Withheld Federal Income Tax | Any nonpayroll federal income tax withholding | January 31 | n/a | n/a | n/a | n/a |
| 1042 Annual Withholding Tax Return for U.S. Source Income of Foreign Persons | Withholding agents paying foreign persons | March 15 | n/a (1042-S by March 15) | n/a | n/a | n/a |
| Health coverage (ACA) returns | ||||||
| 1095-C Employer-Provided Health Insurance Offer and Coverage | Applicable large employers (50 or more full-time employees) | February 28 / March 31 (AIR) | March 2 for 2026 | n/a | n/a | n/a |
| 1094-C Transmittal of Employer-Provided Health Insurance Offer and Coverage Information Returns | Transmittal for Forms 1095-C | February 28 / March 31 (AIR) | n/a | n/a | n/a | n/a |
| 1095-B Health Coverage | Providers of minimum essential coverage | February 28 / March 31 (AIR) | March 2 for 2026 | n/a | n/a | n/a |
| 1094-B Transmittal of Health Coverage Information Returns | Transmittal for Forms 1095-B | February 28 / March 31 (AIR) | n/a | n/a | n/a | n/a |
| Paper transmittal | ||||||
| 1096 Annual Summary and Transmittal of U.S. Information Returns | Paper filers of 1099, 1098, 5498, W-2G | With the paper forms' due date / Not used | n/a | n/a | n/a | n/a |
Due dates move to the next business day when they fall on a weekend or legal holiday. For 2026 forms filed in 2027: January 31 falls on a Sunday, so that deadline moves to Monday, February 1, 2027; February 28 also falls on a Sunday, so the paper deadline moves to Monday, March 1, 2027. March 31 (electronic) and March 15 are weekdays. February 28 does not become February 29 in a leap year. Click a column heading to sort; sorting drops the group headings.
Information returns
Returns a payer files with the IRS to report a payment to someone else, with a copy to the recipient. The IRS matches the name and TIN on each one, which is where CP2100 lines and 972CG penalties come from. E-filed originals and corrections go through IRIS from 2027.
1099 series
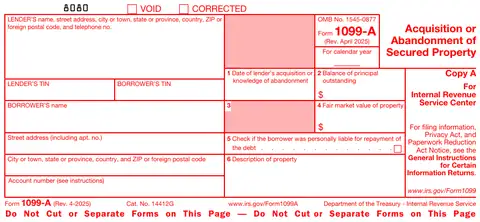
Form 1099-A
Acquisition or Abandonment of Secured Property. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
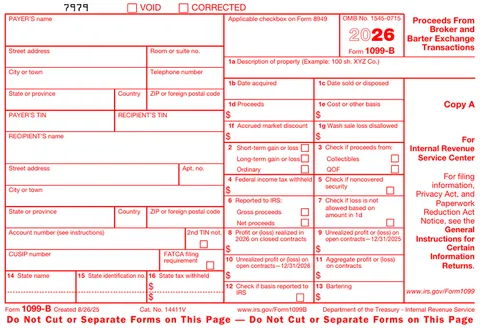
Form 1099-B
Proceeds From Broker and Barter Exchange Transactions. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient February 15.
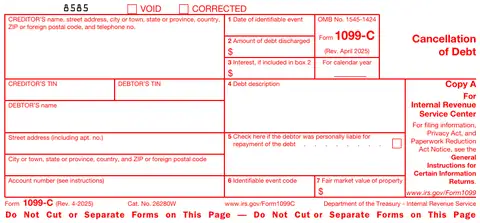
Form 1099-C
Cancellation of Debt. $600 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
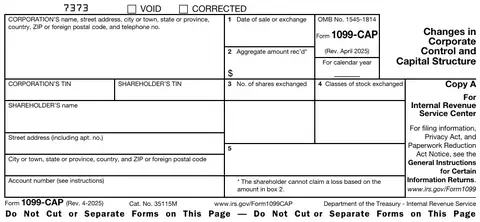
Form 1099-CAP
Changes in Corporate Control and Capital Structure. Over $1,000 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
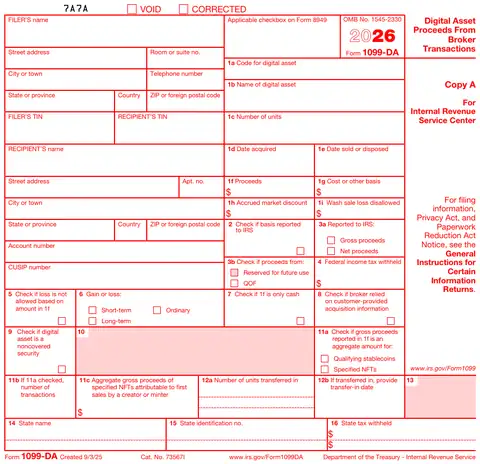
Form 1099-DA
Digital Asset Proceeds From Broker Transactions. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient February 15.
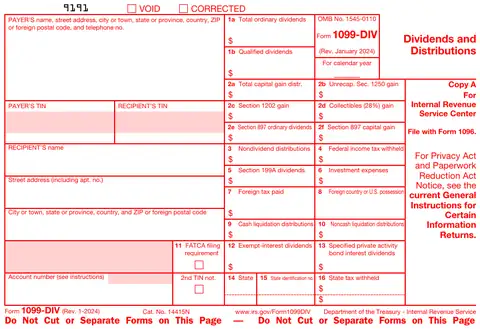
Form 1099-DIV
Dividends and Distributions. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
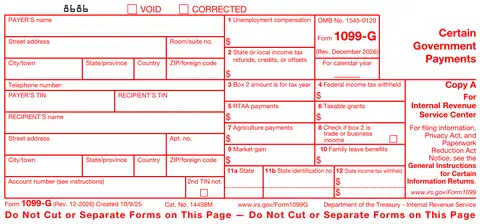
Form 1099-G
Certain Government Payments. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
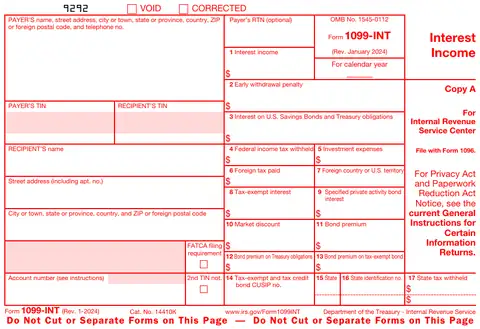
Form 1099-INT
Interest Income. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
Form 1099-K
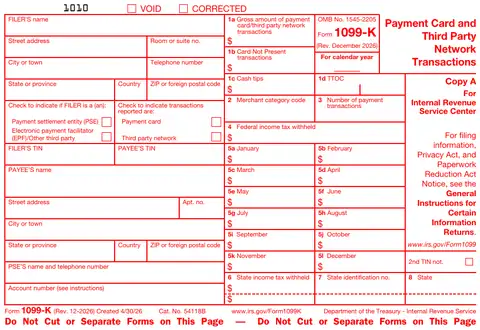
Payment Card and Third Party Network Transactions. $20,000 / 200 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
Form 1099-LPS
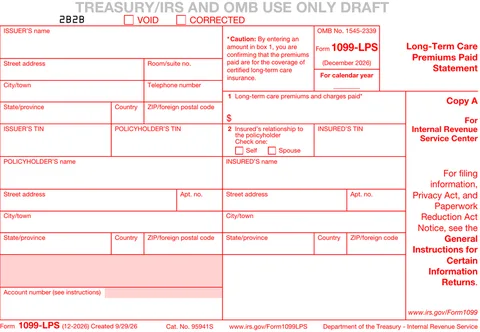
Long-Term Care Premiums Paid Statement. All amounts threshold; IRS February 1; recipient January 31.
Form 1099-LS
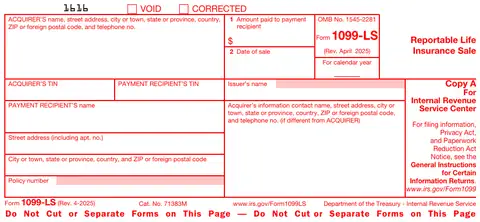
Reportable Life Insurance Sale. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient February 15.
Form 1099-LTC
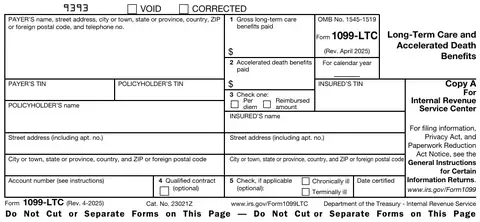
Long-Term Care and Accelerated Death Benefits. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
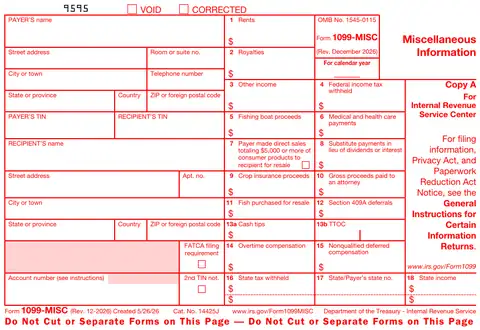
Form 1099-MISC
Miscellaneous Information. $2,000 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
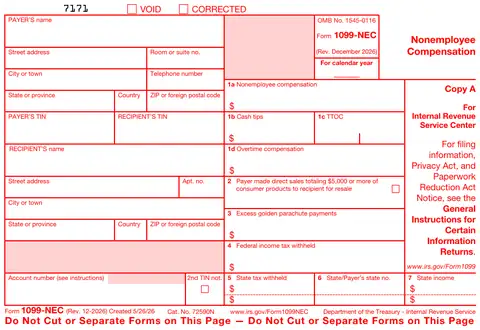
Form 1099-NEC
Nonemployee Compensation. $2,000 threshold; IRS January 31; recipient January 31.
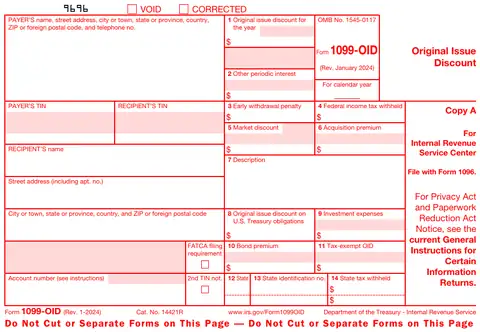
Form 1099-OID
Original Issue Discount. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
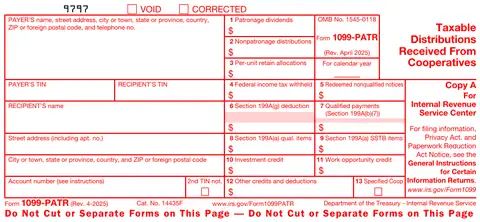
Form 1099-PATR
Taxable Distributions Received From Cooperatives. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
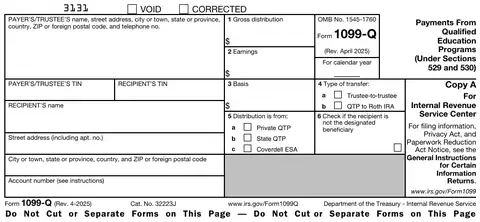
Form 1099-Q
Payments From Qualified Education Programs. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
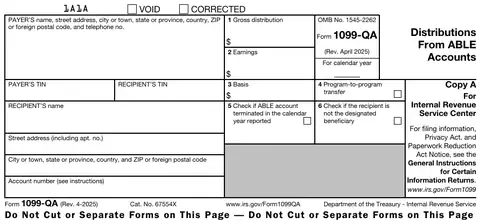
Form 1099-QA
Distributions From ABLE Accounts. All amounts threshold; IRS February 28; recipient January 31.
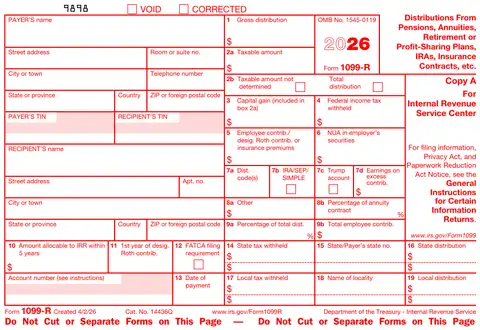
Form 1099-R
Distributions From Pensions, Annuities, Retirement Plans, IRAs, Insurance Contracts. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
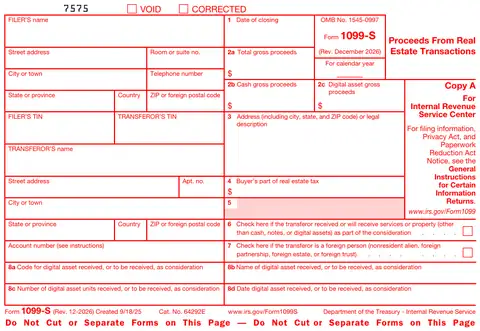
Form 1099-S
Proceeds From Real Estate Transactions. Generally $600 threshold; IRS February 28 (paper) / March 31 (e-file); recipient February 15.
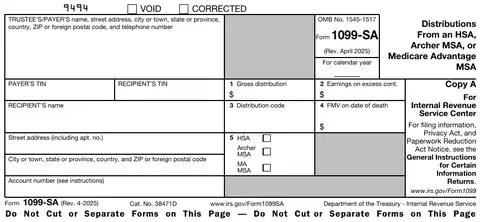
Form 1099-SA
Distributions From an HSA, Archer MSA, or Medicare Advantage MSA. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
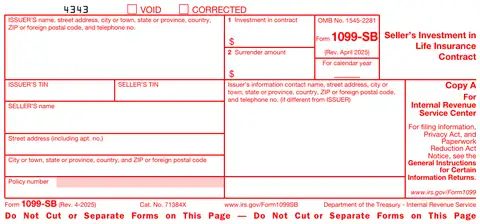
Form 1099-SB
Seller's Investment in Life Insurance Contract. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient February 15.
1098 series and 1097-BTC
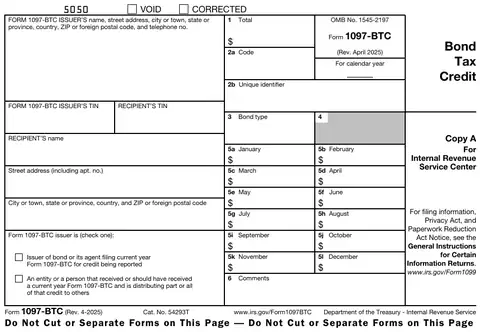
Form 1097-BTC
Bond Tax Credit. $10 threshold; IRS February 28 (paper) / March 31 (e-file); recipient Quarterly.
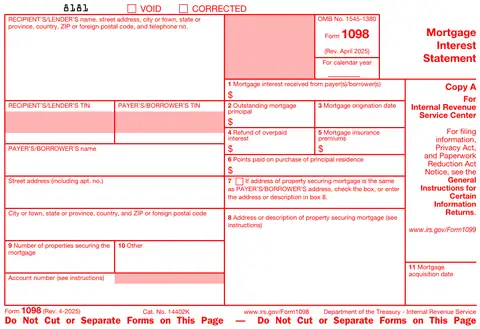
Form 1098
Mortgage Interest Statement. $600 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
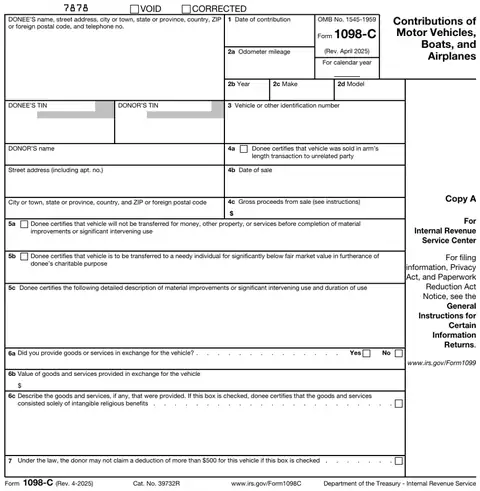
Form 1098-C
Contributions of Motor Vehicles, Boats, and Airplanes. Over $500 threshold; IRS February 28 (paper) / March 31 (e-file); recipient 30 days from sale or contribution.
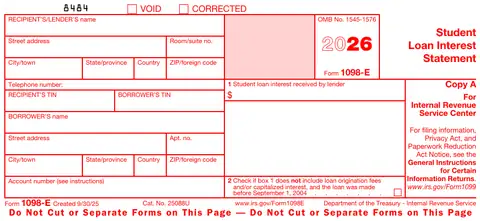
Form 1098-E
Student Loan Interest Statement. $600 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
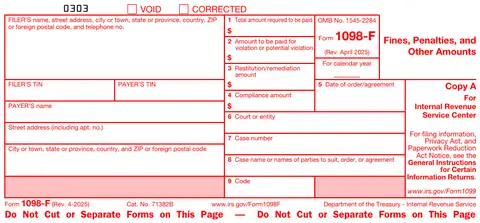
Form 1098-F
Fines, Penalties, and Other Amounts. $50,000 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
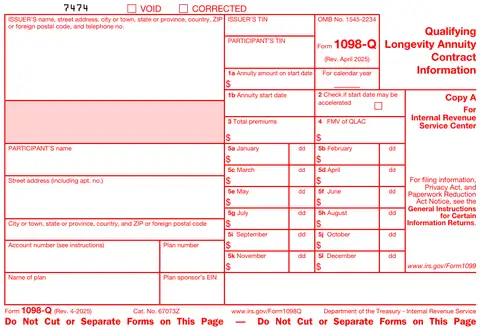
Form 1098-Q
Qualifying Longevity Annuity Contract Information. All amounts threshold; IRS February 28; recipient January 31.
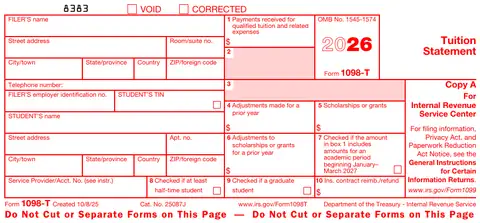
Form 1098-T
Tuition Statement. All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
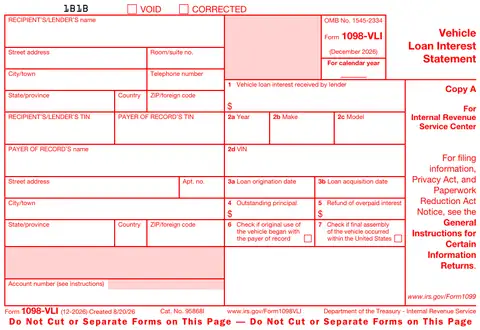
Form 1098-VLI
Vehicle Loan Interest Statement. $600 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
5498 series
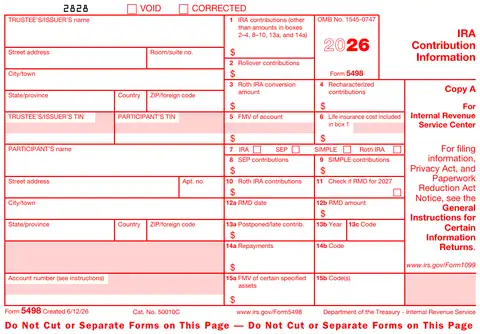
Form 5498
IRA Contribution Information. All amounts threshold; IRS May 31; recipient January 31 / May 31.
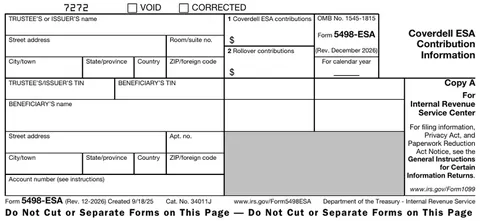
Form 5498-ESA
Coverdell ESA Contribution Information. All amounts threshold; IRS May 31; recipient April 30.
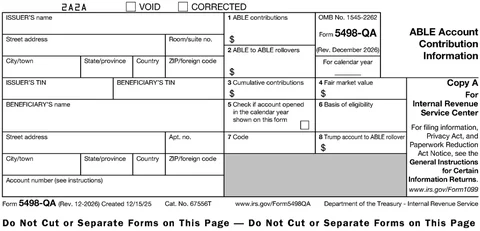
Form 5498-QA
ABLE Account Contribution Information. All amounts threshold; IRS May 31; recipient March 15.
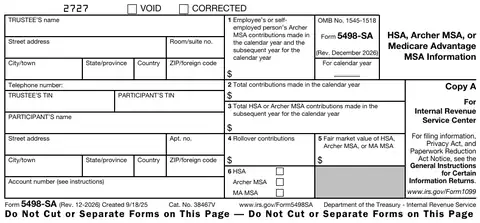
Form 5498-SA
HSA, Archer MSA, or Medicare Advantage MSA Information. All amounts threshold; IRS May 31; recipient May 31.
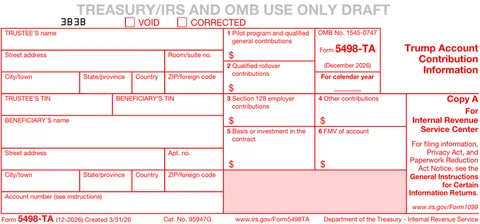
Form 5498-TA
Trump Account Contribution Information. All amounts threshold; IRS Not yet set; recipient May 31.
1042-S, 3921, 3922 and W-2G
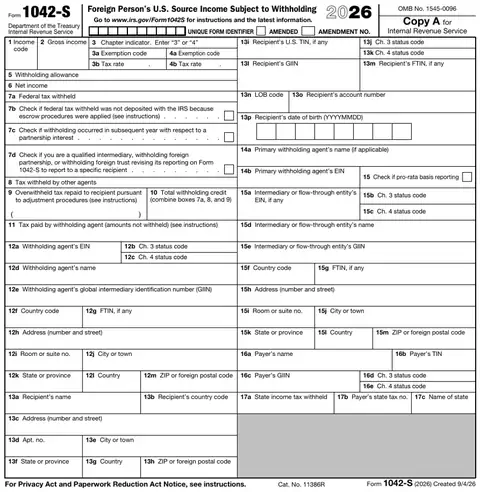
Form 1042-S
Foreign Person's U.S. Source Income Subject to Withholding. All amounts threshold; IRS March 15; recipient March 15.
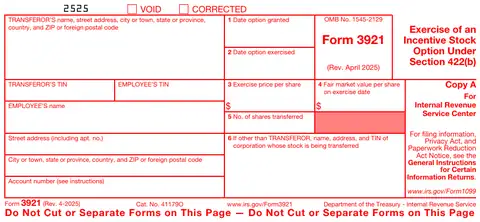
Form 3921
Exercise of an Incentive Stock Option Under Section 422(b). All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
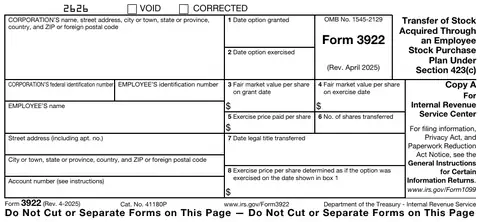
Form 3922
Transfer of Stock Acquired Through an Employee Stock Purchase Plan Under Section 423(c). All amounts threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
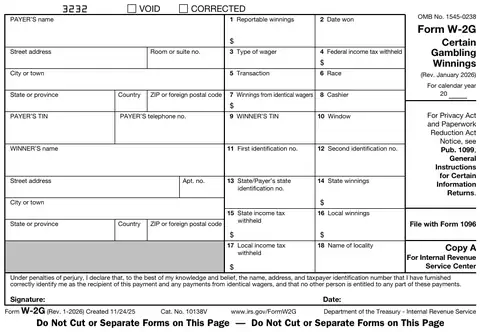
Form W-2G
Certain Gambling Winnings. $2,000 threshold; IRS February 28 (paper) / March 31 (e-file); recipient January 31.
Certifications: the W-9, the W-8 series and Form 8233
The other half of the system: the certifications a payee gives the payer, which the payer keeps and relies on to decide whether to file a 1099 or a 1042-S, whether to withhold, and at what rate. Only Form 8233 reaches the IRS: the withholding agent sends a copy after accepting it.
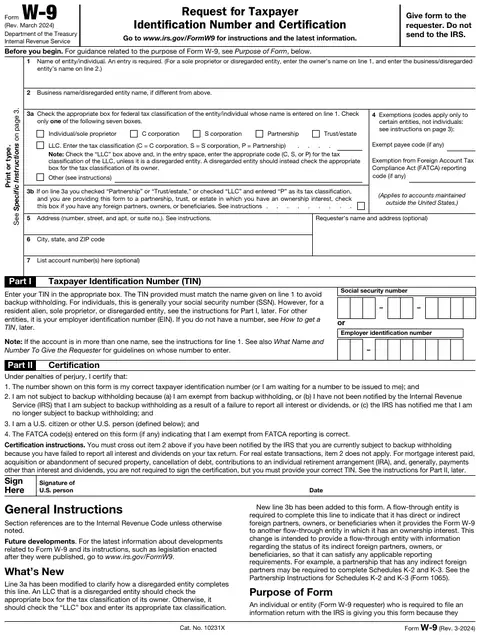
Form W-9
U.S. persons. TIN, U.S. status, backup withholding status. Valid: no expiry.
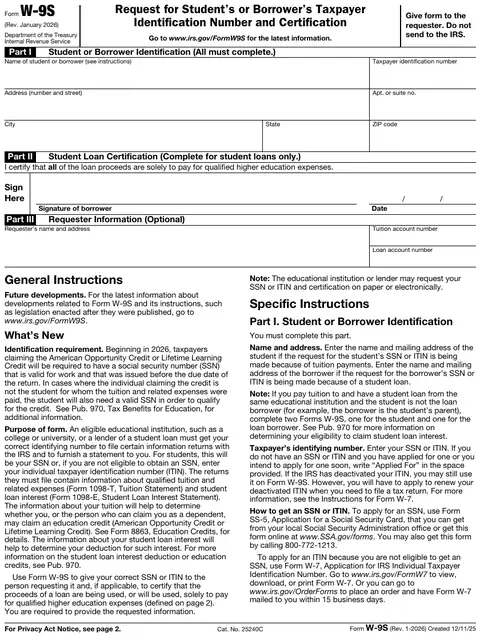
Form W-9S
Students and student-loan borrowers. Name, TIN, qualified-expense certification. Valid: no expiry.
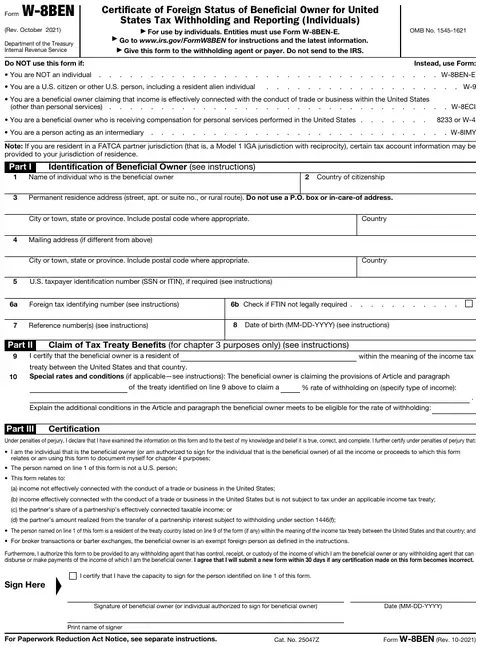
Form W-8BEN
Foreign individuals. Foreign status, treaty claim. Valid: 3 years.
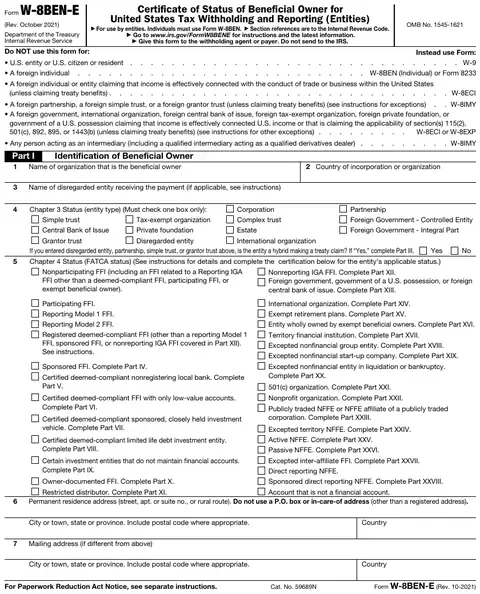
Form W-8BEN-E
Foreign entities. Foreign status, chapter 3 and 4 status, treaty claim. Valid: 3 years.
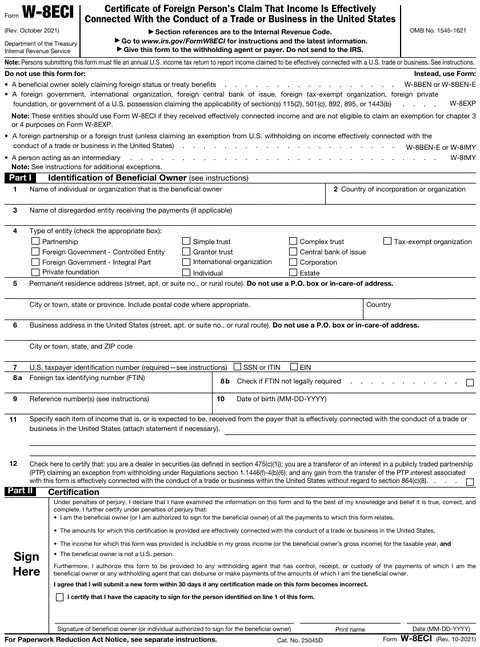
Form W-8ECI
Foreign persons with U.S. business income. Income is effectively connected; U.S. TIN. Valid: 3 years.
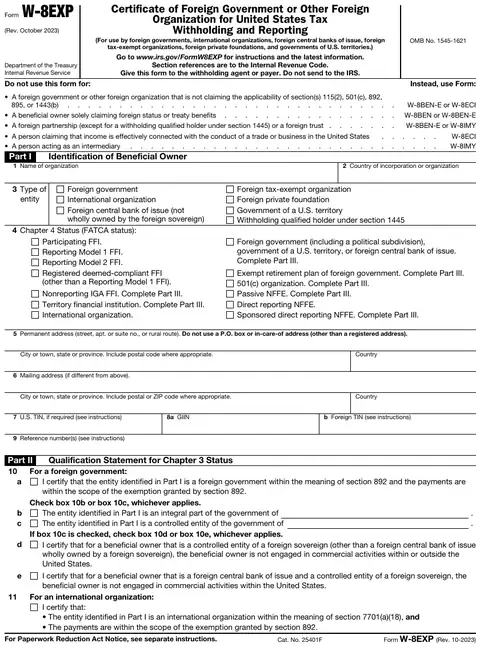
Form W-8EXP
Foreign governments, int'l organizations, foreign charities. Statutory exemption claimed. Valid: indefinite.
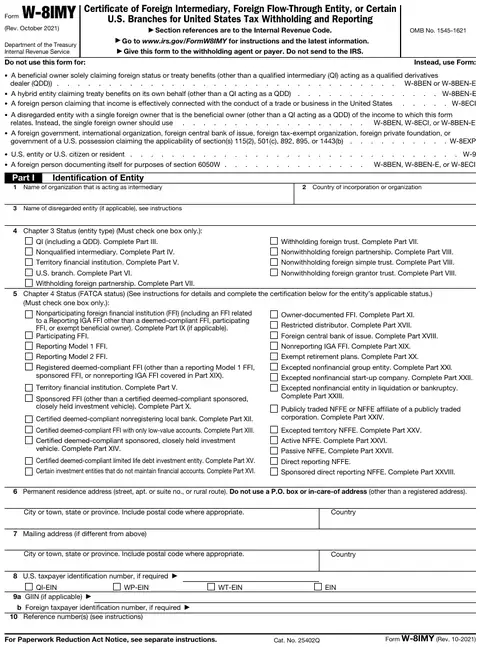
Form W-8IMY
Foreign intermediaries and flow-throughs. Role, withholding responsibility, underlying payees. Valid: indefinite.
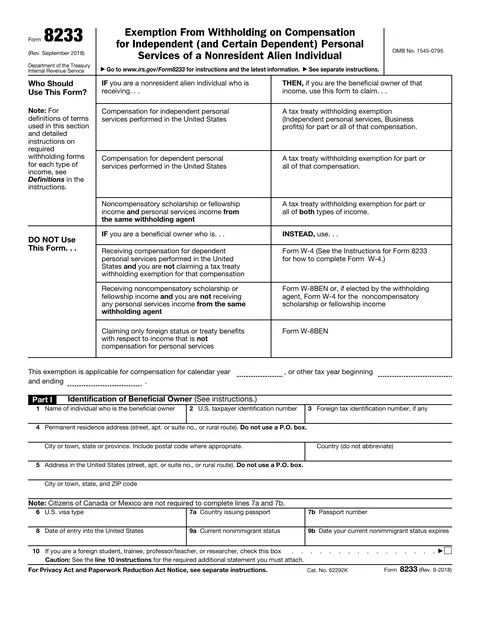
Form 8233
Nonresident aliens paid for U.S. services, claiming a treaty. Treaty exemption for services pay, U.S. TIN, visa details. Valid: one tax year.
Payroll returns
The returns an employer files about wages: the quarterly or annual employment tax return and its correction, the FUTA return, Forms W-2 and W-3 filed with the Social Security Administration and their corrections, the W-4 each employee gives you, and the tip return for large food and beverage establishments.
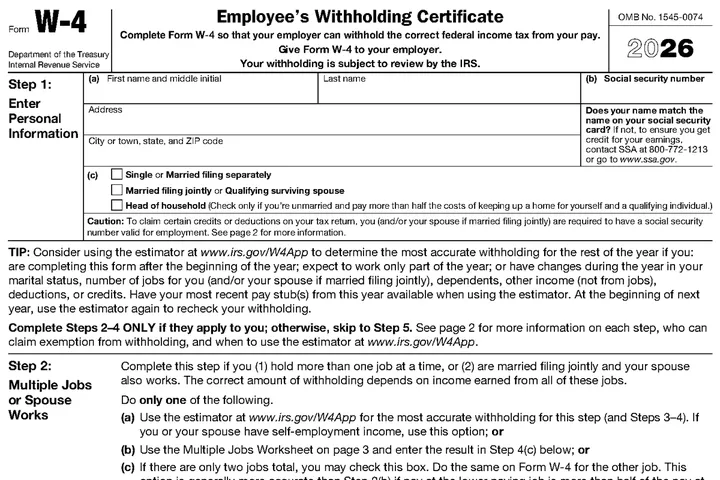
Form W-4
Employee's Withholding Certificate. Every new employee. Filed with Kept by the employer; sent to the IRS only when directed.
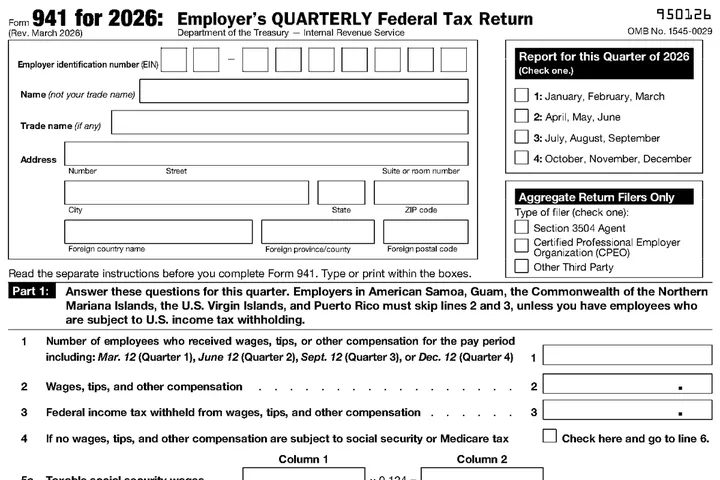
Form 941
Employer's Quarterly Federal Tax Return. Any employer paying wages (unless on 944 or 943). Filed with IRS (e-file or paper).
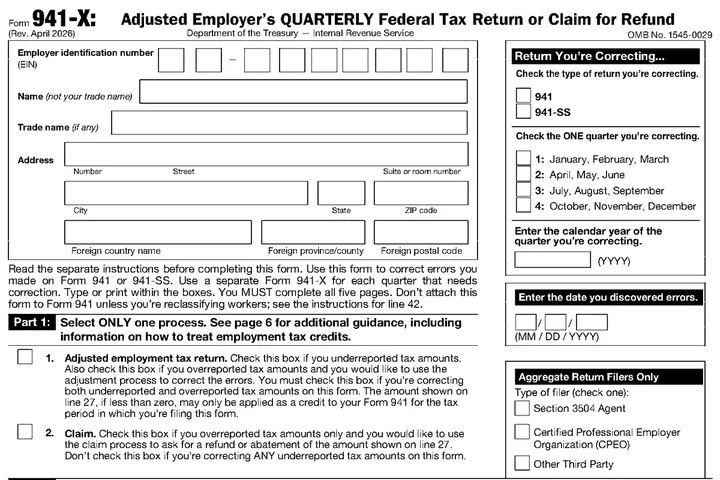
Form 941-X
Adjusted Employer's Quarterly Federal Tax Return or Claim for Refund. When a filed 941 was wrong. Filed with IRS (e-file through MeF, or paper).
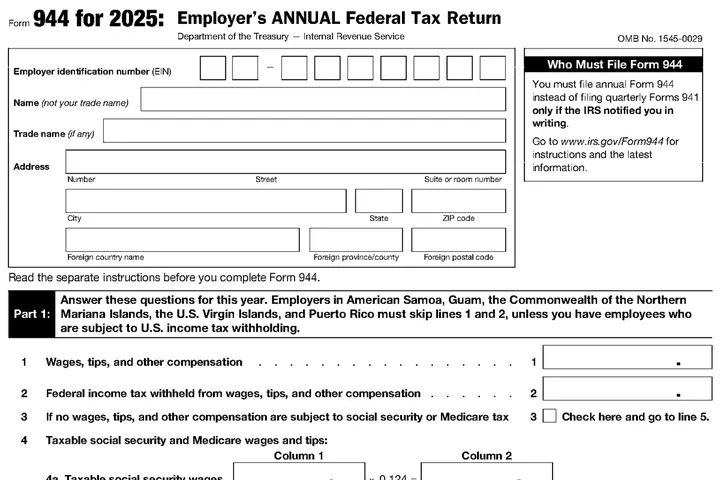
Form 944
Employer's Annual Federal Tax Return. Employers the IRS notifies to file annually. Filed with IRS (e-file or paper).
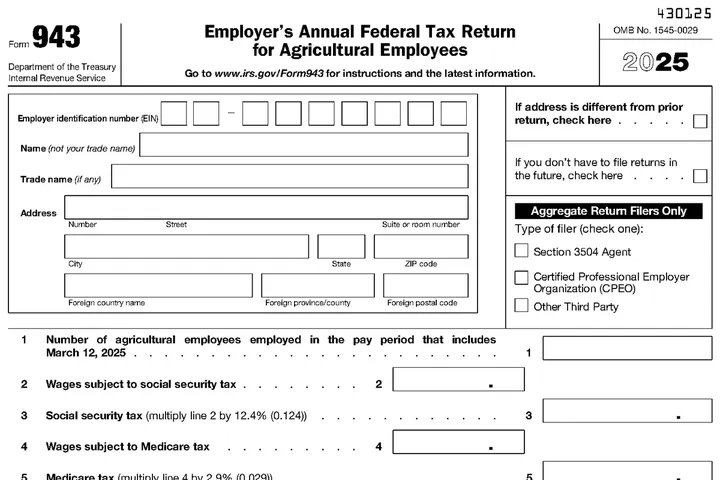
Form 943
Employer's Annual Federal Tax Return for Agricultural Employees. Employers of farmworkers. Filed with IRS (e-file or paper).
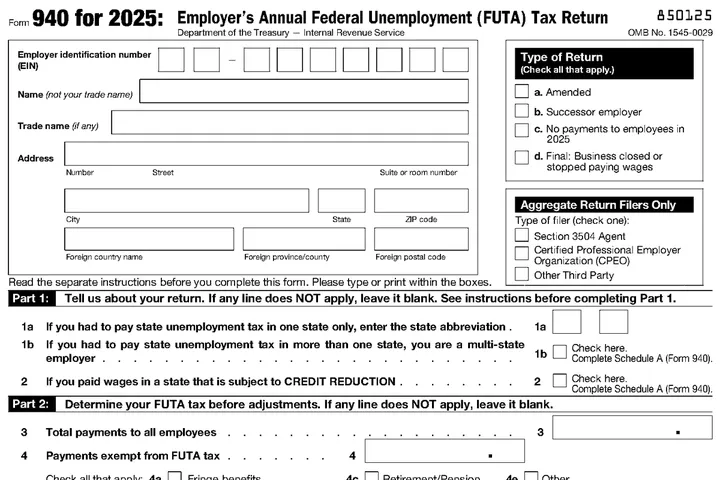
Form 940
Employer's Annual Federal Unemployment (FUTA) Tax Return. $1,500 of wages in a quarter, or an employee in 20 weeks. Filed with IRS (e-file through MeF or paper).
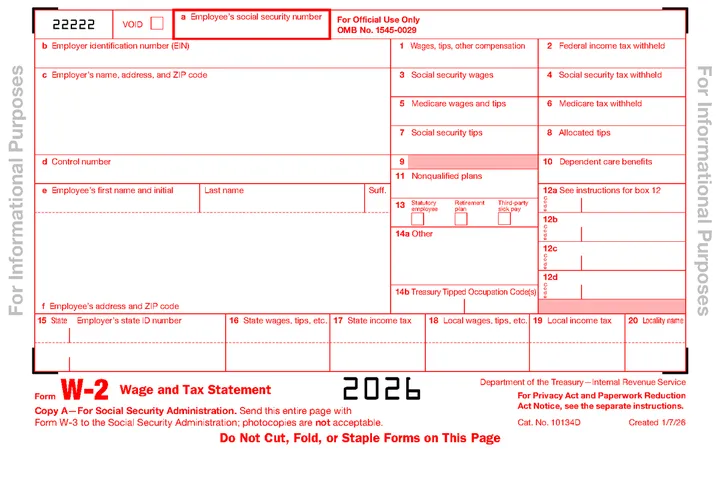
Form W-2
Wage and Tax Statement. Wages paid to employees. Filed with Social Security Administration (BSO e-file or paper Copy A with Form W-3).
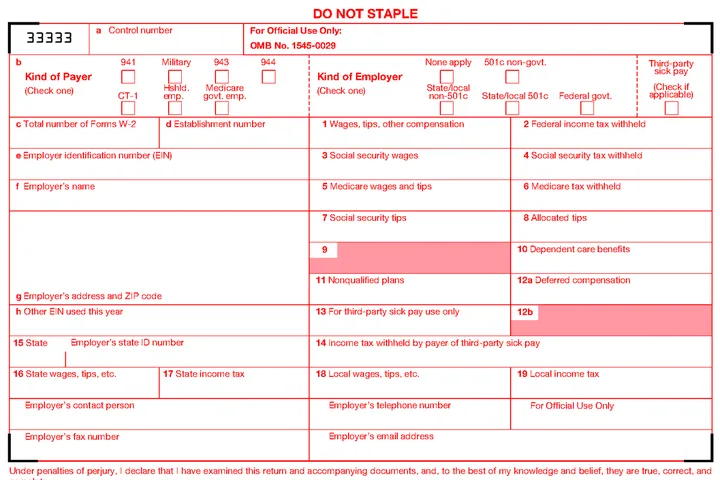
Form W-3
Transmittal of Wage and Tax Statements. With paper W-2s. Filed with Social Security Administration (paper only, with Copy A of Forms W-2).
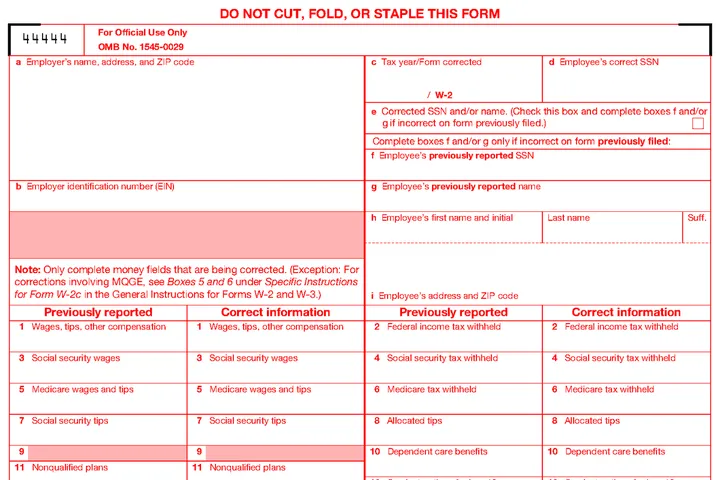
Form W-2c
Corrected Wage and Tax Statement. When a filed W-2 was wrong. Filed with Social Security Administration (BSO e-file or paper Copy A with Form W-3c).
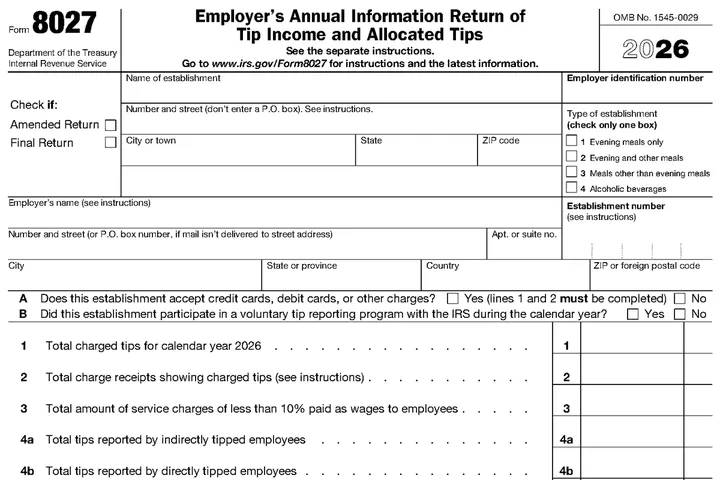
Form 8027
Employer's Annual Information Return of Tip Income and Allocated Tips. Large food or beverage establishments. Filed with IRS (e-file through IRIS, or paper to Ogden).
Withholding returns
Annual returns that report and reconcile federal income tax withheld outside payroll: Form 945 for backup withholding and other nonpayroll withholding, and Form 1042 for withholding on payments to foreign persons, reconciled with the Forms 1042-S.
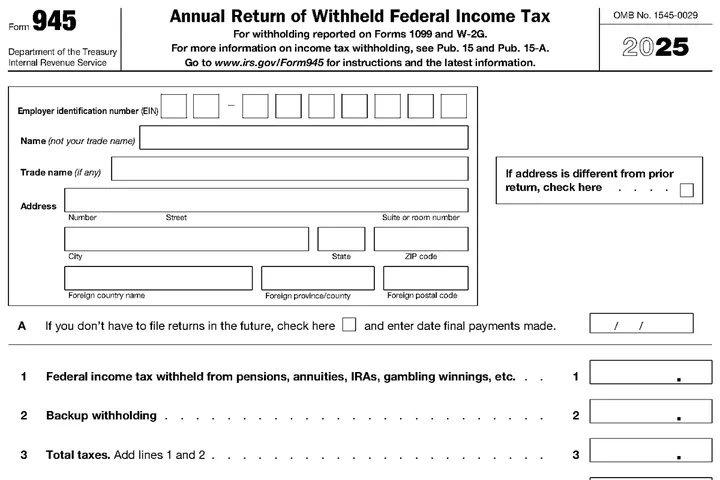
Form 945
Annual Return of Withheld Federal Income Tax. Any nonpayroll federal income tax withholding. Filed with IRS (e-file or paper).
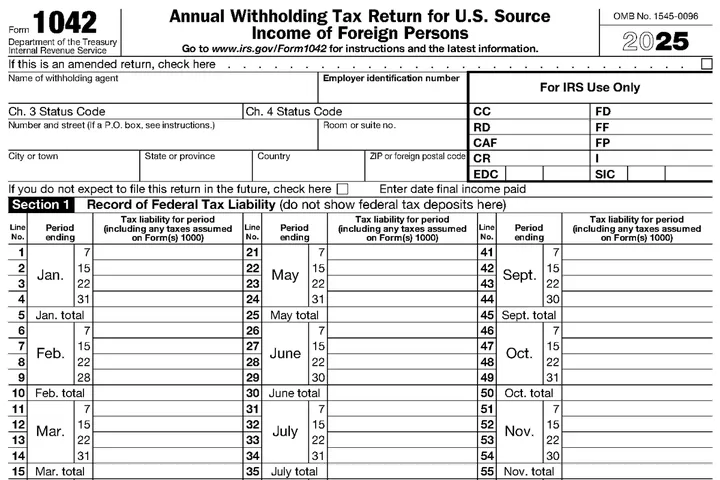
Form 1042
Annual Withholding Tax Return for U.S. Source Income of Foreign Persons. Withholding agents paying foreign persons. Filed with IRS (e-file through MeF; paper to Ogden only if not required to e-file).
Health coverage (ACA) returns
Filed by applicable large employers, insurers and other coverage providers. They are information returns subject to the same penalties, but they are filed electronically through the AIR system, not IRIS.
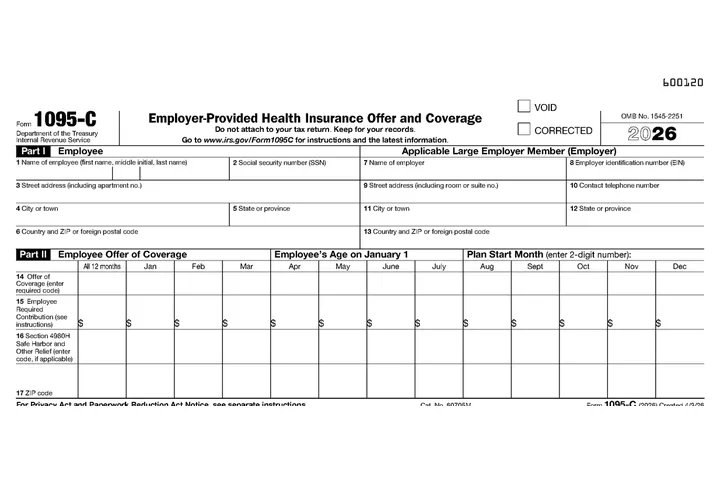
Form 1095-C
Employer-Provided Health Insurance Offer and Coverage. Applicable large employers (50 or more full-time employees). Filed with IRS through the AIR system (paper only under 10 returns).
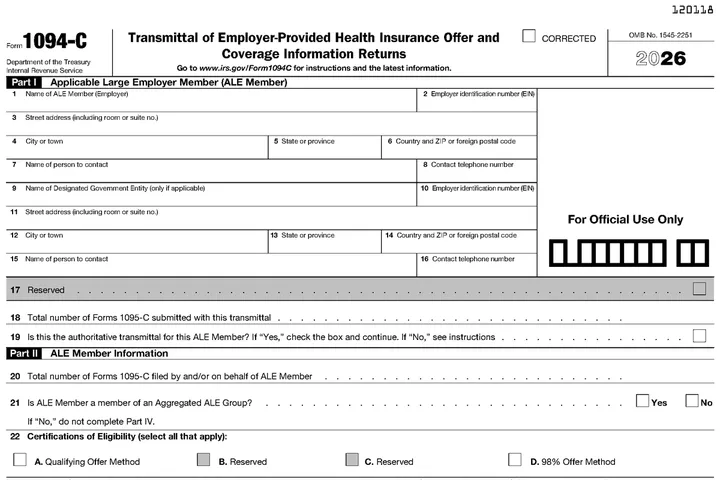
Form 1094-C
Transmittal of Employer-Provided Health Insurance Offer and Coverage Information Returns. Transmittal for Forms 1095-C. Filed with IRS through the AIR system (paper only under 10 returns).
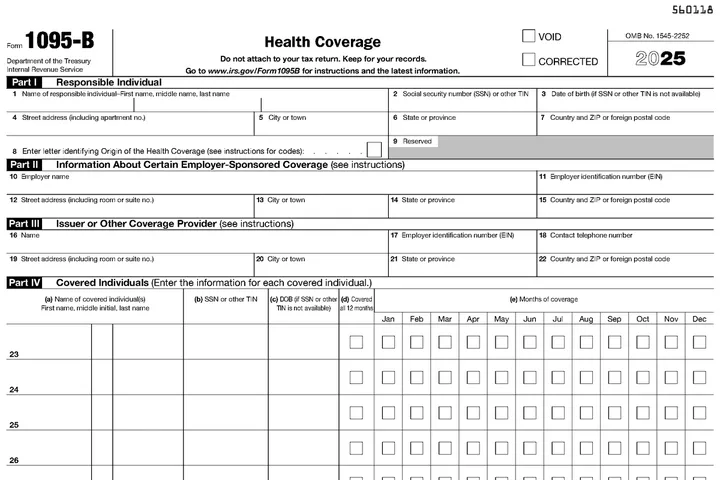
Form 1095-B
Health Coverage. Providers of minimum essential coverage. Filed with IRS through the AIR system (paper only under 10 returns).
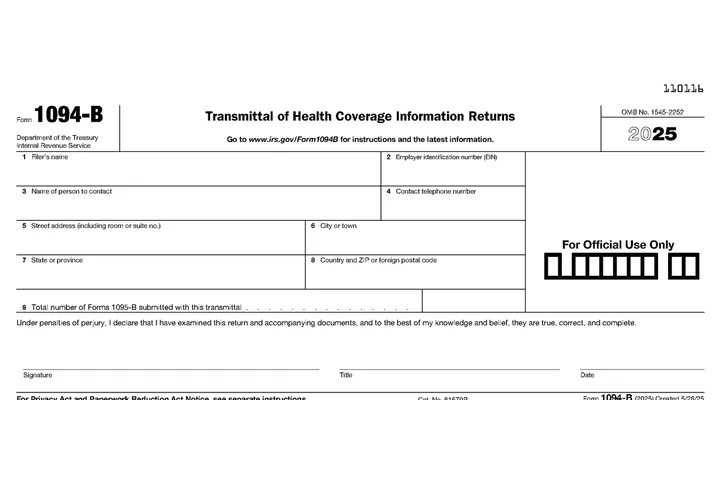
Form 1094-B
Transmittal of Health Coverage Information Returns. Transmittal for Forms 1095-B. Filed with IRS through the AIR system (paper only under 10 returns).
Paper transmittal
Form 1096 goes only with information returns filed on paper; e-filed returns need none.
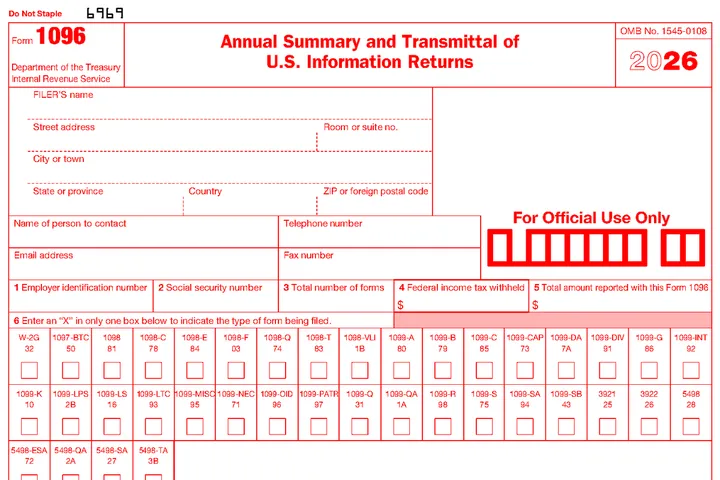
Form 1096
Annual Summary and Transmittal of U.S. Information Returns. Paper filers of 1099, 1098, 5498, W-2G. Filed with IRS (paper only, to the Submission Processing Center for your state).
What changed for 2026
For the 2027 season (the 2026 forms) and what is still pending, see what's coming for 2027.
- Publication 1099. The General Instructions for Certain Information Returns became a numbered publication for tax year 2026. The per-form instructions still exist separately and now point to "the current Pub. 1099" for the general rules.
- $2,000 threshold. P.L. 119-21 (July 2025) raised the section 6041 and 6041A amounts from $600 to $2,000 for payments after 2025, indexed from 2027. It reaches 1099-NEC box 1a, most of 1099-MISC, 1099-DIV liquidations, 1099-G grants and paid leave, and the general W-2G threshold. Royalties ($10), attorney gross proceeds ($600), 1099-S ($600) and 1099-C ($600) are under other sections and did not move. Backup withholding thresholds moved with the reporting thresholds (IRC 3406(b)(6)).
- 1099-K. The same law repealed the $600 phase-down retroactively; TPSOs report at more than $20,000 and more than 200 transactions, with a backup-withholding rule tied to the same tests or to prior-year reportable payments.
- New boxes. Cash tips, Treasury Tipped Occupation Codes and overtime compensation on 1099-NEC and 1099-MISC; cash tips on 1099-K; family leave benefits on 1099-G (box 10); digital assets on 1099-S (box 2c); checkboxes 7b to 7d on 1099-R. Excess golden parachute payments moved from the MISC to the NEC.
- IRIS only. FIRE is retired after the 2026 filing season; from filing season 2027 every e-filed information return, original or correction, goes through IRIS, and references to Pub. 1220 were removed from the general instructions. The FIRE to IRIS page covers the migration.
- Retired forms. Form 1098-MA and Form 1099-H can no longer be filed; Form 1098-VLI (vehicle loan interest) is new; Forms 5498-TA and 1099-LPS are in development (1099-LPS has since been finalized, in October 2026).
What every information return shares
The general rules in Publication 1099 apply to all of them. A payer needs an EIN to file; the filer name and EIN must match the Form 945 that reports the withholding. Recipient statements may carry a truncated TIN (except W-2G) but the IRS copy never may. A sole proprietor or disregarded LLC is reported under the individual's name first and the business name second. Statements may be furnished electronically only with the recipient's affirmative electronic consent and the required disclosures, posted through October 15. Copies are kept for three years from the due date, four if any withholding was reported or the form is a 1099-C. Payments to corporations are generally not reportable, with the named exceptions: medical payments, attorney fees and gross proceeds, fish purchases, substitute payments, 1099-K, 1099-B for S corporations, barter, 1099-A and 1099-C, and federal executive agency vendor payments.
The penalty for a late, incorrect or missing-TIN return is IRC 6721 ($60 within 30 days, $130 by August 1, $340 after, $690 for intentional disregard, for the 2026 forms filed in 2027 under Rev. Proc. 2025-32) with a matching IRC 6722 penalty for the payee statement, reduced by the de minimis rule for corrections made by August 1 and by the $100/$25 dollar-error safe harbor. The 972CG guide and estimator cover the computation and the reasonable-cause defense.